
Premium Bonds Under Scrutiny: Who Really Wins?
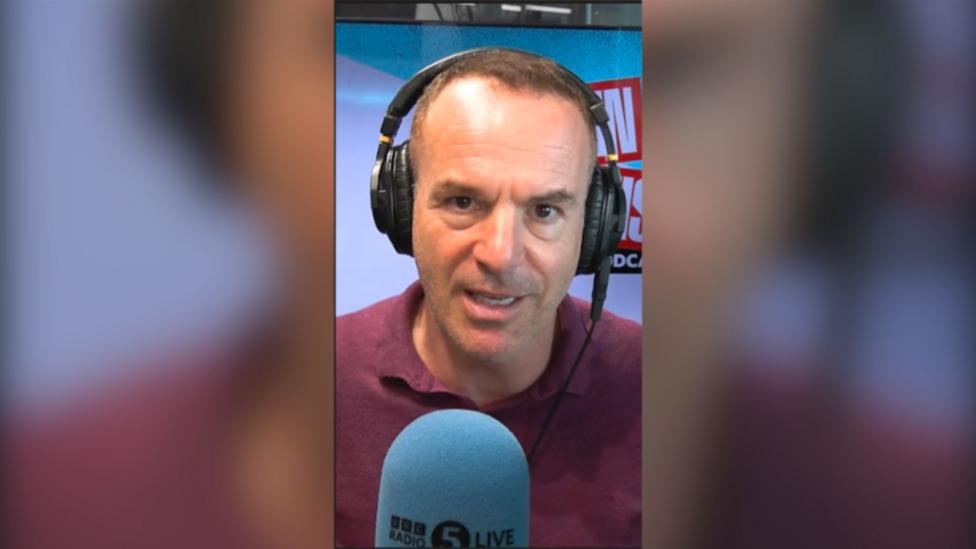
Premium bonds remain the United Kingdom's most popular savings product, with millions holding them through National Savings and Investments. However, financial expert Martin Lewis recently sparked debate by questioning whether every saver benefits equally from this iconic scheme. His analysis highlights a critical distinction between those who profit from the prize draw and those who might earn more elsewhere.
The bonds, backed by HM Treasury, replace traditional interest with a monthly prize draw. While this structure appeals to gamblers at heart, it creates uneven outcomes. Lewis points out that average returns can lag behind standard savings accounts, especially for those with smaller balances. This revelation challenges the assumption that premium bonds are universally beneficial.
How Premium Bonds Compare to Standard Savings Accounts
Current NS&I data shows the premium bond prize fund rate sits at 4.00 percent, but this represents the average, not a guarantee. Many savers receive significantly less, particularly in months without wins. Meanwhile, top easy-access savings accounts now offer around 5 percent, providing guaranteed growth without the lottery element.
For higher-rate taxpayers, the tax advantage of premium bonds remains compelling. Winnings are completely tax-free, unlike interest from standard accounts which may trigger tax liabilities. This makes the bonds particularly attractive to those earning above the personal savings allowance threshold, a point Lewis emphasizes in his assessment.
Basic-rate taxpayers with smaller savings pots often fare worse. A £1,000 balance, for instance, yields an expected annual return of just £40, while a comparable savings account might deliver £50. Over several years, this difference compounds, potentially costing savers hundreds of pounds in lost growth.
Martin Lewis's Verdict on Premium Bond Eligibility
Lewis's guidance categorizes savers into distinct groups based on their financial circumstances. Those with emergency funds, typically three to six months of expenses, should prioritize liquidity and guaranteed returns. Premium bonds offer instant access, but the unpredictable prize structure undermines their reliability for essential savings.
Conversely, savers with substantial balances, generally above £10,000, may find premium bonds more favorable. The odds of winning improve with larger holdings, and the statistical likelihood of achieving near-average returns increases significantly. This makes the product suitable for those with surplus cash beyond their immediate needs.
Higher-rate taxpayers receive the strongest recommendation, as the tax-free nature of prizes effectively boosts their real returns. For a 40 percent taxpayer, a 4 percent tax-free yield equates to a taxable equivalent of 6.67 percent, a figure difficult to match elsewhere in the current market.
Historical Performance and Prize Distribution Trends
Since their introduction in 1956, premium bonds have evolved significantly. The prize fund rate has fluctuated with market conditions, reaching historic highs during periods of elevated interest rates. However, the distribution of prizes remains heavily skewed, with most winners receiving £25 or £50, while the £1 million jackpots remain exceptionally rare.
NS&I data reveals that roughly one in 22,000 bonds wins a prize each month, translating to a 1 in 22,000 chance per £1 unit. This means a £100 holding offers only a 0.45 percent monthly chance of winning anything at all. Such statistics underscore the importance of understanding probability before committing funds.
Industry analysts note that premium bonds have historically underperformed equities over long horizons, but their capital security and tax advantages make them a unique hybrid product. This dual nature appeals to risk-averse savers seeking excitement without market exposure, though financial planners often recommend more predictable alternatives.
Practical Strategies for Maximizing Premium Bond Returns
For those committed to premium bonds, timing and balance size matter. Maximizing holdings to the £50,000 limit improves odds proportionally, while maintaining a diversified portfolio ensures liquidity. Savers should also monitor NS&I rate changes, as the prize fund adjusts periodically based on economic conditions.
Lewis advises savers to compare current market rates regularly, especially given the recent volatility in fixed-term bonds. A two-year fixed account offering 5.5 percent may outperform premium bonds for most investors, despite lacking the thrill of potential jackpots. This pragmatic approach prioritizes long-term wealth accumulation over short-term excitement.
Additionally, savers should consider their time horizon. Premium bonds suit those who can afford to wait for prizes, while those needing predictable income should look elsewhere. The product's flexibility, including instant withdrawals and tax-free status, remains a significant advantage, but it cannot compensate for consistently below-market returns.
Future Outlook for UK Savings Products
As interest rates stabilize, the gap between premium bonds and traditional accounts may narrow or widen depending on monetary policy. The Bank of England's decisions directly influence NS&I pricing, which must balance consumer appeal with Treasury funding requirements. Savers should stay informed about these shifts to optimize their strategies.
Regulatory changes could also reshape the landscape, with potential reforms to savings allowances or NS&I's mandate. Financial experts anticipate continued innovation in savings products, including more flexible ISAs and hybrid accounts that combine guaranteed returns with prize elements. These developments may eventually challenge premium bonds' dominance.
Ultimately, the decision rests on individual circumstances, including tax bracket, savings goals, and risk tolerance. While premium bonds remain a legitimate option, they are no longer the default choice for every saver. A thorough analysis of personal finances, as advocated by Lewis, ensures savers make informed decisions aligned with their unique needs.
