
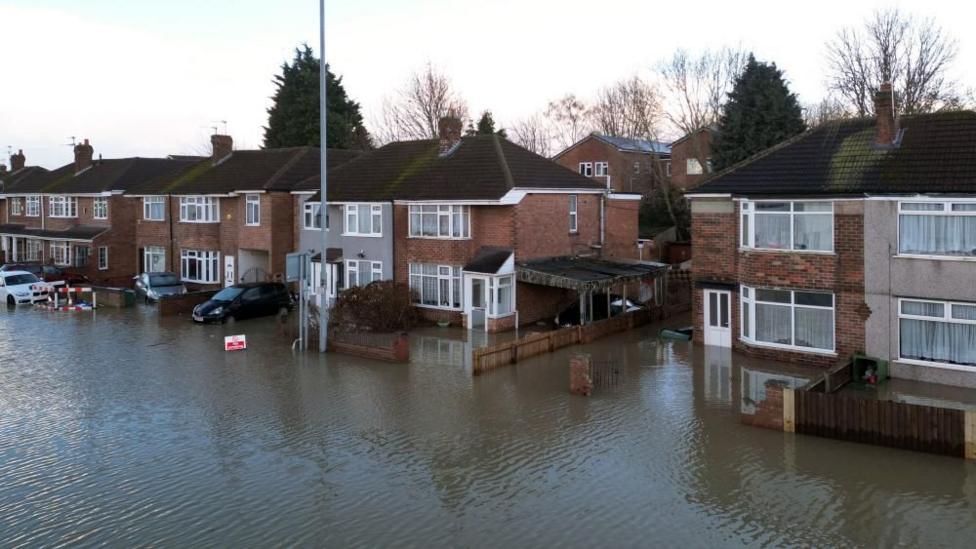
Aviva Chief Issues Stark Flood Warning
Amanda Blanc, chief executive of Aviva, one of Britain's largest insurers, has issued a stark warning that England is “for sure” constructing homes that may become uninsurable in the future due to escalating flood risks. Her statement, delivered during a recent industry briefing, has reignited concerns over the nation's planning policies and climate resilience. The comments come as insurers grapple with rising flood-related claims and increased pressure from environmental factors.
Blanc's remarks highlight a growing disconnect between housing development targets and environmental realities. She emphasized that current building practices in flood-prone areas are unsustainable, potentially leaving homeowners without coverage options. The Aviva chief's assessment aligns with internal company data showing increased frequency of extreme weather events. Industry analysts note that her public stance signals a significant shift in how major insurers view long-term property risks.
Flood Risk Data and Insurance Industry Concerns
Recent government assessments indicate that millions of properties across England are already at risk of flooding, with projections suggesting this number will rise dramatically over the next decade. Insurers have responded by adjusting premium models and coverage availability. Aviva's own risk modeling shows that some new developments in high-risk zones could face premium increases of 300% or more within years, potentially making coverage financially prohibitive for average homeowners.
The insurance sector has long warned about the implications of building on flood plains. Official records from previous flood events show that between 2015 and 2020, insurance payouts for flood damage exceeded £2.5 billion annually. These figures have driven many insurers to reconsider their exposure in vulnerable regions. Blanc's comments reflect a broader industry consensus that without meaningful planning reform, the situation will worsen significantly.
Industry analysts point out that the issue extends beyond just coastal areas. Inland flooding from overwhelmed drainage systems and river overflows has become increasingly common. Urban development has exacerbated these problems by replacing natural water absorption surfaces with impermeable concrete. This has created a perfect storm of environmental and infrastructural challenges that insurers are now forced to confront.
Government Planning Policies Under Scrutiny
The government's housing targets have been criticized for prioritizing quantity over quality and location safety. Current planning guidelines allow development in areas that insurers deem high-risk. Blanc's warning adds pressure on policymakers to reconsider these frameworks. Environmental agencies have repeatedly called for stricter flood risk assessments before planning permissions are granted.
Recent regulatory filings show that the government has acknowledged the need for reform but has yet to implement comprehensive changes. The Department for Levelling Up, Housing and Communities has commissioned studies into sustainable development practices, though critics argue these have been slow to produce actionable results. Local councils face competing pressures to meet housing targets while protecting residents from environmental hazards.
The issue has become politically sensitive, with some arguing that stricter flood regulations could slow housing development and exacerbate affordability crises. However, Blanc and other industry leaders counter that building uninsurable homes is economically and socially irresponsible. They argue that the long-term costs of flood damage far outweigh short-term development gains, both for individual homeowners and the broader economy.
Economic and Social Impact on Homeowners
For prospective homeowners, the insurability of a property is becoming a critical factor in purchasing decisions. Mortgage lenders typically require valid insurance coverage, meaning uninsurable homes would be effectively unsellable. This could trap existing homeowners in properties they cannot sell and create pockets of stranded assets across the country. The social implications are significant, particularly for lower-income families who may be more likely to live in high-risk areas.
Property values in flood-prone areas have already begun to show signs of decline in some regions. Real estate data indicates that homes with a history of flooding sell for 20-30% less than comparable properties in safe zones. As awareness of climate risks grows, this price differential is expected to widen, potentially creating significant wealth inequality between those who can afford safe housing and those who cannot.
Insurance experts suggest that the industry may need to develop new products and partnerships to address the emerging crisis. Some have proposed government-backed flood insurance programs similar to those in other countries, while others advocate for investment in property-level flood defenses. Aviva has already invested heavily in flood resilience research, supporting nature-based solutions like wetland restoration and sustainable drainage systems.
Future Outlook and Recommended Reforms
Looking ahead, Blanc's warning serves as a catalyst for urgent action. She has called for a fundamental reassessment of where and how England builds new homes. This includes implementing stricter flood risk standards, investing in infrastructure improvements, and creating a national strategy for climate adaptation. Without such measures, the gap between housing needs and environmental safety will continue to widen.
Industry analysts recommend that the government adopt a more proactive approach, including mandatory flood risk disclosure for all property transactions and stronger enforcement of existing regulations. They also suggest that planning authorities should have access to real-time flood data and climate projections when making decisions. These reforms would help ensure that new developments are both sustainable and insurable in the long term.
The insurance industry stands ready to work with policymakers, but time is running short. As climate patterns become more unpredictable, the window for implementing effective solutions narrows. Blanc's message is clear: the decisions made today about where and how we build will determine whether future generations can protect their homes and investments. The responsibility now lies with planners, developers, and government officials to act decisively.
Conclusion: A Call for Urgent Action
Amanda Blanc's warning represents a critical juncture for England's housing and insurance sectors. The prospect of uninsurable homes is no longer a distant hypothetical but an imminent reality that demands immediate attention. As climate change accelerates, the intersection of housing policy, environmental protection, and insurance viability will become increasingly central to national discourse. The decisions made in the coming years will shape the resilience of communities for generations.
