
A Personal Decision With Long-Term Financial Impact
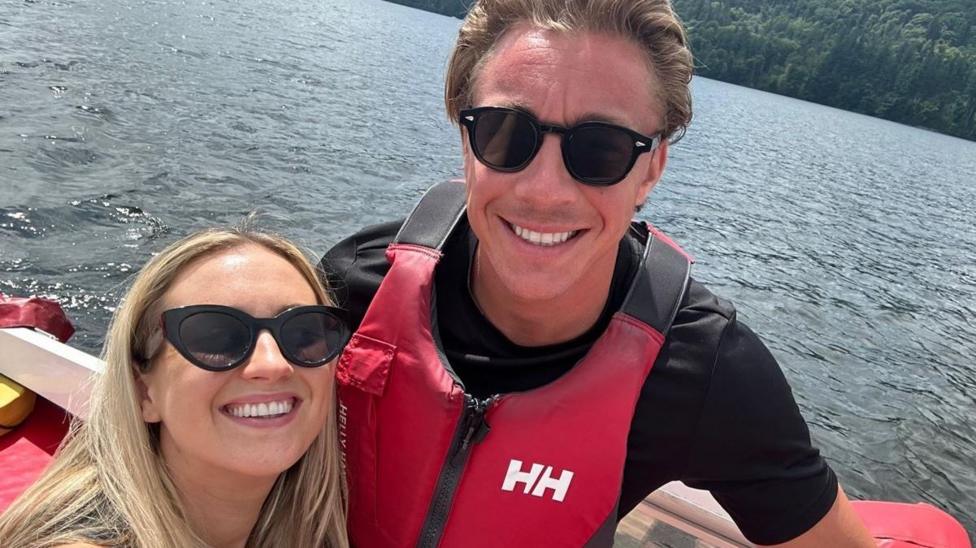
When Molly and Taylor Haylett welcomed their first child, they made a deliberate change to their household finances. Molly asked her husband to pay into her pension. This decision, rooted in the financial realities of parenthood, highlights a growing conversation about retirement savings for mothers.
The couple's approach is straightforward. During Molly's maternity leave, her income dropped significantly, which reduced her own pension contributions. By asking Taylor to contribute to her pension instead, they aimed to offset the long-term financial penalty that often follows a career break for childcare.
Understanding the Pension Gap for Mothers
Official records from the Department for Work and Pensions show that women often retire with substantially smaller pension pots than men. This gap is frequently attributed to time out of the workforce for caregiving. Even a short period of reduced earnings can compound over decades, leading to thousands of pounds less in retirement income.
The Hayletts' strategy directly addresses this issue. By transferring some of the household's income into Molly's pension, they are effectively maintaining her retirement savings trajectory. This simple act can help prevent the financial disparity that many mothers face later in life.
How the Arrangement Works in Practice
The couple's plan involves Taylor making contributions to Molly's pension from his own salary. This is possible under UK pension rules, which allow individuals to contribute to another person's pension, subject to annual allowance limits. The contributions benefit from tax relief at the marginal rate, making it a tax-efficient way to save.
For Molly, this means her pension continues to grow even though she is not earning a full salary. For Taylor, it is a shared investment in their future as a family. The arrangement requires careful budgeting, but the couple views it as a non-negotiable part of their long-term financial plan.
Expert Views on Spousal Pension Contributions
Industry analysts note that spousal pension contributions are an underused tool for closing the gender pension gap. Financial advisers often recommend that higher-earning partners consider this strategy, especially when one partner takes time off for childcare. It ensures that the non-earning partner does not lose out on years of compound growth.
However, experts caution that couples should consider their overall financial picture first. Paying off high-interest debt or building an emergency fund may take priority. But for families with stable finances, redirecting some income into a partner's pension can be a powerful move for long-term security.
The Broader Context of Family Finance Planning
The Hayletts' story is part of a wider trend of couples becoming more strategic about their finances after having children. From shared bank accounts to separate investments, modern families are finding new ways to balance immediate needs with future goals. Pension planning, once a personal responsibility, is increasingly becoming a joint decision.
This shift is also reflected in policy discussions. Some campaigners argue that the state should do more to protect mothers' pensions, such as automatically crediting pension contributions during parental leave. Until then, individual actions like those taken by the Hayletts remain crucial.
Practical Steps for Couples Considering This Move
For couples interested in a similar arrangement, the first step is to check the annual allowance for pension contributions, which currently stands at £60,000 per person per year. This includes all contributions, whether from an employer, the individual, or a third party. Staying within this limit avoids a tax charge.
Next, couples should consider the tax implications. Contributions made to a partner's pension are not eligible for tax relief unless the receiving partner has sufficient UK earnings. In cases where the mother has no income, the maximum contribution that receives tax relief is £2,880 per year, which is grossed up to £3,600.
Finally, it is essential to communicate openly about long-term goals. The Hayletts' decision worked because both partners agreed on the importance of maintaining Molly's pension. Without that shared vision, such a financial arrangement could cause resentment or confusion down the line.
Looking Ahead: A Model for Future Parents
As more families share their financial strategies, the stigma around discussing money is slowly fading. The Hayletts' approach offers a practical example for other parents who worry about the long-term cost of childcare. It shows that with careful planning, the impact of a career break on retirement savings can be mitigated.
Ultimately, the decision to ask a partner to pay into your pension is about fairness and foresight. It acknowledges that raising a child is a joint effort, and so too should be the financial preparation for the future. For Molly and Taylor, it is a choice they are confident will pay off for decades to come.
