
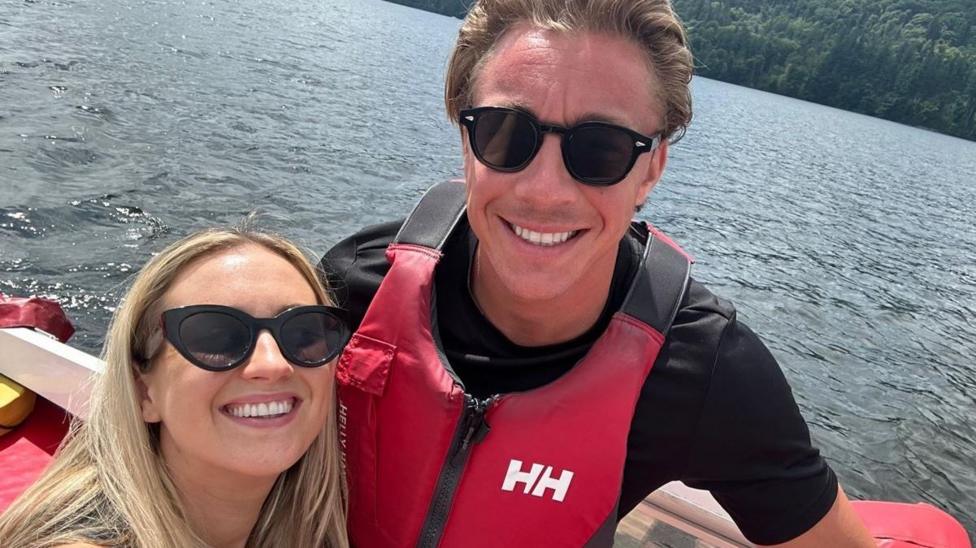
A Family Finance Shift: The Hayletts' Pension Decision
When Molly and Taylor Haylett welcomed their first child, they made a significant change to their household finances. Molly asked Taylor to pay into her pension instead of boosting his own. This decision, she explains, was about long-term security and fairness, not just immediate savings. The couple's approach highlights a growing conversation among financial planners about how parenthood reshapes retirement planning.
The Hayletts, who live in the United States, realized that Molly's career break for childcare would create a gap in her retirement savings. Taylor, who continued working full-time, had the capacity to contribute more. By redirecting some of his income into Molly's pension, they aimed to balance their long-term financial futures. Their story offers a practical case study for other families navigating similar transitions.
The Hidden Cost of Childcare on Retirement Savings
Financial experts note that parents, especially mothers, often face a 'motherhood penalty' in retirement. Time out of the workforce means fewer years of pension contributions, which can compound significantly over decades. According to industry analysts, a five-year career break can reduce a person's retirement income by as much as 20 percent. This makes proactive planning, like the Hayletts', critical for closing the gap.
The couple's strategy also addresses the emotional and psychological aspects of money management. Molly told official records that asking Taylor to contribute felt like a conversation about partnership, not charity. It was a way to acknowledge that her unpaid labor at home had equal value to his paid work outside it. This framing helped them make the decision without resentment or guilt.
How Spousal Pension Contributions Work in Practice
Spousal pension contributions are a legal and tax-efficient way to support a partner's retirement. In many jurisdictions, including the US and UK, one spouse can contribute to the other's pension fund, subject to annual limits. These contributions often qualify for tax relief, making them an attractive option for couples with uneven incomes. The Hayletts took advantage of this mechanism to optimize their savings.
However, the rules vary by country and pension scheme. In the UK, for example, contributions to a spouse's pension are capped by the recipient's annual allowance, which is typically £60,000. In the US, IRA and 401(k) rules differ, with spousal IRAs offering a specific pathway. Couples must consult a financial advisor or check official guidelines to ensure compliance and maximize benefits.
The Broader Impact on Family Financial Planning
The Hayletts' decision reflects a broader trend in family finance: moving away from individual accounts toward a household-based approach. Planners report that more couples are pooling resources to address shared goals like childcare, education, and retirement. This shift requires open communication about money, which can strengthen relationships but also demands careful documentation and legal awareness.
For Molly and Taylor, the change also meant adjusting their monthly budget. They reallocated funds from dining out and travel to ensure the pension contributions didn't strain their cash flow. This disciplined approach, they explained, was easier than they expected because they treated it as a non-negotiable expense. The result was a more secure financial foundation for their growing family.
Expert Insights: Why This Strategy Makes Sense
Industry analysts say the Hayletts' approach is a smart move for many couples, particularly those with a single primary earner. It ensures both partners accumulate retirement savings, reducing the risk of poverty in old age for the non-working spouse. Additionally, it can lower the household's overall tax bill by shifting income into a lower tax bracket, depending on individual circumstances.
Yet experts caution that this strategy isn't for everyone. Couples with high debt or inadequate emergency funds should prioritize those issues first. Moreover, if the contributing spouse has a higher earning potential, it might be better to maximize their pension instead. Each family must evaluate its unique situation, considering factors like age, health, and career trajectory.
Looking Ahead: The Future of Family Retirement Planning
As more families adopt shared financial strategies, pension providers are adapting. Some schemes now offer joint accounts or flexible contribution structures to accommodate spousal transfers. Policymakers are also exploring reforms to make retirement savings more equitable for caregivers. The Hayletts' story is a timely reminder that small, deliberate choices can have profound long-term effects.
For Molly and Taylor, the decision has already paid off in peace of mind. They no longer worry about the financial impact of Molly's career break, knowing that her pension is growing steadily. Their advice to other couples is simple: have the conversation early, crunch the numbers together, and don't be afraid to ask for help. Planning for the future, they say, is an act of love.
The couple's experience also underscores the importance of revisiting financial plans at major life milestones. A child's birth, a job change, or a move can all alter the optimal allocation of resources. By staying flexible and informed, families can navigate these transitions with confidence. The Hayletts' approach offers a blueprint for turning a potential financial setback into a strategic advantage.
