
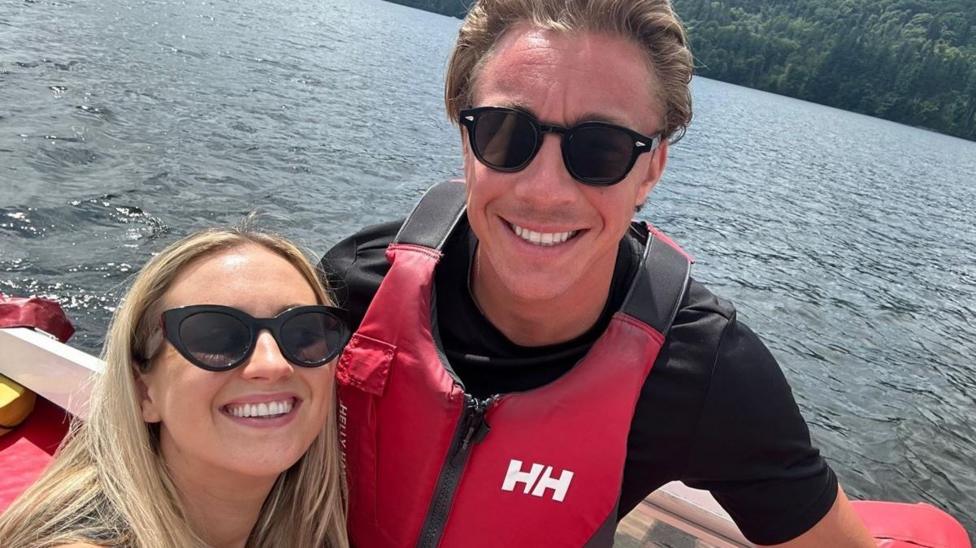
A Family Financial Reset
When Molly and Taylor Haylett welcomed their first child, they realized their financial strategy needed a major overhaul. The couple, both in their early thirties, had previously managed money separately. But with reduced income during maternity leave and rising childcare costs, they decided to rethink how they saved for retirement, leading Molly to ask Taylor to pay into her pension instead of his own.
The decision wasn't about distrust or lack of commitment. Rather, it was a calculated move to balance their long-term financial security. By redirecting contributions to Molly's pension, they aimed to close the gender pension gap that often widens when women take career breaks for childcare. The Hayletts' story offers a practical blueprint for other couples navigating similar financial crossroads.
Why the Pension Gap Widens After Parenthood
Research consistently shows that women retire with significantly smaller pensions than men. This disparity stems from career interruptions, part-time work, and lower lifetime earnings. When a child arrives, many mothers reduce hours or leave the workforce entirely, missing out on employer contributions and compound growth during those years. The Hayletts recognized this risk early and acted preemptively.
Molly, who had built a solid pension foundation in her pre-child career, faced a potential slowdown in contributions. Taylor, meanwhile, continued full-time employment. By shifting some of his pension contributions to Molly's pot, they ensured her retirement savings kept growing steadily, even while her income dipped. This approach also leveraged tax relief more efficiently in their specific income bracket.
How the Hayletts Restructured Their Contributions
The couple's strategy was straightforward: Taylor reduced his own pension contributions to the minimum needed to secure his employer's match, then directed the surplus into Molly's pension. They also increased Molly's contributions to capture full tax relief, since she had unused annual allowance from previous years. This rebalancing allowed them to maintain overall household savings without straining their budget.
They didn't stop at pension transfers. The Hayletts also reviewed their emergency fund and adjusted their monthly budget to account for new childcare expenses. They prioritized building a cash buffer for unexpected costs, which gave them peace of mind as they navigated the unpredictable early months of parenting. This holistic approach ensured that their pension strategy didn't compromise their short-term financial stability.
Legal and Tax Considerations for Couples
In the UK, pension contributions are generally tax-deductible up to certain limits, and unused allowances can be carried forward for up to three years. The Hayletts exploited this rule to maximize Molly's contributions without exceeding her annual allowance. However, they were careful to stay within the lifetime allowance threshold to avoid punitive tax charges, a common pitfall for high earners.
For married couples or civil partners, pension sharing on divorce is a well-known option, but voluntary rebalancing during marriage is less common. Financial advisers often recommend that couples consider their combined pension pots as a single entity, rather than viewing them in isolation. This mindset shift can lead to more efficient tax planning and better long-term outcomes, as the Hayletts discovered.
The Impact on Their Daily Finances
Redirecting contributions meant Taylor's take-home pay increased slightly, since his pension contributions were lower, while Molly's decreased because she boosted hers. However, they adjusted their joint budget to offset this, treating the household as a single economic unit. They also set up automatic transfers to ensure consistency, avoiding the temptation to skip contributions during tight months.
The couple also took advantage of government schemes like tax-free childcare and, when eligible, the 30 hours free childcare offer. These benefits reduced their out-of-pocket childcare costs, freeing up more cash to allocate toward savings. By combining these strategies, they maintained their lifestyle while building a more secure retirement future for both partners.
Broader Lessons for New Parents
The Hayletts' story highlights the importance of proactive financial planning during major life transitions. Many couples default to keeping finances separate, but this can perpetuate inequalities, especially when one partner sacrifices career progression for family. Experts suggest that couples should have open conversations about long-term goals and consider how to balance pension contributions fairly, even if one earns less.
Financial advisers also recommend reviewing pension plans annually, especially after life events like a birth, marriage, or job change. The rules around pension allowances and tax relief can change, so staying informed is crucial. For those unsure where to start, consulting a regulated financial planner can provide personalized guidance, but even simple steps like rebalancing contributions can make a significant difference.
Future Outlook and Retirement Security
The Hayletts plan to continue this arrangement until their child starts school, at which point they'll reassess their contributions. By then, Molly's pension will have received several years of extra payments, potentially growing into a substantial sum thanks to compound interest. This forward-thinking approach gives them confidence that they'll both enjoy a comfortable retirement, without one partner being left behind.
Their strategy also serves as a reminder that pension planning isn't just about maximizing your own pot—it's about securing your family's financial future. By sharing the burden and the benefits, couples can build a more equitable foundation. As the Hayletts demonstrate, a little proactive planning can go a long way toward closing the pension gap and ensuring long-term stability.
