
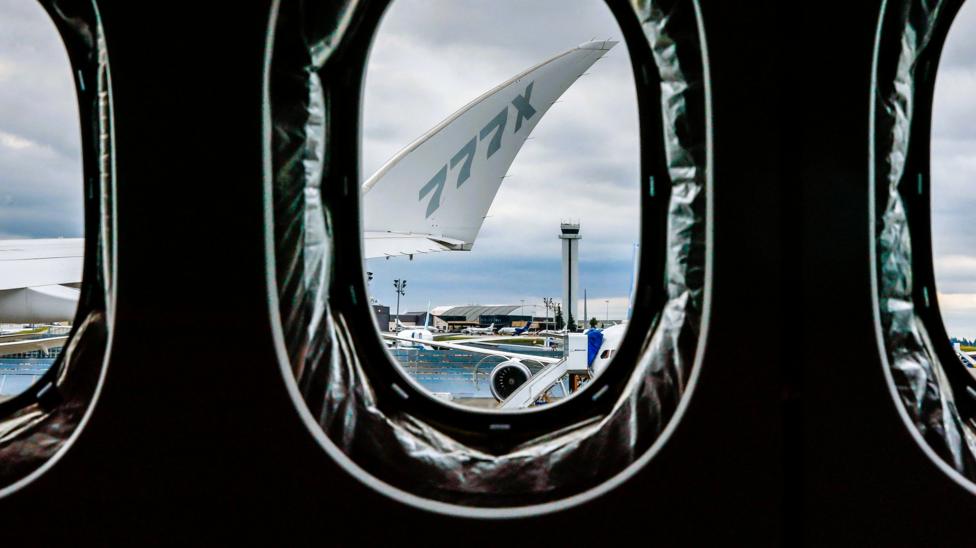
Major aerospace manufacturers across the global aviation sector are confronting severe engineering bottlenecks as next-generation passenger aircraft demand larger, stronger, and more resilient cabin windows. Advanced structural requirements and extreme thermal tolerances have concentrated production within a tiny handful of certified specialized suppliers, creating critical supply chain pressures as airline fleet modernization programs accelerate worldwide.
The Physics of High-Altitude Structural Pressurization
Commercial aircraft cruising at altitudes above thirty thousand feet require cabin pressure environments that subject the fuselage to continuous expansion and contraction cycles. Every window cutout represents an inherent structural vulnerability in the airframe that must withstand multi-directional stress loads. Engineers must balance structural integrity with optical clarity, ensuring materials do not warp, crack, or craze over decades of continuous operational flight cycles.
Modern cabin assemblies rely on multi-pane architecture where the outer pane bears the primary pressure differential while the inner pane serves as a fail-safe backup. Between these layers, tiny breather holes regulate moisture and pressure gradients, preventing condensation and frost formation in sub-zero atmospheric conditions. Fabricating these curved assemblies requires microscopic precision to prevent optical distortion across broad passenger view angles.
Advanced Materials and Specialized Manufacturing Barriers
The transition away from traditional glass toward oriented stretched acrylics has fundamentally reshaped aerospace manufacturing pipelines over recent decades. Stretched acrylic provides superior impact resistance against bird strikes and debris while shedding critical weight compared to inorganic glass formulations. However, the multi-axis stretching process requires proprietary chemical formulations and tightly controlled cleanroom environments that few industrial facilities can maintain.
Only a limited cohort of specialized chemical and transparency fabricators possess the certified autoclave equipment necessary to cure high-grade aerospace polymers. These specialized manufacturers must continually invest millions into capital equipment to meet rigid dimensional tolerances. Consequently, the industrial barrier to entry remains exceptionally high, leaving airframe assemblers vulnerable to localized supply disruptions and material shortages.
Regulatory Certification and Rigorous Safety Mandates
Aviation regulatory authorities enforce exhaustive certification protocols before any window design enters commercial service. Regulatory filings mandate rigorous ballistic testing, rapid decompression simulations, and prolonged chemical exposure trials to guarantee window resilience against aggressive de-icing fluids and hydraulic compounds. These exhaustive validation workflows can take years to achieve full compliance across international aviation frameworks.
Quality assurance programs must audit every production batch for minute chemical impurities or microscopic voids that could propagate into catastrophic cracks during structural flexing. High-resolution optical sensors and ultrasonic inspection tools evaluate every finished unit before delivery. This meticulous level of screening inevitably reduces overall production yields, compounding lead times for airframe assembly plants struggling to meet delivery schedules.
Design Demands of Next-Generation Composite Fuselages
The widespread adoption of carbon-fiber-reinforced polymer fuselages has heightened engineering complexity for transparency suppliers. Composite structures permit higher cabin humidity and lower equivalent cabin altitudes, which significantly improves passenger comfort during long-haul flights. However, the differing thermal expansion rates between carbon fiber airframes and acrylic window panes require sophisticated flexible sealants to prevent structural fatigue.
Airlines increasingly demand larger window dimensions to enhance cabin aesthetics and deliver competitive passenger experiences on flagship international routes. Expanding the surface area increases structural loads exponentially, forcing suppliers to engineer thicker, chemically strengthened laminates that preserve weight savings. The integration of electronically dimmable electrochromic layers adds further electrical layers that complicate the overall fabrication process.
Economic Implications and Industry Supply Outlook
As commercial carriers order record numbers of fuel-efficient passenger jets to replace aging fleets, supplier backlogs continue to expand across tier-one aerospace networks. Analysts indicate that transparency manufacturing has become a critical gating factor for final aircraft delivery rates, alongside engine assemblies and landing gear. Any disruption within this niche material ecosystem cascades directly into commercial airline fleet deployment strategies.
Aerospace manufacturers are currently pursuing strategic investments to automate transparency inspection lines and expand certified cleanroom capacity across North America and Europe. Engineering teams are also researching advanced ceramic coatings and hybrid resin matrices to extend the operating lifespan of installed units. Building supply resilience will remain paramount as commercial aviation pushes toward more durable, efficient aircraft architectures.
