
Understanding Travel Insurance Essentials
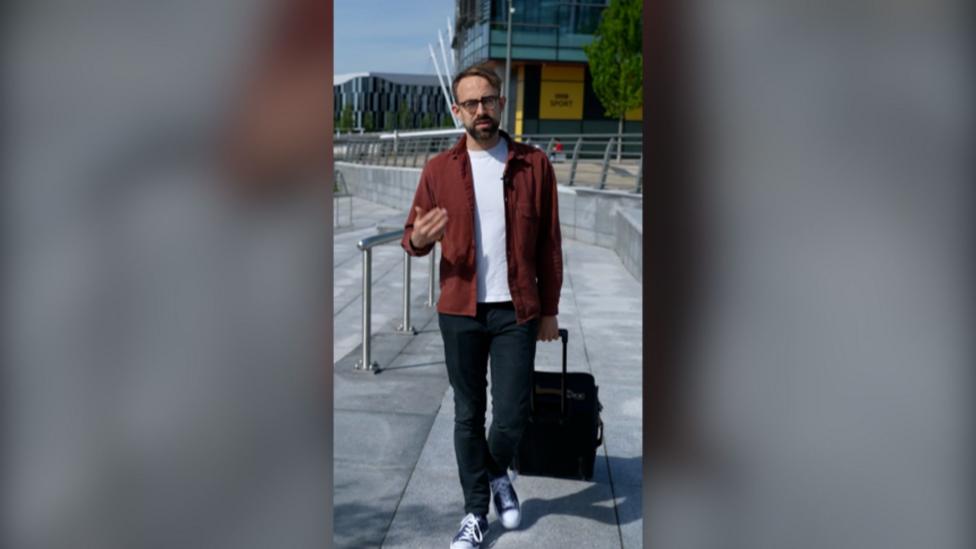
Consumer expert Harry Kind has released a comprehensive guide on purchasing travel insurance, addressing common pitfalls and key decision points. The guide comes as travel demand surges, with more Americans planning international trips this year. Industry analysts note that many travelers still overlook critical policy details. This report breaks down the essential factors every buyer should evaluate before purchasing coverage.
Travel insurance is not a one-size-fits-all product. Policies vary widely in coverage limits, exclusions, and costs. According to state insurance documents, the average traveler spends between $100 and $300 per trip on premiums. However, inadequate coverage can lead to significant out-of-pocket expenses in emergencies. Understanding the fine print is crucial for making an informed purchase.
Coverage Limits and Policy Maximums
One of the first things to examine is the policy's coverage limits, particularly for medical expenses and emergency evacuation. Many standard plans cap medical coverage at $50,000, which may be insufficient for treatment abroad. Experts recommend considering higher limits, especially for destinations with expensive healthcare systems. Always verify whether the policy covers pre-existing conditions, as many exclude them.
Emergency evacuation coverage is another critical component. Medical transport can cost tens of thousands of dollars, and not all policies include this benefit. Travelers heading to remote or high-risk areas should prioritize plans with robust evacuation clauses. Industry analysts suggest comparing at least three policies to identify the best value for individual needs.
Exclusions and Fine Print Details
Every travel insurance policy contains exclusions that can void coverage. Common exclusions include adventure sports, alcohol-related incidents, and travel to high-risk countries. Consumer experts advise reading the policy documents thoroughly before purchase. A single overlooked clause could leave travelers financially vulnerable during a crisis.
The fine print also outlines claim procedures and documentation requirements. Some insurers require receipts, police reports, or medical records within specific timelines. Failure to submit proper documentation can result in denied claims. State consumer protection agencies recommend keeping digital copies of all travel-related documents while abroad.
Cost vs. Value Balance
Price is a significant factor, but the cheapest policy is rarely the best value. Low-cost plans often have higher deductibles and lower coverage caps. Conversely, premium plans may include unnecessary benefits for certain travelers. Evaluating trip cost, destination, and personal health needs helps determine the right balance between affordability and protection.
Industry analysts point out that annual multi-trip policies can offer better value for frequent travelers. These plans cover multiple trips within a year, often at a fraction of the cost of individual policies. However, they may impose per-trip duration limits, typically 30 days. Travelers should calculate their total annual travel days to assess suitability.
Policy Purchase Timing and Cancellation Coverage
When you buy travel insurance matters as much as what you buy. Purchasing a policy immediately after booking a trip ensures coverage for pre-departure cancellations. Waiting until later may exclude coverage for events that occur before the policy start date. Experts recommend buying insurance within 14 days of the initial trip deposit.
Trip cancellation coverage is a primary reason travelers purchase insurance. Policies typically reimburse prepaid, non-refundable expenses if a covered reason forces cancellation. Covered reasons often include illness, injury, or death of the traveler or a family member. Some policies offer 'cancel for any reason' upgrades, though these come with higher premiums and reduced reimbursement percentages.
Destination-Specific Risks and Regional Considerations
Destination risk profiles should heavily influence policy selection. Travelers visiting regions with unstable political climates or limited healthcare infrastructure require specialized coverage. Some policies exclude entire countries or regions based on government travel advisories. Checking the U.S. State Department's advisory levels before purchasing is a prudent step.
Additionally, travelers should consider coverage for natural disasters and weather-related disruptions. Hurricane season, for example, increases the risk of trip interruptions in Caribbean and Gulf destinations. Policies with comprehensive weather disruption coverage offer peace of mind, though they may carry higher premiums. Comparing regional risks against policy benefits is essential for adequate protection.
Consumer expert Harry Kind emphasizes that research is the most valuable tool for buyers. Reading sample policies, understanding state insurance regulations, and consulting independent review platforms can clarify confusing terms. While the process may seem daunting, a methodical approach ensures travelers are not caught off guard by unexpected expenses. Informed buyers consistently secure more suitable coverage.
Looking ahead, the travel insurance market continues to evolve with new products and digital tools. Many insurers now offer real-time claims tracking and mobile-friendly policy management. As travel patterns shift, experts predict increased customization options for niche needs. Staying informed about these developments will help consumers make smarter decisions for future trips.
