
How a New Parent's Pension Decision Changed Their Finances
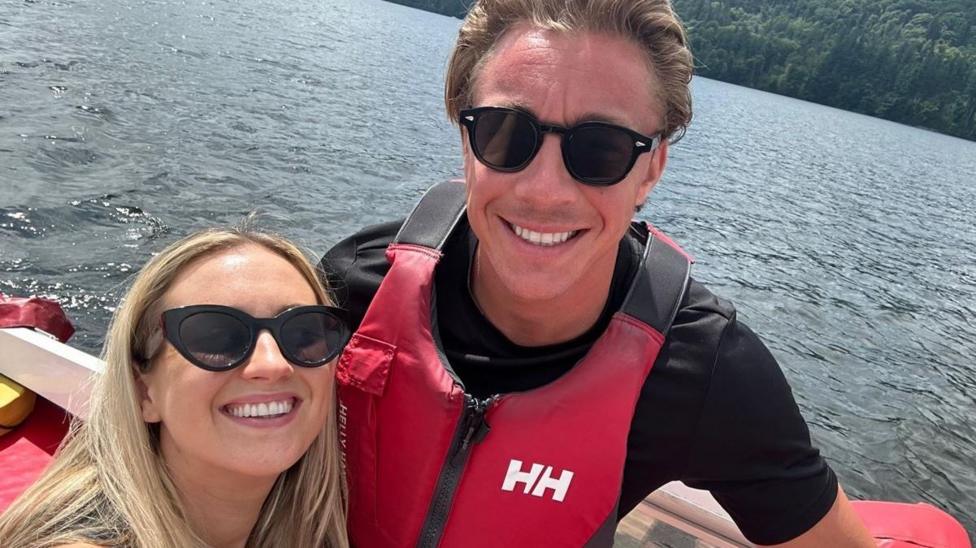
When Molly and Taylor Haylett welcomed their first child, they made a significant change to their financial strategy. Molly asked Taylor to pay into her pension, a move that many couples overlook. This decision, rooted in long-term security, highlights how family milestones can reshape retirement planning. The Hayletts' story offers a practical blueprint for other parents navigating similar financial crossroads.
The couple, who spoke with reporters, explained that the shift came after evaluating their income and childcare costs. Molly, who took extended maternity leave, saw her earnings drop, while Taylor's remained steady. By redirecting some of Taylor's pension contributions to Molly's plan, they balanced their retirement savings. This approach, financial advisors say, can help close the pension gap that often widens during caregiving years.
Why Couples Should Revisit Pension Contributions After a Child
Having a child often triggers a reassessment of household budgets, but pensions frequently take a backseat. The Hayletts' decision underscores the importance of viewing pension contributions as a shared family asset. When one partner reduces work hours or leaves the workforce, their pension accrual slows, potentially affecting their retirement income. Redirecting contributions can mitigate this impact, ensuring both partners maintain adequate savings.
Financial planners note that the pension gap between men and women is often exacerbated by childcare responsibilities. Women are more likely to take career breaks, leading to lower lifetime pension savings. By making spousal contributions, couples can address this imbalance. In the UK, pension rules allow individuals to contribute to a partner's pension, subject to annual allowance limits, making this a viable strategy for many families.
The Mechanics of Spousal Pension Contributions
Spousal pension contributions work by one partner paying into the other's pension fund, either directly or through a salary sacrifice arrangement. The contributing partner receives tax relief at their marginal rate, provided the total contributions do not exceed the annual allowance. For the Hayletts, this meant Taylor's payments into Molly's pension reduced their overall tax liability while boosting Molly's retirement pot.
Experts advise couples to check the pension provider's rules, as some schemes only accept contributions from the account holder. In such cases, a separate arrangement or a new personal pension may be necessary. Additionally, couples should consider the lifetime allowance, which currently stands at £1,073,100 in the UK, to avoid unexpected tax charges. Professional guidance can help navigate these complexities.
Balancing Short-Term Costs and Long-Term Gains
One reason many couples delay such changes is the immediate financial strain of childcare. The Hayletts, however, prioritized long-term security over short-term comfort. They allocated a portion of Taylor's income to Molly's pension, viewing it as an investment in their collective future. This trade-off, while challenging, can yield significant benefits over time, especially given the power of compound interest.
Molly emphasized that the decision wasn't about immediate savings but about ensuring they both had adequate retirement income. She noted that many mothers she knew regretted not addressing pension gaps earlier. By acting proactively, the Hayletts avoided the need for catch-up contributions later, which can be more difficult due to annual allowance limits. Their story serves as a reminder that financial planning should evolve with life changes.
Expert Insights on Pension Planning for Families
Industry analysts highlight that pension contributions should be part of any family financial review. They recommend couples assess their respective pension pots, projected retirement ages, and income needs. Tools like pension calculators can help model different scenarios. The Hayletts' approach aligns with broader advice that emphasizes equalizing retirement savings, particularly when one partner takes on caregiving roles.
Legal and regulatory considerations also play a role. In the UK, the government offers tax relief on pension contributions up to 100% of annual earnings, capped at £60,000. For non-earning spouses, contributions up to £3,600 gross can be made without earnings, making it easier for stay-at-home parents to build pensions. Understanding these rules is crucial for couples looking to optimize their savings.
How to Start the Conversation About Pensions as a Couple
For couples considering similar changes, financial experts suggest starting with a transparent discussion about retirement goals and current savings. Reviewing pension statements together can reveal gaps and opportunities. The Hayletts recommend that couples explore employer matching schemes, as many employers contribute additional amounts to pensions, which can amplify the benefits of any extra contributions.
It's also important to revisit pension plans annually or after major life events, such as a new job, a pay raise, or the birth of another child. The Hayletts plan to review their strategy each year, adjusting contributions as their income changes. This proactive approach ensures their pension planning remains aligned with their family's evolving needs, setting a strong example for other parents.
Ultimately, the Hayletts' story illustrates that pension decisions are not just about retirement—they're about family security. By making a deliberate choice to support each other's savings, they've strengthened their financial foundation. For other couples, the lesson is clear: don't wait for a financial advisor to suggest it; take the initiative to discuss pensions early and often.
Future Outlook: Normalizing Pension Contributions for Parents
As more families share caregiving responsibilities, experts expect spousal pension contributions to become more common. The Hayletts' openness about their finances may encourage others to follow suit. With rising awareness of the pension gender gap, policy makers and employers are also exploring ways to support parents' retirement savings. This trend could lead to more family-friendly pension policies in the coming years.
In the meantime, couples can take actionable steps today. From consulting a financial planner to using online resources, the tools are accessible. The Hayletts' journey proves that even small, deliberate changes can have a lasting impact. By prioritizing their collective financial health, they've not only secured their own retirement but also set a precedent for their child's understanding of money management.
