
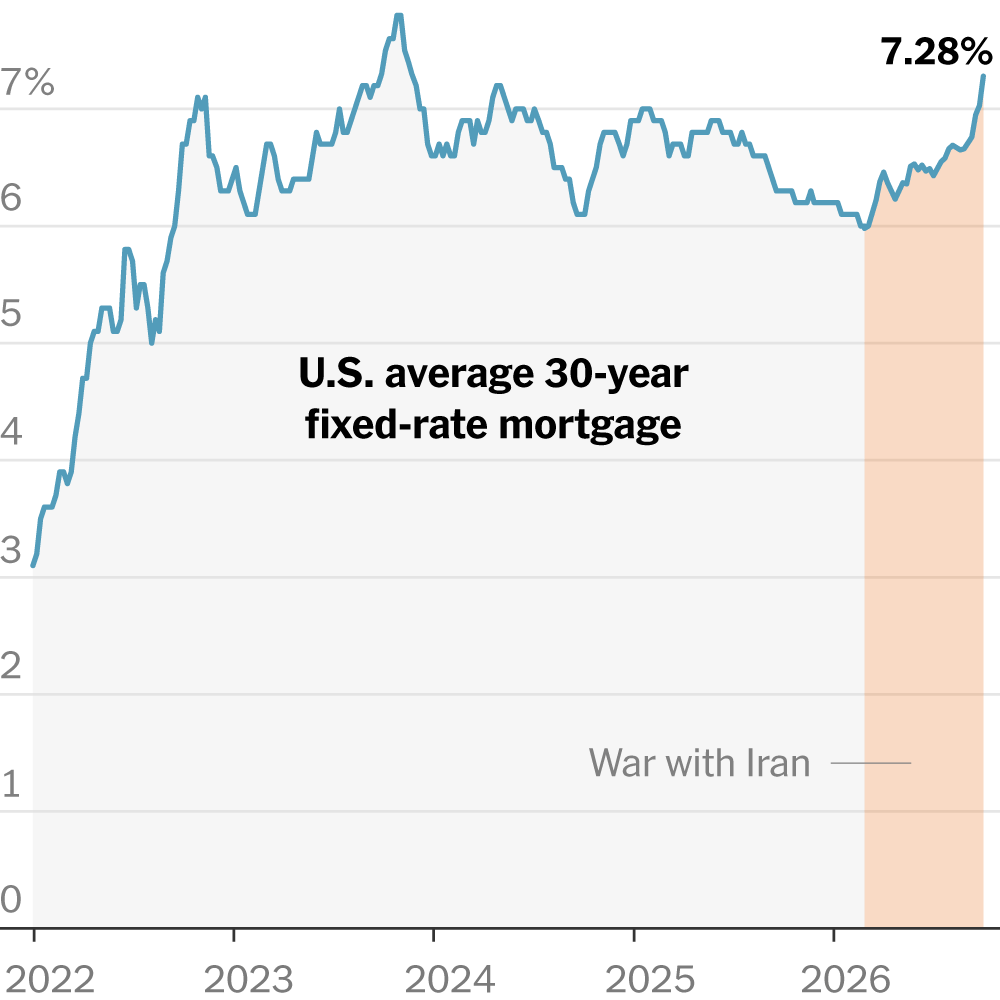
The average 30-year fixed-rate mortgage climbed to 7.28 percent this week, marking the highest level since late 2023 and up sharply from 6.34 percent a year ago, according to official lending data. Rising borrowing costs are reshaping the housing market, with a growing share of buyers now opting for adjustable-rate mortgages (ARMs) to secure lower initial payments. The shift reflects mounting affordability pressures across the country.
Why Mortgage Rates Keep Climbing
Lenders attribute the sustained increase to persistent inflation and stronger-than-expected economic data, which have pushed long-term bond yields higher. The 30-year fixed rate closely tracks the yield on 10-year Treasury notes, and recent Treasury auctions signaled investor expectations of prolonged higher rates. Industry analysts say the Federal Reserve's cautious stance on cutting its benchmark rate has also kept upward pressure on mortgage costs.
A year ago, the average rate stood at 6.34 percent, meaning today's borrowers face roughly $190 more in monthly principal and interest on a $400,000 loan. For a median-priced home, that difference translates into thousands of dollars in additional annual costs. The rapid escalation has startled prospective buyers who had hoped rates would ease in 2025, according to state housing records.
Homebuyers Turn to Adjustable-Rate Mortgages
Applications for ARMs have surged to their highest share of total mortgage demand in over a decade, per industry data. These loans typically offer a fixed rate for an initial period, often five or seven years, before adjusting annually. The starting rate on a 5/1 ARM currently averages about 6.4 percent, nearly a full percentage point below the 30-year fixed product.
Borrowers in high-cost coastal markets are especially drawn to ARMs because the lower initial payment can make a home purchase feasible. However, financial advisors caution that ARM holders face payment shocks when the fixed period ends, especially if rates remain elevated. Lenders are required to disclose maximum possible adjustments, yet many buyers focus primarily on the initial savings.
Affordability Crisis Deepens for First-Time Buyers
The combination of high rates and record home prices has pushed the typical monthly mortgage payment to an all-time high relative to median income. First-time buyers, who lack equity from a previous home sale, are bearing the brunt of the affordability crunch. Real estate records show that the share of purchases financed with ARMs is highest among younger buyers aged 25 to 34.
Many of these buyers are stretching their budgets to enter the market, sometimes with down payments below 10 percent. Lenders report increased demand for mortgage products with lower credit score requirements, though these often carry higher fees. Housing counselors warn that overextended borrowers could face delinquency if rates move higher or home values stagnate.
Regulators and Lenders Respond to Market Shift
Federal banking regulators have issued updated guidance reminding lenders to verify ARM borrowers' ability to repay at the fully indexed rate, not just the introductory payment. This rule, established after the 2008 housing crisis, aims to prevent a repeat of widespread defaults. Several large banks have tightened underwriting standards for ARM products in recent weeks, according to regulatory filings.
The Mortgage Bankers Association projects that ARM volume will remain elevated through 2025, potentially reaching 15 percent of all originations. That would represent a significant structural shift from the past decade, when fixed-rate loans dominated. Industry analysts note that ARMs now carry stricter consumer protections than in prior cycles, including caps on annual and lifetime rate increases.
Economic Impact and Housing Supply Challenges
Elevated mortgage rates are also suppressing housing supply, as existing homeowners with low-rate loans are reluctant to sell and give up their favorable financing. The inventory of existing homes for sale remains near historic lows, keeping prices high despite reduced buyer demand. New construction starts have slowed in recent months, partly due to higher financing costs for builders.
Economists warn that the housing market may remain sluggish for the rest of the year unless inflation cools substantially. Some forecasters expect the Federal Reserve to begin cutting rates in late 2025, which could slowly ease mortgage costs. However, bond market signals suggest that the path to lower rates is uncertain, leaving buyers and sellers in a holding pattern.
What Homebuyers Should Consider in This Rate Environment
Financial planners recommend that prospective buyers compare the total cost of a fixed-rate loan versus an ARM over their expected time in the home. For those planning to move within five to seven years, an ARM can generate substantial savings. Conversely, buyers expecting to stay longer may prefer the certainty of a fixed payment, even at a higher initial rate.
Experts also advise shopping among multiple lenders, as rate quotes can vary by more than half a percentage point for the same borrower profile. Paying discount points upfront can reduce the rate, though this requires additional cash at closing. Government-backed loans, such as FHA and VA products, may offer more competitive terms for eligible borrowers.
Outlook for Mortgage Rates and the Housing Market
Looking ahead, market participants will closely monitor upcoming inflation reports and Federal Reserve meetings for clues on rate direction. If inflation proves stubborn, mortgage rates could test the 8 percent threshold seen in late 2023. Conversely, a cooling economy might bring rates back toward 6.5 percent by year-end, according to industry projections.
For now, the housing market is adjusting to a new normal of higher borrowing costs, with ARMs playing a more prominent role. Buyers are becoming more flexible, often considering smaller homes, different neighborhoods, or new construction incentives. Sellers, meanwhile, are increasingly offering rate buydowns to attract offers, a trend noted in recent brokerage reports.
The coming months will be critical in determining whether the current rate surge is a temporary spike or a sustained trend. Homebuilders are pivoting to smaller, more affordable floor plans, and some states are exploring property tax relief measures. As the market recalibrates, both buyers and sellers will need to adapt to a landscape defined by higher costs and greater financial scrutiny.
