
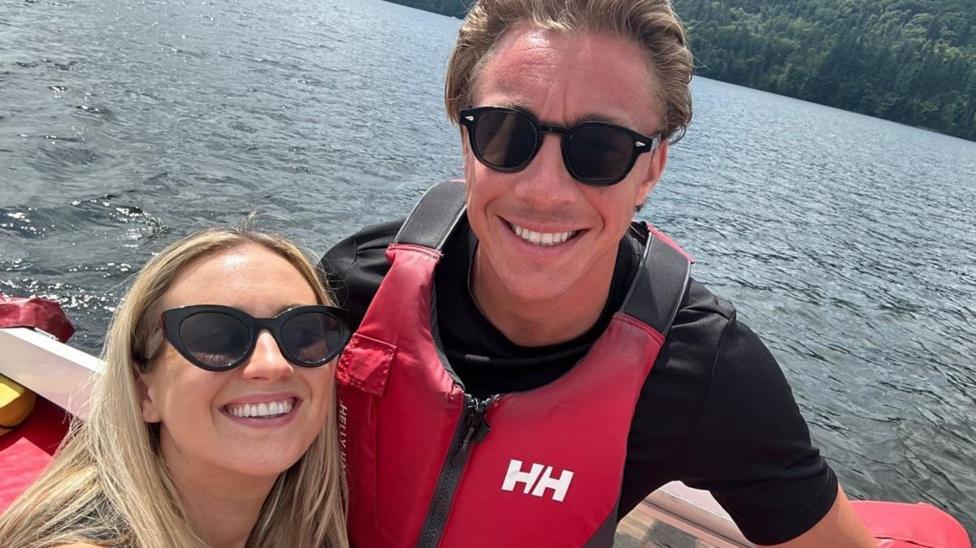
A Personal Finance Decision Rooted in Future Security
When Molly Haylett and her husband Taylor welcomed their first child, the couple faced a pivotal financial crossroads. Molly, who had always managed her own retirement savings, made a deliberate request: that Taylor start paying into her pension. This decision, she explains, was not about immediate income but about protecting their family's long-term financial health against the hidden costs of parenthood.
The Hayletts, like many new parents, quickly realized that starting a family reshapes household budgets in unexpected ways. From reduced earnings during maternity leave to the soaring expense of childcare, the financial strain is immediate. However, Molly's focus was on a less visible threat: the compounding loss of retirement savings during years when contributions often pause or shrink.
The Hidden Penalty of Career Breaks on Retirement Funds
Official records from pension regulators consistently highlight a troubling trend: women often retire with significantly smaller pension pots than men, largely due to career interruptions for caregiving. A single year out of the workforce can reduce eventual retirement income by a measurable percentage, a gap that widens with each additional year of reduced contributions.
Molly explains that her request was a proactive countermeasure. By having Taylor contribute to her pension, the couple aimed to keep her retirement savings growing even while her personal income dipped. This strategy, she notes, treats their household finances as a single unit, rather than separate accounts, ensuring that the financial burden of childcare doesn't fall disproportionately on her future.
How the Couple Restructured Their Household Budget
The Hayletts' approach involved a transparent review of their combined income and expenses. They calculated the total cost of their new childcare arrangements and then adjusted their monthly transfers accordingly. Taylor's contribution to Molly's pension was set to mirror a percentage of her previous salary, effectively simulating her continued earning while she was on reduced hours.
This arrangement required open communication and a shared commitment to their long-term goals. Molly emphasizes that the conversation wasn't about control or mistrust, but about pragmatic planning. By making the pension payment a fixed line item in their budget, they removed the guesswork and ensured the contribution happened automatically each month.
Tax Relief and Government Incentives Explained
Industry analysts point out that such spousal contributions can also unlock valuable tax relief. In many jurisdictions, pension contributions are made from pre-tax income, meaning the couple could reduce their overall tax liability while boosting Molly's retirement fund. This dual benefit makes the strategy particularly attractive for higher-earning households.
Additionally, the couple explored whether they qualified for any government top-ups or childcare vouchers that could offset their costs. While these schemes vary by location, the Hayletts found that even a modest tax break, when redirected into the pension, could compound into a significant sum over the course of a decade.
The Broader Impact on Family Financial Equality
Molly's decision highlights a growing conversation about financial equality within marriages. Traditional models often leave the primary caregiver, typically the mother, with a diminished retirement outlook. By actively rebalancing contributions, couples like the Hayletts are challenging this norm and building a more equitable financial foundation.
Financial planners interviewed for this story note that this approach requires a shift in mindset. It asks couples to view their pensions as a joint asset, not individual ones. This perspective can be difficult, especially for those who value financial independence, but Molly argues it's a necessary evolution when children enter the picture.
Practical Steps for Parents Considering a Similar Move
For other parents, Molly recommends starting with a simple calculation: review your last three months of expenses and project your childcare costs. Then, determine the gap between your current pension contributions and what you were saving before children. That gap is the target amount for a spousal contribution.
She also advises scheduling a formal review every six months. As childcare costs drop when children start school, or as salaries rise, the contribution amounts can be adjusted. This keeps the strategy aligned with the family's evolving financial reality, preventing it from becoming either a strain or an afterthought.
Long-Term Outlook and Lessons Learned
Looking ahead, the Hayletts are confident that their early planning will pay off. While they acknowledge the sacrifice of having less disposable income now, they view it as an investment in their future independence. Molly notes that the peace of mind from knowing her retirement is on track is worth far more than the temporary pinch.
Their story serves as a practical case study for the broader challenge of balancing family and career. It demonstrates that with deliberate planning, couples can mitigate the financial penalties often associated with parenthood. The key, Molly insists, is to start the conversation early and treat the pension as a shared priority.
Ultimately, the Hayletts' experience underscores a simple but powerful lesson: financial security in retirement is not just about individual earnings, but about how couples allocate their collective resources. By making this strategic choice, they have not only protected Molly's pension but also strengthened their family's overall resilience.
