
Why Parenthood Changed Their Pension Strategy
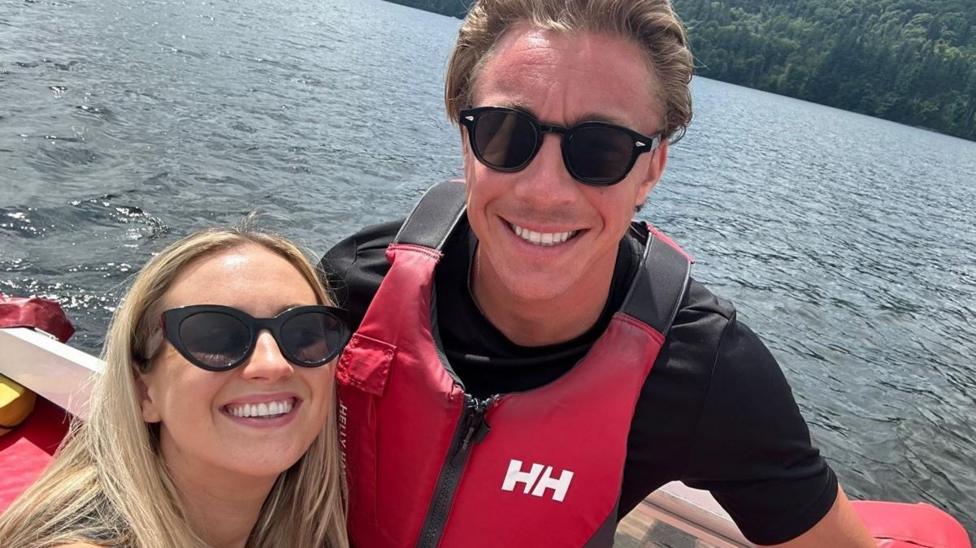
Molly and Taylor Haylett, a married couple from the United Kingdom, made a significant financial adjustment when they welcomed their first child. They decided that Taylor would pay into Molly's pension during her parental leave. This move aimed to offset the loss of her regular income and maintain long-term retirement savings growth.
The Hayletts' decision reflects a growing awareness among young families about the pension gap that often emerges after childbirth. Official records show that women in the UK retire with significantly smaller pension pots than men, largely due to career breaks and reduced hours for childcare. Their proactive approach offers a template for other couples navigating similar transitions.
Understanding the Financial Impact of Parental Leave
When one parent takes time off work, their pension contributions typically stop or drop dramatically. This pause can compound over decades, reducing the final retirement fund by thousands of pounds. Industry analysts note that even a single year of missed contributions can have a measurable effect on long-term growth due to the power of compound interest.
Statutory maternity pay in the UK often falls well below a working salary, making it difficult for new mothers to maintain their previous contribution levels. Many couples overlook this issue entirely, focusing instead on immediate childcare costs. The Hayletts, however, prioritized their future financial security alongside present-day expenses.
How the Hayletts Structured Their Contribution Arrangement
Taylor continued working full-time while Molly took parental leave, and he redirected a portion of his income into her pension account. This arrangement required careful budgeting and clear communication between the couple. They reviewed their monthly expenses and identified areas where they could reduce spending to accommodate the additional retirement contributions.
The couple also took advantage of the UK's pension tax relief system, which allows contributions to be made on behalf of a non-working spouse. This approach provides a tax-efficient way to build retirement savings while one partner is out of the workforce. Financial advisors often recommend this strategy for families with a single income during early childhood years.
Navigating Pension Rules and Employer Policies
Employers in the UK are required to make pension contributions for employees earning above a certain threshold, but this obligation does not extend to workers on unpaid leave. Couples must therefore plan for gaps in employer contributions during extended parental leave. The Hayletts contacted their pension providers directly to understand the specific rules governing voluntary payments.
Some employers offer enhanced parental leave packages that include continued pension contributions, but these policies vary widely across industries. Spokespersons for several major pension providers confirm that individuals can usually make additional contributions to a partner's pension within annual allowance limits. However, these limits change frequently, so couples should seek up-to-date guidance from financial professionals.
The Broader Context of the Gender Pension Gap
The gender pension gap in the UK remains a persistent issue, with women retiring with roughly a third less pension wealth than men on average. This disparity stems from multiple factors, including lower average earnings, career breaks for childcare, and a higher likelihood of working part-time. The Hayletts' approach directly addresses one of the most significant contributors to this gap.
Government initiatives such as automatic enrolment have helped millions of workers start saving for retirement, but they do not fully solve the problem of contribution gaps during parental leave. Policy analysts suggest that more employers should match contributions during maternity and paternity leave to reduce the long-term financial penalty faced by parents.
Practical Steps for Other Families
Experts recommend that couples discuss their pension strategy before the birth of a child, rather than reacting after income changes occur. This planning should include reviewing both partners' pension statements, understanding employer policies, and setting a realistic budget for additional contributions. The Hayletts say that having this conversation early made their transition to parenthood smoother.
Couples should also consider the long-term implications of one partner reducing their working hours. Even a slight reduction in contributions over several years can significantly affect retirement income. Financial planners advise running projections that model different scenarios, including extended leave, part-time work, and childcare costs, to make informed decisions.
Finally, families should review their arrangements annually, especially when salaries change or additional children arrive. The Hayletts plan to reassess their pension strategy after each major life event to ensure their retirement goals remain on track. Their story demonstrates that with careful planning, parents can protect their financial future while raising a family.
