
Federal Reserve Report Exposes Supervisory Blind Spots
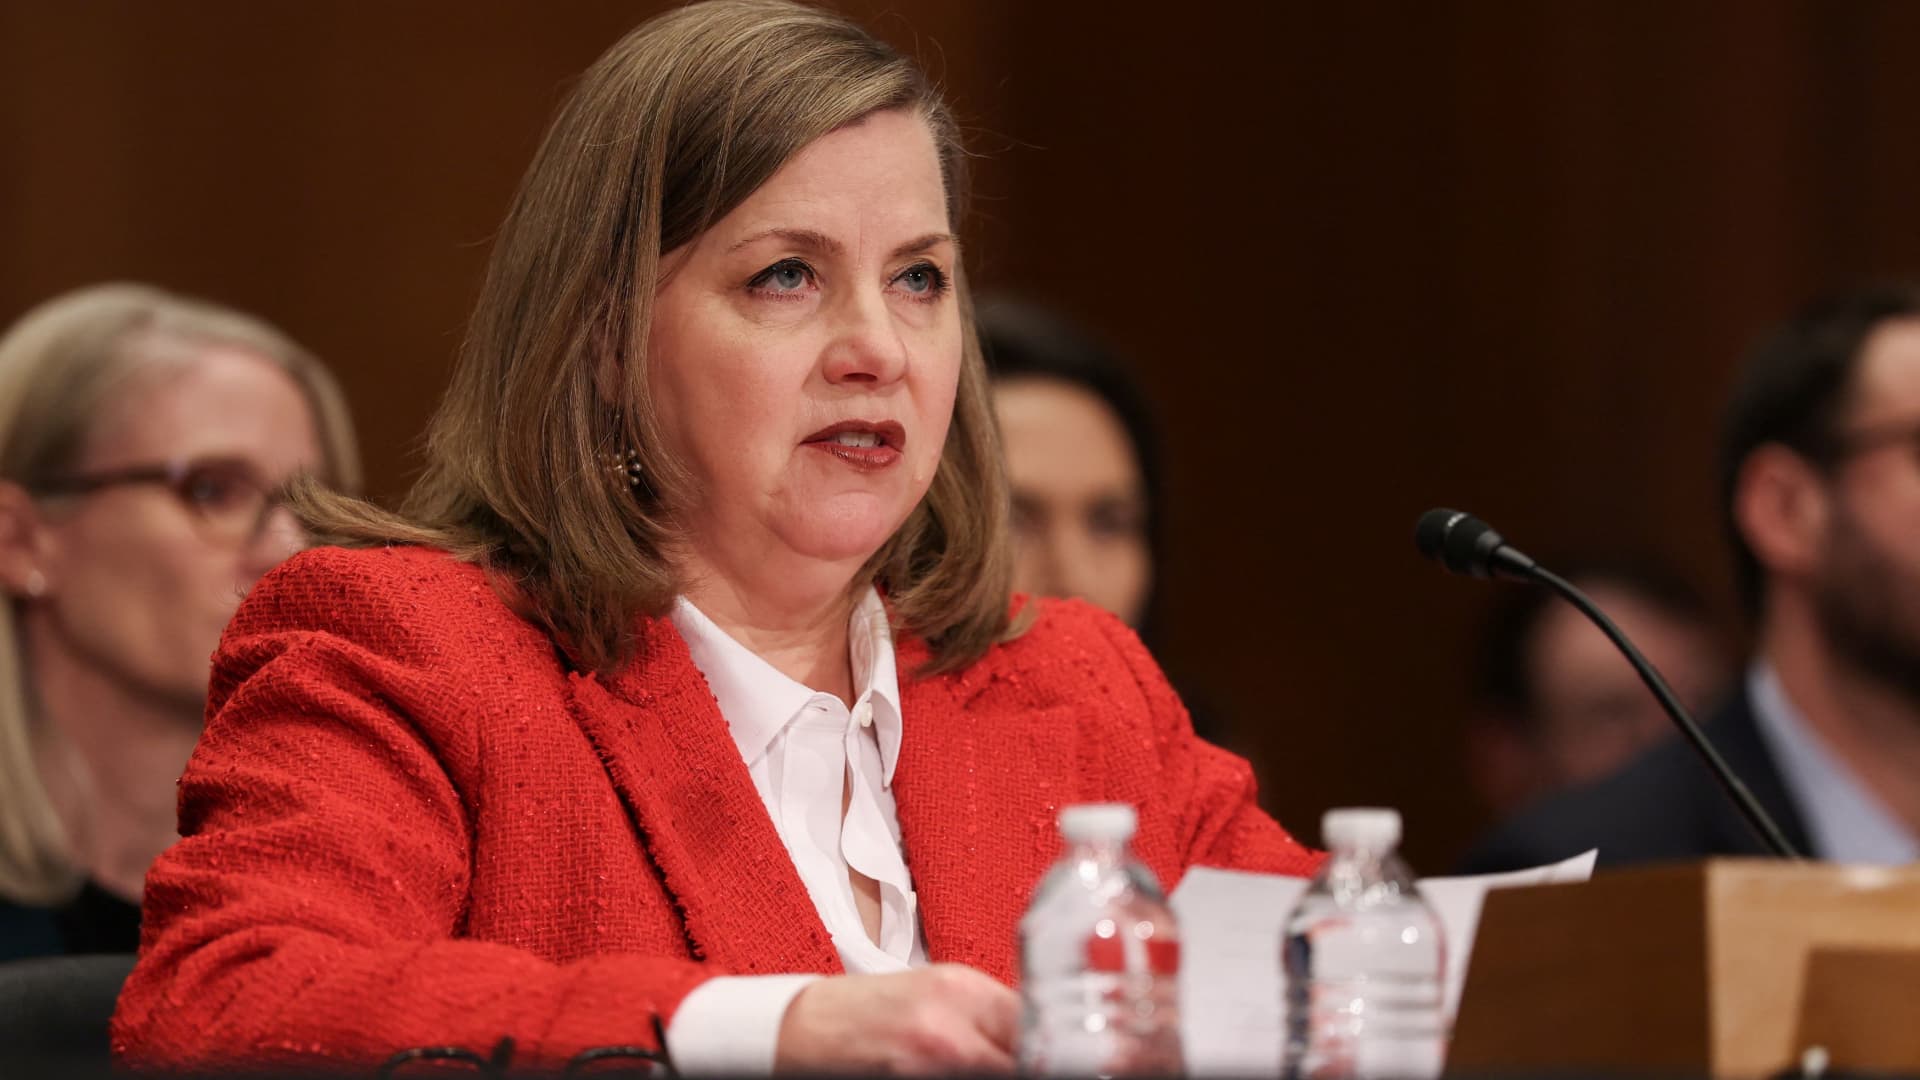
A new internal report from the Federal Reserve reveals that central bank staff failed to recognize mounting vulnerabilities at Silicon Valley Bank before its dramatic collapse in March 2023. Vice Chair for Supervision Michelle Bowman released the findings during a congressional briefing on Tuesday, acknowledging that supervisory teams missed critical red flags that could have triggered earlier intervention.
The report, based on internal reviews and interviews with examiners, points to systemic weaknesses in the Fed's risk assessment framework. Staff reportedly focused on traditional liquidity metrics while underestimating the bank's concentrated deposit base and exposure to rising interest rates. This oversight allowed SVB's balance sheet risks to balloon undetected for months.
How Supervisory Gaps Allowed Risks to Escalate
According to the report, Fed examiners assigned to Silicon Valley Bank relied heavily on outdated stress-test models that failed to account for rapid social media-driven deposit withdrawals. The bank's clientele, primarily venture capital firms and tech startups, held uninsured deposits far exceeding typical thresholds, yet this concentration was not flagged as a material risk.
Internal communications show that junior examiners raised concerns about SVB's bond portfolio losses in late 2022, but these warnings were not escalated to senior leadership. A culture of deference to bank management and a fragmented supervisory structure contributed to the missed signals, the report concludes.
Bowman's Response and Calls for Reform
Vice Chair Bowman, who has led the Fed's supervision division since 2022, called the findings deeply troubling and vowed to implement sweeping changes. She announced the creation of a new risk analytics unit dedicated to detecting emerging threats in real time, along with mandatory training for examiners on interest rate risk and uninsured deposit dynamics.
Bowman also emphasized the need for stronger communication channels between field examiners and Washington policymakers. The report recommends quarterly briefings on high-risk institutions and a centralized dashboard to track vulnerability indicators across the banking sector. Industry analysts note these reforms could face resistance from regional Fed banks accustomed to autonomous oversight.
The Fallout: Economic and Regulatory Repercussions
Silicon Valley Bank's failure triggered a cascading crisis that saw Signature Bank collapse within days and forced the Federal Reserve to launch an emergency lending facility. The FDIC's intervention cost the deposit insurance fund billions, and taxpayers absorbed losses on uninsured deposits through a systemic risk exception.
Small and mid-sized banks across the country faced immediate liquidity pressures as depositors moved funds to larger institutions. The episode also sparked a broader debate about the adequacy of capital requirements for banks with assets between $100 billion and $250 billion, which had been exempted from stricter stress tests under a 2019 regulatory rollback.
Industry Analysts Weigh In on Systemic Vulnerabilities
Industry analysts say the report exposes a fundamental mismatch between the Fed's supervisory tools and modern banking risks. Social media amplification, real-time payment systems, and remote work have transformed how depositors react to news, yet examiners still rely on lagging indicators like quarterly call reports.
The report also highlights the challenge of supervising banks whose business models depend on volatile sectors like technology. Unlike traditional commercial lenders, SVB's growth was tied to venture capital funding cycles, making its deposit base inherently unstable. Analysts argue that specialized examination teams should be deployed for such institutions.
Future Outlook: Will Reform Prevent Another Collapse?
Federal Reserve Chair Jerome Powell has pledged full support for the report's recommendations, with implementation expected over the next 18 months. However, critics note that similar promises followed the 2008 financial crisis, yet regulatory gaps persisted. The challenge lies in balancing robust oversight without stifling community and regional banks.
Bowman's report will now inform pending legislation in Congress, including proposals to raise capital requirements and expand stress-testing mandates. Lawmakers from both parties have expressed support for stricter supervision, though disagreements remain over the scope of new rules. The Fed is also exploring partnerships with fintech firms to develop predictive analytics tools.
For now, the report serves as a sobering reminder that regulatory vigilance must evolve alongside financial innovation. As banking becomes increasingly digital and interconnected, the margin for error narrows. The Fed's response to these findings will likely shape the stability of the U.S. financial system for decades to come.
The full report has been made publicly available on the Federal Reserve's website, and Bowman has committed to annual progress updates. Financial institutions are watching closely, as the new supervisory framework could redefine the relationship between banks and their primary regulator.
