
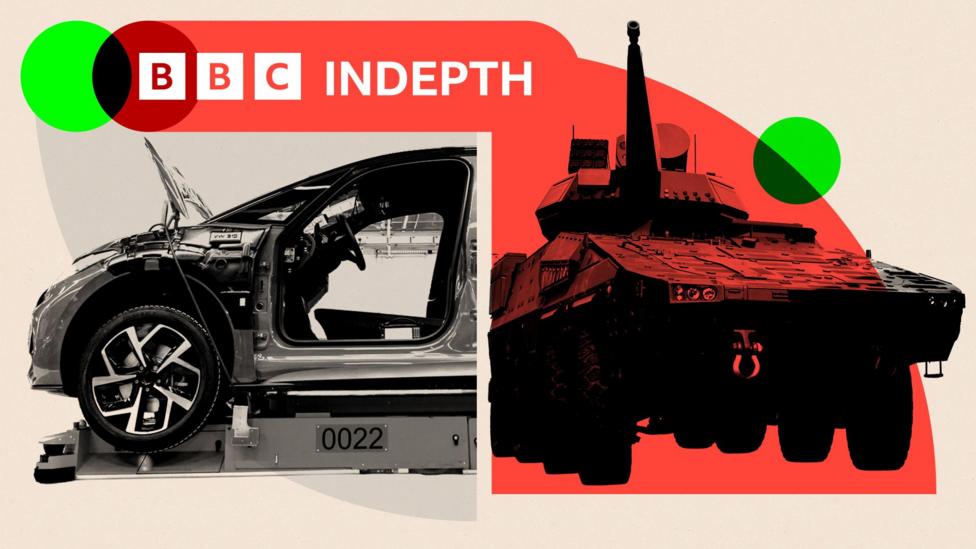
European automotive leaders are facing their most severe industrial downturn in decades, with plant closures and mass layoffs spreading across the continent. As consumer demand for electric vehicles stagnates and Chinese competitors flood the market, executives are now turning to an unexpected savior: the continent's massive rearmament drive. Defense officials and industry analysts confirm that military production lines may offer the only viable path to keep factories operational and preserve Europe's manufacturing expertise.
Why Europe's Car Industry Is in Freefall
The crisis stems from multiple converging factors. Passenger car registrations across the European Union dropped 18% in the first half of this year compared to pre-pandemic levels, according to industry data. European manufacturers have lost significant market share to Chinese electric vehicle producers, who now account for nearly 25% of all EV sales in the region. High energy costs and supply chain disruptions have further eroded profit margins at major plants in Germany, France, and Italy.
Automakers including Volkswagen, Stellantis, and Renault have announced production cuts and workforce reductions affecting over 50,000 employees since early 2024. Union leaders report that nearly 40% of European auto manufacturing capacity now sits idle. The situation has become so dire that some analysts predict the closure of up to 15 assembly plants across the continent within the next three years without intervention.
The Rearmament Pivot: A New Industrial Lifeline
European Union member states have committed to increasing defense spending by 30% annually through 2030, creating unprecedented demand for military vehicles, logistics trucks, and armored platforms. Industry analysts note that automotive factories possess the exact capabilities needed for defense production, including precision manufacturing, advanced materials expertise, and complex supply chain management. Several European automakers have already begun converting civilian production lines to military specifications.
Volkswagen's commercial vehicle division has secured contracts to produce tactical trucks for the German Bundeswehr, while Renault Trucks Defense has partnered with French military authorities for logistics vehicle production. Stellantis has announced plans to repurpose its Italian plants for military drone and armored vehicle components. These contracts represent initial steps toward a broader industrial integration between the automotive and defense sectors.
Government Defense Orders: The Scale of Opportunity
European governments have pledged over €800 billion in combined defense spending through 2030, with a substantial portion allocated to land-based military systems. Defense briefings indicate that European armed forces require more than 200,000 new tactical vehicles to replace aging fleets. This demand could theoretically keep major automotive plants operating at 60% capacity for the next decade, according to industry estimates.
The European Commission has proposed a Strategic Defence Industrial Readiness Act, which would prioritize European-manufactured defense equipment and fast-track procurement processes. Officials suggest this legislation could create a stable pipeline of defense orders for automotive companies, allowing them to maintain workforce levels and invest in next-generation manufacturing technologies. Member states are currently negotiating final provisions of this framework.
Challenges and Risks of the Military Conversion
Converting automotive production to defense manufacturing presents significant technical and financial hurdles. Military vehicles require different engineering standards, including enhanced armor integration, specialized communication systems, and compliance with strict security protocols. Automotive executives acknowledge that retooling costs could reach €50 million per plant, with additional expenses for workforce retraining and certification processes.
Industry analysts caution that defense contracts are typically smaller in volume than commercial automotive production, potentially limiting their impact on employment levels. A single military vehicle order might involve 10,000 units annually compared to 500,000 civilian cars. European automakers must therefore balance defense work with continued civilian production to maintain economies of scale and protect their core business operations.
Public and Economic Impact on Manufacturing Regions
Regions heavily dependent on automotive manufacturing face profound economic consequences from the industry's transformation. Cities like Wolfsburg, Turin, and Stuttgart could see unemployment rates rise above 15% without new industrial opportunities. Local officials have begun lobbying national governments to direct defense contracts toward automotive-heavy areas, arguing that military production offers the most viable path for economic stabilization.
Worker training programs are being developed across Europe to prepare automotive employees for defense sector roles. These initiatives focus on transferable skills such as advanced welding, electrical systems integration, and quality assurance. Union representatives report that early pilot programs have shown promising results, with workers successfully transitioning to military vehicle production within six months of retraining.
Future Outlook: Can Defense Save Europe's Auto Industry?
Industry analysts remain cautiously optimistic that defense production can help stabilize Europe's automotive sector, though they emphasize it cannot fully replace civilian demand. The most successful strategy appears to involve maintaining flexible manufacturing capabilities that can shift between commercial and military production based on market conditions. European automakers that embrace this hybrid approach may emerge stronger from the current crisis.
The long-term viability of this strategy depends on sustained government commitment to European defense industrial capacity. Defense officials have signaled that procurement policies will favor domestic manufacturers, providing automotive companies with predictable revenue streams. As European security concerns continue to rise, the integration of automotive and defense industries appears increasingly likely to become a permanent feature of the continent's manufacturing landscape, potentially reshaping Europe's industrial identity for decades to come.
