
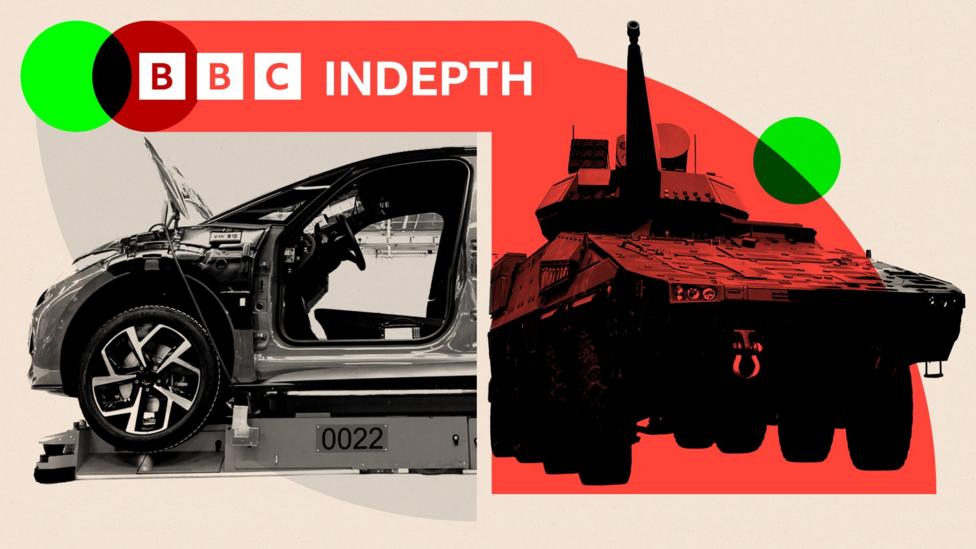
Auto Industry's Deepening Downturn
European automakers are confronting one of the most severe downturns in decades, with sluggish electric vehicle adoption and intense competition from Asian rivals eroding market share. Factory utilization rates have plummeted, and several major manufacturers have announced production cuts and workforce reductions. The crisis has prompted industry leaders to search for new revenue streams that can stabilize operations and preserve manufacturing jobs across the continent.
The region's automotive sector contributes significantly to national economies, particularly in Germany, France, and Italy, where hundreds of thousands of workers depend on the industry. Official records show new car registrations in Europe fell by nearly five percent last year, with electric models underperforming expectations. This trend has intensified pressure on executives to rethink traditional business models and explore alternative industrial applications for their extensive production capabilities.
Defense Spending as a Potential Lifeline
In response to escalating geopolitical tensions in Eastern Europe, the European Union has pledged substantial increases in defense budgets, with member states committing to higher military expenditure over the next several years. This shift has captured the attention of auto executives who see potential for converting existing plants to produce military vehicles, components, and related equipment. Industry analysts suggest this pivot could provide a much-needed buffer against civilian market volatility.
Several automotive groups have already initiated exploratory talks with defense ministries and procurement agencies about potential collaboration opportunities. These discussions focus on leveraging existing engineering expertise and manufacturing infrastructure to support rearmament initiatives. Government officials have signaled openness to such partnerships, recognizing the strategic value of maintaining robust industrial capacity within national borders.
Historical Precedents and Industrial Flexibility
The concept of automakers pivoting to military production is not unprecedented, as many European manufacturers converted their assembly lines during the mid-twentieth century to support wartime efforts. That historical experience demonstrated remarkable adaptability, with civilian factories rapidly transitioning to produce armored vehicles, aircraft parts, and other defense materials. Current executives reference this legacy when advocating for renewed flexibility in production strategies.
Modern manufacturing facilities possess advanced robotics and precision engineering capabilities that align well with defense manufacturing requirements. State documents indicate that several existing automotive plants could be reconfigured with minimal investment to accommodate military contracts. This technical compatibility strengthens the case for deeper integration between the civilian automotive sector and the defense industrial base.
However, industry observers caution that such conversions would require significant time and capital, likely spanning several years before meaningful output could be achieved. Supply chains would also need substantial adaptation, as military components often demand different materials and tolerances than commercial vehicles. Executives emphasize that any pivot would complement rather than replace existing civilian production operations.
Economic Implications and Employment Stability
Proponents argue that defense contracts could help preserve skilled manufacturing jobs that might otherwise face elimination amid declining vehicle demand. Labor unions have expressed conditional support for this approach, provided that employment protections and wage standards remain intact. Regional governments have also shown interest, viewing defense work as a mechanism to maintain economic stability in communities heavily dependent on automotive factories.
Industry analysts estimate that military production could account for up to fifteen percent of total output at some European plants within the next decade, creating a more diversified revenue base. This would reduce vulnerability to cyclical consumer demand and international trade disputes. The potential for increased research and development spending in areas like lightweight materials and autonomous systems also presents attractive opportunities for technological advancement.
Nevertheless, some economists question whether defense contracts can fully compensate for the scale of losses in the civilian market, given the substantial volume differences between commercial and military vehicle production. They point out that annual military vehicle orders represent only a fraction of typical automotive sales volumes, suggesting the financial impact may be limited in the near term.
Regulatory Hurdles and Export Restrictions
Shifting toward defense production introduces complex regulatory challenges, including export control compliance and international arms trade agreements. Companies would need to navigate stringent oversight from national authorities and the European Union, adding administrative layers to existing operations. These requirements may deter some manufacturers from pursuing defense contracts despite the potential financial benefits.
Additionally, reputational considerations could influence corporate decisions, as some stakeholders express concerns about the ethical implications of military production. Several companies have previously faced shareholder pressure regarding defense-related activities, though recent geopolitical developments have softened such opposition. Executives must balance these factors while evaluating long-term strategic options.
Future Outlook and Strategic Priorities
Looking ahead, European automakers are expected to pursue a dual-track strategy that maintains civilian vehicle production while selectively engaging in defense markets. Industry leaders anticipate gradual expansion of military-related activities as procurement frameworks become clearer and funding mechanisms solidify. This approach aims to maximize industrial utilization without abandoning the transition toward electric and autonomous vehicles.
The coming months will likely see formal announcements regarding specific partnerships and production commitments as defense budgets gain final approval. Automotive executives remain cautiously optimistic, viewing rearmament as one component of a broader recovery strategy rather than a complete solution. The industry's ability to adapt will determine whether this emerging opportunity translates into sustainable growth or remains a temporary measure.
For now, the European automotive sector stands at a crossroads, balancing immediate survival needs against long-term transformation goals. The intersection of defense spending and manufacturing capability presents a unique chance to reinforce industrial resilience, though execution challenges remain substantial. Stakeholders across the region will monitor these developments closely as the situation evolves.
