
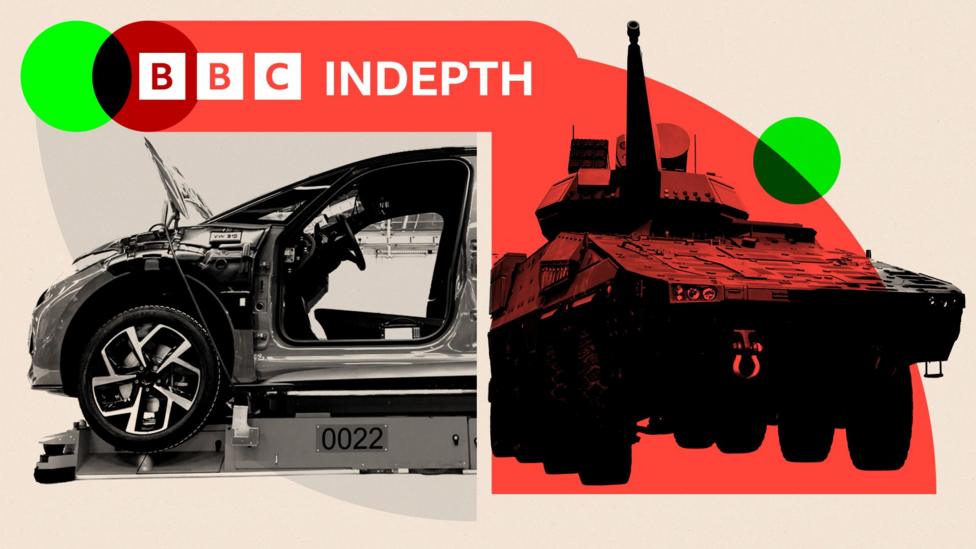
Auto Industry Crisis Deepens Across Europe
European automotive executives are increasingly looking toward defense manufacturing as a strategic lifeline amid a protracted industry downturn. The shift comes as passenger car sales stagnate and electric vehicle demand softens across key markets. Industry analysts say the pivot could reshape the continent's industrial landscape, blending traditional automotive engineering with military production capabilities.
The crisis has been building for months. Official records show new car registrations in major European economies fell by more than six percent in the last quarter compared to the previous year. Supply chain disruptions, elevated energy costs, and cautious consumer spending have compounded the pressure on manufacturers already investing heavily in electrification.
Why Rearmament Spending Is a Potential Lifeline
European governments have signaled a significant increase in defense budgets following heightened geopolitical tensions. This rearmament push, according to defense briefings, could generate hundreds of billions in new procurement contracts over the next decade. Automakers with expertise in precision engineering, logistics, and advanced materials are well-positioned to bid for these opportunities.
Executives argue that producing military vehicles, drones, and communication systems could utilize existing factory capacity without massive retooling costs. The overlap between automotive supply chains and defense manufacturing is substantial, particularly in areas like lightweight composites, electronics, and powertrain systems. Industry analysts note this synergy could provide a buffer against volatile civilian market cycles.
Historical Precedent and Industrial Flexibility
Europe's automotive sector has historically demonstrated adaptability during periods of national emergency. During past conflicts, car plants were swiftly converted to produce aircraft engines, tanks, and field equipment. That legacy of industrial flexibility is now being revisited as executives seek to revive underutilized production lines and protect skilled workforces.
State documents from several European nations indicate a preference for domestic suppliers in defense procurement. This policy stance could favor established automotive giants with deep regional roots. Smaller suppliers within the automotive ecosystem may also benefit through subcontracting arrangements, creating a broader industrial ripple effect beyond just final assembly plants.
Regulatory and Political Hurdles Ahead
Transitioning toward defense work is not without complications. Strict export controls, compliance requirements, and lengthy certification processes could slow the pivot. Additionally, some political factions within Europe remain hesitant about deepening the entanglement of civilian industries with military objectives, citing concerns over corporate accountability and long-term strategic dependencies.
The European Union is currently debating a new defense industrial strategy that aims to streamline procurement and encourage cross-border collaboration. Spokespersons for the bloc have emphasized the need to maintain a robust civilian manufacturing base while selectively integrating defense capabilities. The final framework will likely shape how aggressively automakers can pursue this new revenue stream.
Economic Impact and Workforce Implications
The automotive sector directly employs over two million workers across Europe, with millions more in related supply chains. A successful pivot to defense manufacturing could preserve high-skilled jobs in regions heavily dependent on car production. However, industry analysts caution that defense contracts are often less labor-intensive than civilian vehicle assembly, potentially limiting employment gains.
Regional economies in Germany, France, and Italy are watching these developments closely. Local officials have begun preliminary discussions with automakers about retraining programs and infrastructure investments that could support dual-use production. These conversations indicate that the potential shift is being taken seriously at the highest levels of regional governance.
Future Outlook and Strategic Decisions
Industry analysts suggest that the next twelve months will be critical for determining the trajectory of this pivot. Automakers are expected to announce initial defense-related partnerships and pilot projects within that timeframe. Success will depend on securing long-term contracts, navigating regulatory frameworks, and maintaining civilian product competitiveness simultaneously.
The broader question remains whether rearmament can genuinely rescue the European auto industry or merely provide a temporary buffer. Some experts argue that the structural challenges facing civilian carmakers, including overcapacity and shifting consumer preferences, will persist regardless of defense opportunities. The most resilient companies will likely pursue a balanced portfolio approach.
For now, the mood among executives is cautiously optimistic. The convergence of geopolitical necessity and industrial capability has opened a door that many thought permanently closed. Whether that door leads to sustained profitability or simply a slower decline will depend on execution, political will, and the unpredictable nature of global events in the coming years.
