
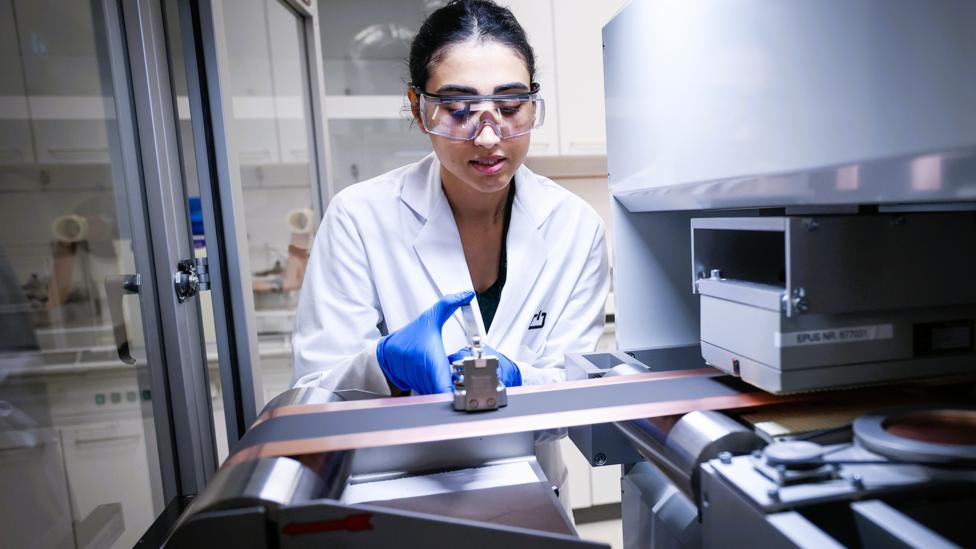
Europe's Battery Ambitions Meet Reality
European officials and manufacturers have long touted the continent's potential to become a global battery powerhouse. Yet recent industry data reveals a stark gap between aspiration and achievement. While European firms develop cutting-edge cell technologies, Chinese producers continue to control roughly 80 percent of global battery manufacturing capacity, leaving European stakeholders to confront hard questions about competitiveness.
The push for battery autonomy stems from broader strategic goals tied to electric vehicle adoption and renewable energy storage. European Union policymakers have allocated billions in subsidies and regulatory support to nurture domestic production. However, industry analysts note that technological innovation alone may not offset the cost advantages and scale that Chinese manufacturers have built over the past decade.
The Scale Advantage of Chinese Producers
Chinese battery giants benefit from massive domestic demand, established supply chains, and significant government backing. These factors enable production costs that European startups struggle to match. Industry reports indicate that Chinese factories operate at roughly 20 to 30 percent lower cost per kilowatt-hour compared to European facilities, a margin that proves decisive in competitive global markets.
Moreover, Chinese firms have secured long-term contracts with major automakers worldwide, locking in revenue streams that fund further expansion. Their vertical integration spans raw material extraction, cathode production, and cell assembly, creating efficiencies that European companies cannot easily replicate. This structural advantage compounds over time, widening the gap despite European innovation.
Promising European Technologies on the Horizon
Despite the daunting competitive landscape, European researchers have developed notable breakthroughs in solid-state batteries, sodium-ion chemistry, and recycling technologies. Several startups have demonstrated prototypes with higher energy density and improved safety profiles compared to conventional lithium-ion cells. These innovations could potentially disrupt existing market dynamics if scaled successfully.
European firms also lead in battery recycling processes, recovering valuable materials like lithium, cobalt, and nickel with high efficiency. Regulatory pressure from the European Union requiring minimum recycled content in new batteries could create a unique market niche. Analysts suggest that this circular economy approach may offer a differentiated path forward for European manufacturers.
Regulatory Support and Strategic Investments
The European Union has responded to the competitive threat with ambitious policy frameworks. The European Battery Alliance, launched in 2017, coordinates public and private investment across member states. Recent regulations mandate carbon footprint declarations and battery passport requirements, which could disadvantage importers relying on coal-powered production methods.
Government subsidies and loan guarantees have supported the construction of several gigafactories across the continent. Countries including Germany, France, and Hungary have attracted major investments from both European startups and Asian manufacturers seeking regional presence. These facilities aim to reduce import dependence and create thousands of skilled jobs in local communities.
Economic and Geopolitical Stakes for Europe
The battery industry carries significant economic weight, with projections suggesting the global market will exceed $400 billion by 2030. For Europe, failure to establish a competitive domestic sector could mean persistent trade deficits and vulnerability to supply disruptions. Automotive manufacturers across the continent depend heavily on reliable battery supplies to transition their vehicle lineups.
Geopolitical considerations amplify the urgency, as energy storage becomes central to national security strategies. European officials recognize that over-reliance on Chinese imports creates leverage risks in diplomatic disputes. This recognition has spurred cross-border collaborations and research partnerships designed to accelerate technological development and production capacity.
Challenges That Remain for European Manufacturers
High energy costs, permitting delays, and skilled labor shortages continue to hamper European battery projects. Construction timelines for gigafactories often exceed initial estimates, while operational costs remain elevated compared to Asian counterparts. These factors have led some companies to delay expansion plans or seek joint ventures with established players.
Access to critical raw materials also presents a persistent challenge, as Europe lacks significant domestic deposits of lithium, cobalt, and nickel. European firms must negotiate supply agreements with countries like Australia, Chile, and the Democratic Republic of Congo, often competing with Chinese buyers for limited resources. This dependency undermines the goal of full supply chain autonomy.
Future Outlook and Potential Turning Points
Industry analysts remain cautiously optimistic about Europe's long-term prospects, citing policy momentum and technological breakthroughs. The shift toward next-generation battery chemistries could level the playing field, as Chinese manufacturers have heavily invested in current lithium-ion technology. European startups focusing on solid-state and sodium-ion systems may capture emerging market segments before Chinese competitors scale similar solutions.
Collaboration between automakers, energy companies, and research institutions has intensified, creating ecosystems that foster innovation. Several pilot projects have demonstrated commercial viability for European-produced batteries in premium vehicle segments, where performance and sustainability credentials justify higher prices. These early successes could provide a foundation for broader market penetration.
Ultimately, Europe's battery industry faces a pivotal decade that will determine its global standing. Success requires sustained investment, regulatory consistency, and strategic partnerships that bridge technological gaps. Whether Europe can translate its innovative capacity into manufacturing scale remains an open question, but the stakes for the continent's economic and energy future could not be higher.
