
Europe's Battery Ambitions Face Reality Check
European leaders have positioned battery manufacturing as a cornerstone of the continent's green industrial strategy, yet recent industry data reveals a widening gap with Chinese competitors. Official records from the European Battery Alliance indicate that Europe currently controls roughly 10 percent of global battery cell production, while China maintains a commanding lead with over 75 percent market share. This disparity raises fundamental questions about whether Europe can achieve its stated goal of energy independence.
The stakes extend far beyond manufacturing jobs. Batteries represent the critical technology for decarbonizing transportation and stabilizing renewable energy grids. Industry analysts note that Europe imported nearly 80 percent of its lithium-ion batteries in 2023, creating strategic vulnerabilities in supply chains. European Commission officials have acknowledged these concerns in recent policy briefings, emphasizing the need for accelerated domestic production capacity.
Promising Innovations Emerge From European Research Labs
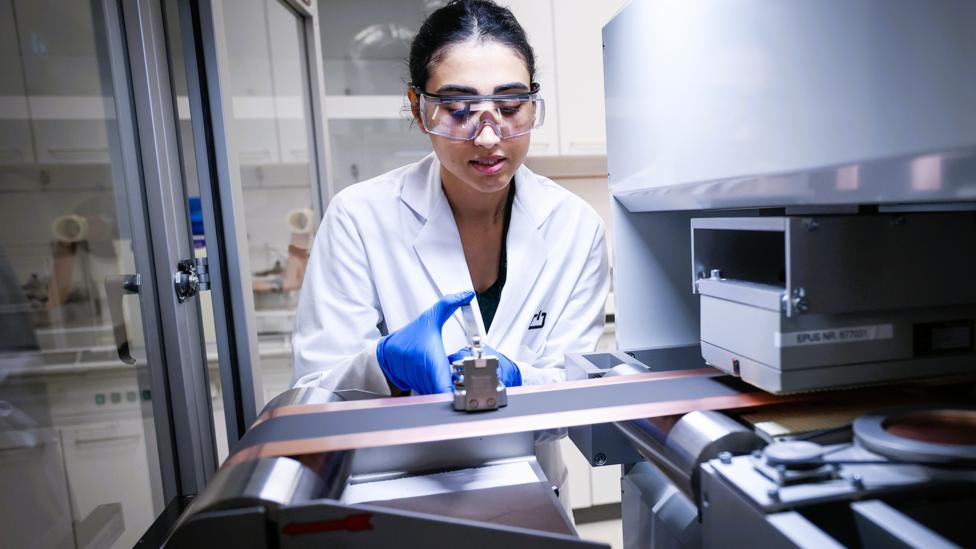
Despite the challenging landscape, European researchers have developed several breakthrough technologies that could shift the competitive balance. State-funded laboratories in Germany and Sweden have made significant progress in solid-state battery designs, which promise higher energy density and improved safety compared to conventional lithium-ion cells. These innovations have attracted substantial private investment from automotive manufacturers seeking to differentiate their electric vehicle offerings.
Swedish startup initiatives have demonstrated particular promise in developing sustainable battery materials that reduce reliance on cobalt and other conflict minerals. Company representatives told industry analysts that their production methods cut carbon emissions by up to 40 percent compared to traditional manufacturing processes. Such environmental advantages could prove decisive as European regulators implement stricter sustainability requirements for battery imports.
Chinese Manufacturers Maintain Scale Advantages
Chinese battery producers have spent the past decade building massive manufacturing ecosystems that benefit from economies of scale and government subsidies. Industry analysts estimate that Chinese factories can produce battery cells at costs 20 to 30 percent lower than their European counterparts. This cost differential has made it difficult for European manufacturers to compete on price, particularly in the mass-market electric vehicle segment.
Beijing's strategic investments in raw material processing have further strengthened China's position. Chinese companies control significant portions of global lithium refining capacity and have secured long-term supply agreements with mining operations across South America and Africa. These vertical integration strategies allow Chinese manufacturers to maintain stable input costs even during periods of commodity price volatility.
Regulatory Framework Aims to Level Playing Field
European Union lawmakers have introduced ambitious regulatory measures designed to foster domestic battery production. The Critical Raw Materials Act establishes targets for domestic processing capacity and encourages member states to streamline permitting processes for new manufacturing facilities. State documents indicate that approved projects under this framework have attracted more than 70 billion euros in planned investments through 2030.
The European Battery Regulation introduces mandatory carbon footprint declarations for all batteries sold in the EU market, creating potential advantages for regional producers with cleaner energy profiles. Industry analysts suggest these requirements could effectively create a green premium that partially offsets the cost disadvantages faced by European manufacturers. However, implementation timelines remain ambitious, and compliance challenges could delay full enforcement.
Automotive Industry Demands Drive Production Targets
European automotive manufacturers have announced aggressive electric vehicle production targets that require substantial battery supply commitments. Official corporate filings show that major German automakers have secured battery supply agreements covering only 60 percent of their projected 2025 requirements. This supply gap presents both a challenge and an opportunity for domestic battery producers seeking long-term purchase agreements.
The transition to electric vehicles has created unprecedented demand for battery manufacturing capacity. Industry analysts project that Europe will need at least 500 gigawatt-hours of annual production capacity by 2030 to support projected electric vehicle sales. Current operational capacity stands at roughly 60 gigawatt-hours, with an additional 120 gigawatt-hours under construction across various member states.
Workforce Development and Infrastructure Constraints
Building a competitive battery industry requires more than capital investment; it demands a skilled workforce and supporting infrastructure. European training programs have begun producing specialized battery engineers and technicians, but industry representatives indicate that current graduation rates fall short of projected needs. The European Battery Academy has launched initiatives to train 800,000 workers by 2025, though funding mechanisms remain uncertain.
Energy costs present another significant competitive challenge for European manufacturers. Electricity prices in major industrial nations remain substantially higher than in China, directly impacting the energy-intensive battery production process. Some member states have proposed industrial electricity rate mechanisms to support large-scale manufacturing operations, but these measures require approval from competition authorities and could face legal challenges.
Future Outlook Depends on Innovation and Collaboration
The trajectory of Europe's battery industry will ultimately depend on its ability to convert research advantages into commercial manufacturing success. Industry analysts emphasize that collaboration between research institutions, manufacturers, and automotive companies will prove essential for scaling innovative technologies. Several cross-border partnerships have already formed, combining German engineering expertise with Scandinavian sustainable manufacturing practices.
International market dynamics could also influence Europe's competitive position in unexpected ways. Trade disputes between major economies may create opportunities for European producers to expand into underserved markets. Additionally, continued technological advancement in battery recycling could reduce raw material dependencies and improve the long-term sustainability of European manufacturing operations.
European policymakers remain publicly optimistic about the continent's ability to close the gap with Chinese producers. Spokespersons for the European Commission have emphasized that battery technology remains a rapidly evolving field where early advantages can quickly become obsolete. They point to Europe's strong research infrastructure and regulatory leadership as fundamental strengths that will support long-term competitiveness.
The coming years will prove decisive for Europe's battery ambitions. Success will require sustained investment, regulatory consistency, and genuine technological breakthroughs that overcome current cost disadvantages. Failure to achieve meaningful progress could leave the continent dependent on foreign suppliers for decades, undermining broader climate goals and economic sovereignty objectives. Industry observers will closely monitor production milestones and market share data throughout 2025.
