
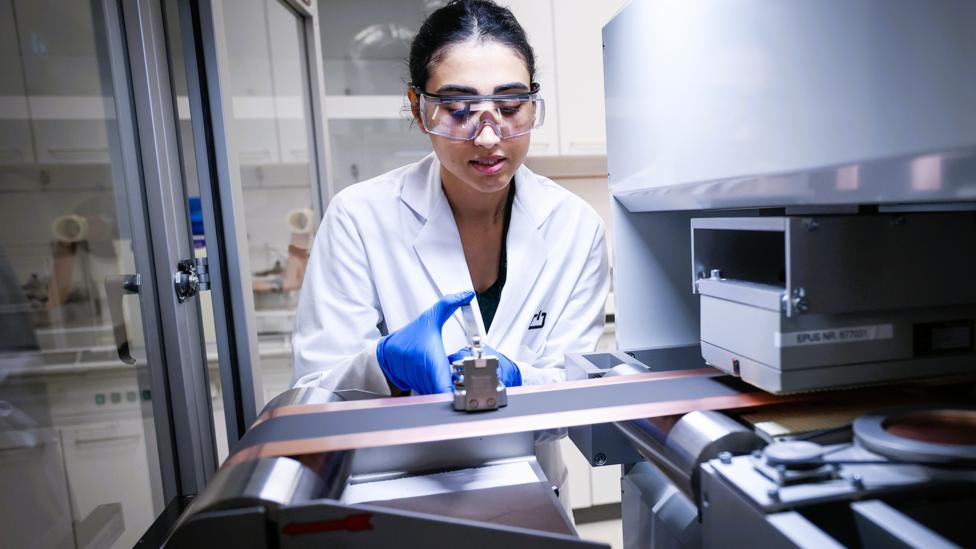
Europe's Battery Ambitions Face Chinese Dominance
European policymakers and industry leaders are racing to build a self-sufficient battery supply chain, but they face a formidable obstacle: China's established manufacturing might. The European Union has set ambitious targets to produce batteries for electric vehicles and energy storage domestically. However, recent data and expert assessments suggest the gap remains wide, with Chinese companies controlling over 70 percent of global battery cell production capacity.
The stakes are high for Europe's automotive sector, which employs millions and is undergoing a rapid transition to electric mobility. Without a competitive domestic battery industry, European carmakers risk depending on imported cells, leaving them vulnerable to supply chain disruptions and price volatility. This strategic vulnerability has prompted Brussels to treat battery production as a matter of industrial sovereignty, not just economic competitiveness.
The Scale of China's Battery Manufacturing Lead
China's dominance in battery production is not accidental. Decades of state-backed industrial policy, massive domestic demand, and aggressive investment in supply chain infrastructure have created an ecosystem that is difficult to replicate. Chinese firms benefit from economies of scale, lower energy costs, and established access to critical raw materials like lithium, cobalt, and nickel, often through long-term contracts or equity stakes in mines worldwide.
Industry analysts point out that China's lead is not just in cell manufacturing but also in upstream processing of battery materials. Refining capacity for key minerals is heavily concentrated in China, giving its companies a cost advantage that European startups cannot easily match. This vertical integration allows Chinese producers to control costs and quality at every stage, from raw material to finished battery pack.
European efforts to catch up are underway, with several gigafactories planned or under construction across the continent. Yet the timeline for reaching scale is measured in years, not months. Analysts estimate that even with aggressive build-out, Europe will meet only a fraction of its projected domestic battery demand by the end of the decade, leaving a significant import dependency.
Promising European Technologies and Niche Strengths
Despite the manufacturing gap, European companies are making notable progress in next-generation battery technologies. Solid-state batteries, which promise higher energy density and improved safety, are a key focus of research and development across the continent. Several European startups and automotive groups have announced pilot production lines and partnerships aimed at commercializing this technology before 2030.
Europe also holds strengths in battery recycling and sustainable production methods. New EU regulations mandate minimum recycled content in batteries and stricter carbon footprint disclosure, creating a regulatory framework that could favor domestic producers. Companies are investing in closed-loop systems that recover valuable materials from spent batteries, reducing reliance on imported raw materials and aligning with the block's circular economy goals.
Additionally, European automakers are leveraging their expertise in vehicle integration and battery management systems. While cell chemistry and manufacturing are key, the way batteries are packaged, cooled, and managed within a vehicle also impacts performance and cost. European engineers are innovating in these areas, potentially offsetting some disadvantages in cell production with superior system-level design.
Policy Response and Investment Push Across the EU
The European Union has responded with a mix of regulatory tools and financial incentives. The European Battery Alliance, launched in 2017, has facilitated cooperation between industry, member states, and the European Investment Bank. Public funding has been approved for multiple transnational projects under Important Projects of Common European Interest (IPCEI), allowing governments to provide state aid that would otherwise be restricted under competition rules.
These efforts are complemented by the EU's Critical Raw Materials Act, which sets benchmarks for domestic extraction, processing, and recycling of key minerals. The legislation aims to reduce dependency on any single third country for strategic raw materials, with a specific focus on diversifying sources and building strategic stockpiles. This regulatory push is designed to create a more resilient and secure supply chain for the entire battery ecosystem.
Member states are also contributing national funds and incentives to attract battery manufacturing. Major projects in Germany, France, and Sweden have received substantial government support, including grants and loan guarantees. These investments are intended to de-risk private capital and accelerate the construction of large-scale production facilities that can compete on cost and quality with established Asian rivals.
Economic and Strategic Impact of Closing the Gap
A competitive European battery industry would have significant economic implications. It could create tens of thousands of direct jobs in manufacturing and hundreds of thousands in the broader supply chain, from engineering to logistics. Beyond employment, it would strengthen Europe's trade balance by reducing imports of high-value components and potentially creating export opportunities in emerging markets.
Strategically, battery independence is linked to broader goals of energy security and climate leadership. The transition to electric vehicles is central to Europe's plan to cut greenhouse gas emissions, and a secure battery supply chain is essential to that transition. Control over battery technology also has geopolitical dimensions, as countries with advanced manufacturing capabilities gain leverage in global trade negotiations and technology standards.
Industry observers note that Europe does not need to beat China in every segment to be successful. Specializing in premium products, sustainable manufacturing, and advanced technologies could carve out a profitable niche. However, achieving even this more modest goal requires sustained investment, regulatory stability, and a skilled workforce, all of which are in development but not yet fully realized.
Future Outlook and Key Challenges Ahead
Looking forward, the trajectory of Europe's battery industry will depend on several critical factors. The pace of technological innovation, particularly in solid-state batteries, could disrupt current market dynamics. If European firms can commercialize this technology first, they could gain a competitive edge that offsets China's scale advantages in conventional lithium-ion cells.
Another challenge is the cost of energy and labor in Europe, which remains higher than in many Asian manufacturing hubs. Producers will need to achieve significant efficiency gains and automation to remain cost-competitive. Additionally, the availability of skilled engineers and technicians is becoming a bottleneck, prompting companies to invest in training programs and academic partnerships.
Despite these obstacles, there is cautious optimism among industry stakeholders. The combination of regulatory support, private investment, and technological expertise provides a foundation for growth. Whether Europe can translate this potential into a globally competitive battery industry will be a defining test of its industrial policy and economic resilience in the coming decade.
