
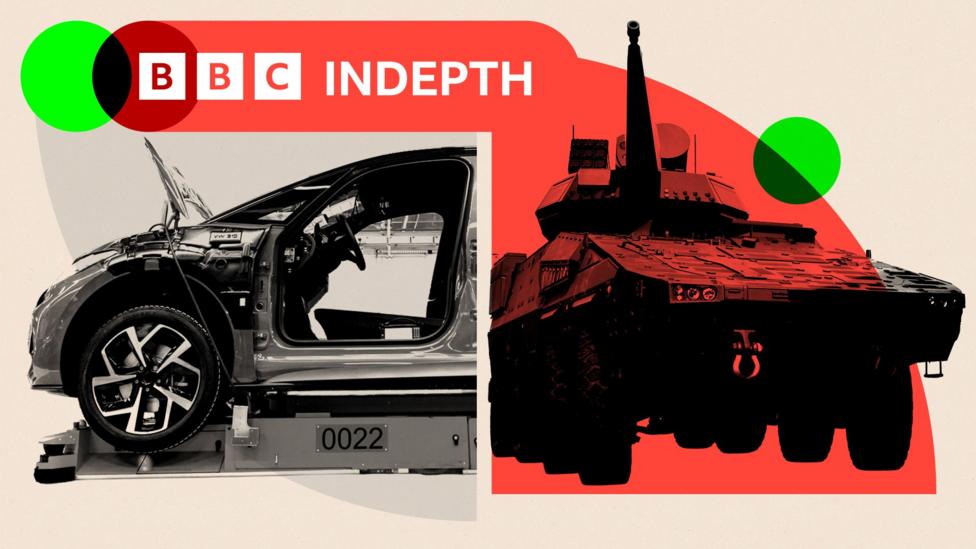
Struggling Sector Sees New Opportunity in Defense
European automakers, battered by weak demand and high costs, are increasingly turning to the continent's defense buildup as a potential lifeline. Industry executives and policymakers see rearmament programs as a way to revive factory output and protect skilled jobs. The shift comes as governments across Europe pledge billions to modernize military capabilities, creating a rare opening for civilian manufacturers to diversify.
The region's car industry has faced a perfect storm of challenges: sluggish electric vehicle adoption, stiff competition from Chinese rivals, and soaring energy prices. Production volumes have fallen sharply since pre-pandemic levels, with several major plants announcing temporary shutdowns. The defense sector, by contrast, is experiencing a surge in demand, driven by geopolitical tensions and renewed commitments to national security.
How Rearmament Spending Could Reshape Auto Plants
Defense contracts typically require precision manufacturing, robust supply chains, and rigorous quality standards, all of which are strengths of established carmakers. Analysts suggest that converting underutilized assembly lines to produce military vehicles, drones, or components could provide steady revenue streams. Several European governments have signaled willingness to prioritize domestic suppliers, further boosting the appeal of such partnerships.
The potential scale of this shift is substantial. Defense ministries across Europe have announced multi-year procurement plans, with budgets rising to record levels. Industry analysts estimate that military vehicle orders alone could reach tens of thousands of units annually, offering a meaningful offset to declining civilian sales. This alignment of industrial capacity with strategic needs has sparked serious discussions within corporate boardrooms and government offices.
Executive Optimism Amid Lingering Uncertainty
Auto executives have expressed cautious optimism about the defense pivot, framing it as a natural extension of their engineering expertise. Some have already secured pilot contracts for military logistics vehicles, while others are exploring joint ventures with established defense firms. However, leaders acknowledge that transitioning from civilian to military production involves significant regulatory hurdles, including export controls and security clearances.
Despite the enthusiasm, industry officials remain wary of over-reliance on defense spending, which can be politically volatile and subject to sudden budget shifts. They emphasize the need for balanced strategies that maintain competitiveness in core automotive markets. The challenge lies in scaling military production without sacrificing innovation in electric vehicles or autonomous driving technologies, where European firms are fighting to regain ground.
Policy Support and Regulatory Hurdles Ahead
European Union policymakers are actively exploring frameworks to facilitate the automotive-defense crossover, including tax incentives and streamlined procurement rules. Officials have highlighted the importance of maintaining a resilient industrial base, particularly in light of supply chain disruptions exposed during recent global crises. Yet, bureaucratic complexities and divergent national priorities may slow implementation, frustrating industry leaders seeking swift action.
Some member states have moved faster than others, with countries like Germany and France leading efforts to integrate civilian manufacturers into their defense supply chains. These nations are also investing in dual-use technologies that serve both military and commercial purposes, such as advanced sensors and lightweight materials. Such approaches could help spread the benefits of rearmament across a wider range of companies and regions.
Economic and Employment Impacts on Local Communities
The potential defense contracts carry significant implications for employment, particularly in regions heavily dependent on auto manufacturing. Thousands of workers face uncertainty as plant closures loom, and rearmament could preserve jobs that might otherwise be lost. Local officials and union representatives have voiced support for the pivot, viewing it as a pragmatic response to a rapidly changing economic landscape.
However, labor leaders also stress the need for retraining programs and wage protections to ensure workers benefit equitably from any transition. The shift to military production may require different skills, raising concerns about job quality and long-term career stability. Balancing these workforce considerations with industrial demands will be a key test for both companies and governments navigating this transformation.
Future Outlook and Strategic Considerations
Looking ahead, the intersection of automotive and defense sectors appears poised for growth, though its ultimate scale remains uncertain. Industry analysts predict that successful integration could take several years, requiring sustained investment and policy alignment. The coming decade will likely see European carmakers increasingly bid for defense work, driven by both economic necessity and strategic opportunity.
For now, the prospect of rearmament offers a glimmer of hope in an otherwise gloomy industrial landscape. Whether this translates into a lasting revival depends on execution, political will, and market conditions. As Europe recalibrates its security posture, its automotive giants may find themselves building more than just cars, potentially reshaping the continent's industrial identity for years to come.
