
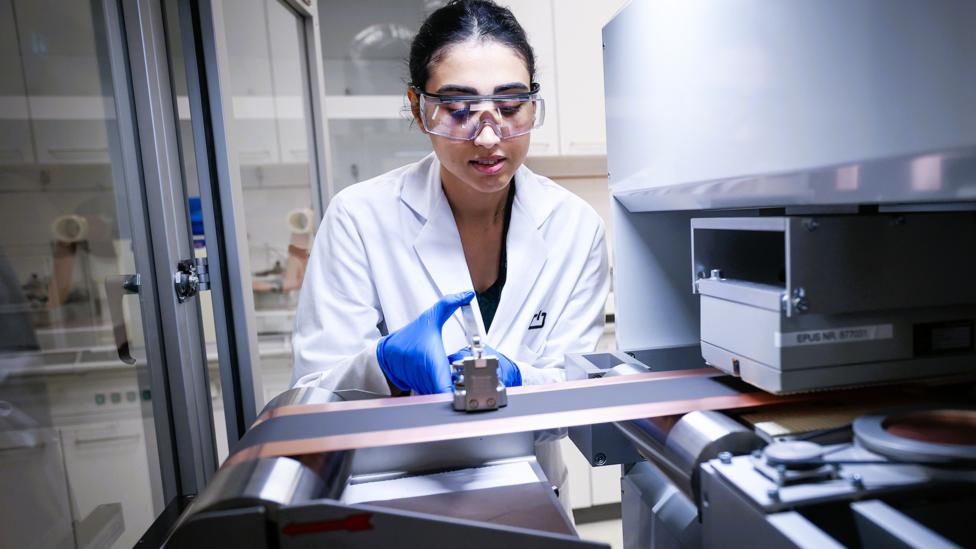
Europe's Battery Ambitions Face a Stark Reality
Europe has made bold promises to build a homegrown battery industry, but its market share remains far behind Asian competitors. Despite billions in subsidies and ambitious gigafactory projects, the continent still relies heavily on imports, particularly from China. Industry analysts suggest that while European technology is innovative, scaling production quickly enough to compete is proving difficult.
The European Union has set aggressive targets for electric vehicle adoption, with a ban on new petrol and diesel cars planned for 2035. This policy push has created urgency to secure battery supplies locally. Yet, as of early 2025, Europe produces only about 7 percent of the world's battery cells, according to official industry data. China commands roughly 77 percent of global manufacturing capacity.
How Did Europe Fall Behind in Battery Manufacturing?
Europe's battery deficit stems from a decade of underinvestment and a lack of coordinated industrial strategy. While Asian firms scaled up production in the 2010s, European automakers relied on imported cells. Government-backed initiatives like the European Battery Alliance launched in 2017 aimed to change course, but implementation has been slower than expected.
Supply chain gaps also hinder progress. Europe lacks sufficient raw material refining capacity for lithium, cobalt, and nickel. Most processing still happens in China, which controls the supply chain from mining to cathode production. European companies are now scrambling to secure partnerships with mining firms in Australia, Chile, and Africa to diversify sources.
Promising European Technologies Could Shift the Balance
Despite production hurdles, Europe holds a competitive edge in next-generation battery chemistry. Solid-state batteries, lithium-sulfur cells, and sodium-ion technology are areas where European research institutes and startups are making notable advances. These innovations could offer higher energy density, lower costs, and safer operation compared to current lithium-ion batteries.
Several European firms have announced breakthroughs in solid-state battery development, with pilot lines expected within two years. Industry analysts note that if these technologies scale successfully, Europe could leapfrog some existing Chinese advantages. However, moving from lab results to mass manufacturing remains a critical challenge that requires significant capital and engineering expertise.
EU Policy Response and Investment Push
The European Commission has responded with a mix of regulatory and financial tools. The Critical Raw Materials Act, passed in 2023, sets targets for domestic extraction and processing of key minerals. The Net-Zero Industry Act streamlines permitting for gigafactories and offers tax incentives for producers. Together, these policies aim to reduce import dependency by 2030.
Public funding has also flowed heavily into the sector. State aid approvals for battery projects have reached billions of euros, supporting companies like Northvolt and ACC (Automotive Cells Company). These firms are building gigafactories in Sweden, Germany, France, and Italy, with combined planned capacity exceeding 500 gigawatt-hours by 2030, according to official filings.
Economic and Geopolitical Stakes for Europe
The battery race carries massive economic weight. The European market for batteries is projected to reach €250 billion annually by 2030, according to industry estimates. Capturing even a third of that value could create hundreds of thousands of jobs and secure Europe's position in the global EV supply chain. Failure would mean continued dependence on foreign suppliers.
Geopolitical tensions add another layer of urgency. Europe aims to reduce vulnerabilities in critical supply chains, especially after the pandemic exposed fragile logistics. Officials have repeatedly stressed that energy storage is a strategic sector, essential for both mobility and grid stability. Diversifying away from Chinese dominance is now seen as a security priority, not just an industrial one.
What Needs to Happen Next for Europe's Battery Sector
Industry experts argue that Europe must accelerate permitting processes and increase funding for recycling infrastructure. Currently, less than 10 percent of lithium-ion batteries in Europe are recycled, creating both environmental and supply chain risks. Expanding domestic recycling capacity could recover valuable materials and reduce reliance on virgin mining.
Collaboration between automakers, battery producers, and research institutes must also deepen. Some European car manufacturers have formed joint ventures with battery startups, but the scale remains small compared to Asian conglomerates. Analysts suggest that more aggressive consolidation and cross-border partnerships could help Europe build the scale required to compete globally.
Workforce development is another pressing need. Battery manufacturing requires specialized skills in electrochemistry, process engineering, and quality control. Several European universities have launched dedicated battery programs, but the pipeline of trained professionals is still thin. Without a strong talent base, even the most modern factories will struggle to operate at full efficiency.
Looking ahead, the next three years will be decisive. If European gigafactories hit production targets and next-gen technologies prove viable, the continent could carve out a meaningful share of the global battery market. If delays persist, Europe may fall further behind, forcing its automakers to continue purchasing cells from Asian suppliers for the foreseeable future.
The path forward is not impossible, but it is steep. Europe has the research base, the policy tools, and the industrial will to build a competitive battery sector. What remains uncertain is execution. Whether the continent can translate ambition into factories and factories into market share will determine the fate of its clean energy transition.
