
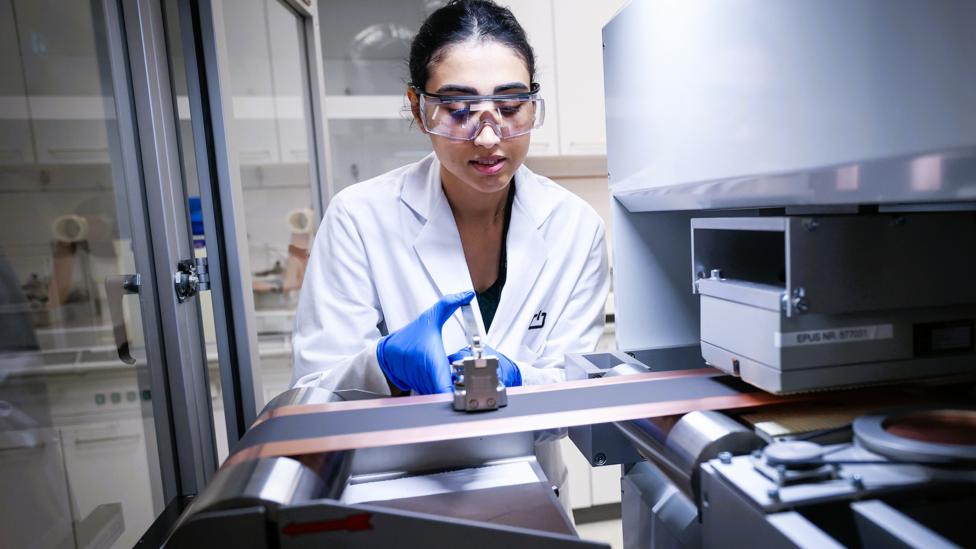
Europe's ambition to build a self-sufficient battery industry faces a steep climb as Chinese manufacturers continue to dominate global production, according to industry analysts. Despite promising breakthroughs in battery technology, European companies lag significantly behind their Asian counterparts in scale, cost efficiency, and supply chain control. The gap raises critical questions about the continent's ability to secure its energy future and compete in the rapidly growing electric vehicle market.
The Scale of the Challenge
China currently controls roughly 80 percent of the global battery cell manufacturing capacity, with companies like CATL and BYD leading the pack. Europe, by contrast, accounts for just over 10 percent of global capacity, despite ambitious targets to capture a larger share by 2030. Analysts note that Chinese firms benefit from decades of government support, massive economies of scale, and a fully integrated supply chain that spans raw materials, processing, and cell assembly.
European startups such as Northvolt and Verkor have made headlines with their plans to build gigafactories, but progress has been slower than projected. Northvolt, for instance, has faced production delays and financial challenges, underscoring the difficulty of challenging entrenched competitors. Industry insiders point out that breaking into the market requires not only technological innovation but also massive capital investment and long-term customer commitments.
Technological Strengths and Weaknesses
Europe does possess notable strengths in battery technology, particularly in the development of solid-state batteries and advanced materials. Several European research institutions and startups are working on next-generation cells that promise higher energy density, faster charging times, and improved safety. However, these innovations remain largely at the laboratory stage, and scaling them to commercial production is a formidable hurdle.
Meanwhile, Chinese manufacturers are not standing still. They are investing heavily in research and development, and some have already begun pilot production of solid-state batteries. This means Europe cannot rely solely on technological superiority to close the gap; it must also match China's speed in commercializing new innovations. Industry analysts warn that without rapid deployment, European breakthroughs could be overtaken by Asian competitors.
Supply Chain Vulnerabilities
A major obstacle for Europe is its dependence on imported raw materials, particularly lithium, cobalt, and nickel. China has secured long-term supply agreements with mines in Africa, Australia, and South America, locking up access to critical minerals. European companies, by contrast, often face higher costs and supply chain uncertainties, which hampers their ability to produce batteries at competitive prices.
Efforts to diversify supply chains are underway, including the European Raw Materials Alliance and initiatives to boost domestic mining and refining capacity. However, these projects face environmental and regulatory hurdles, and analysts estimate it could take a decade or more to reduce dependency significantly. In the short term, European battery makers remain vulnerable to price volatility and geopolitical disruptions.
Policy Support and Investment
The European Union has recognized the strategic importance of the battery industry and has launched several initiatives to support it. The European Battery Alliance, established in 2017, aims to foster a competitive and sustainable battery ecosystem. Additionally, the EU has approved state aid for major projects, including billions of euros in subsidies for gigafactory construction and research programs.
Despite these efforts, experts argue that policy support has been fragmented and insufficient compared to China's coordinated industrial strategy. European regulations on state aid and competition are more restrictive, limiting the scale of subsidies that can be provided. Furthermore, the lack of a unified industrial policy across member states creates inefficiencies and delays, putting Europe at a disadvantage.
Market Competition and Customer Demands
European automakers, including Volkswagen and BMW, have pledged to electrify their fleets and have placed orders with both European and Asian battery suppliers. However, many still rely heavily on Chinese batteries for their current models due to cost and availability. This creates a complex dynamic where European manufacturers must compete for orders while also partnering with the very companies they are trying to displace.
Customer demand for affordable electric vehicles is growing, putting pressure on battery prices. Chinese batteries are often 20 to 30 percent cheaper than European ones, a significant advantage in a price-sensitive market. To win over automakers, European producers must not only match China's quality but also offer competitive pricing, which requires achieving economies of scale that are still out of reach.
Future Outlook and Strategic Imperatives
Looking ahead, industry analysts believe Europe can still carve out a significant niche in the battery market, particularly in premium segments and in the production of specialized cells. The continent's strong automotive industry, environmental regulations, and skilled workforce provide a solid foundation for growth. However, success will depend on faster decision-making, more aggressive investment, and greater collaboration across borders.
The next five years will be critical. If Europe can accelerate its gigafactory rollout and secure raw material supplies, it could achieve a market share of 20 to 25 percent by 2030. Failure to do so risks relegating the continent to a peripheral role, dependent on Asian imports for its energy transition. The stakes are high, and the time to act is now.
In conclusion, Europe's battery industry has promise but faces immense challenges. The gap with China is wide, and closing it will require coordinated efforts from governments, industry, and financial institutions. Innovation alone will not be enough; Europe must also build scale, secure supply chains, and compete on cost. The future of the region's automotive sector and its climate goals hang in the balance.
