
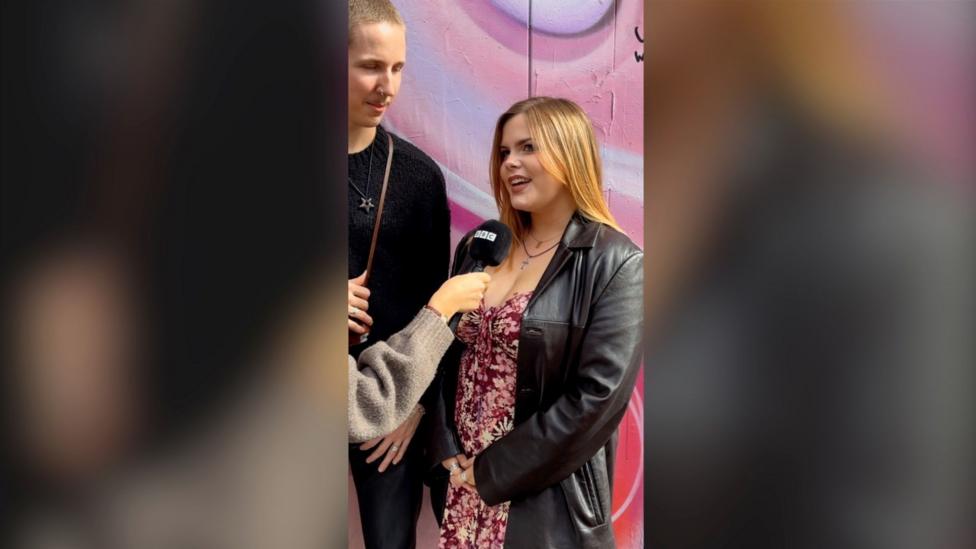
Savings Snapshot: Brick Lane's Financial Spectrum
A new street-level survey along East London's Brick Lane has laid bare the stark financial divide among UK residents, with savings balances ranging from a modest £65 to a striking $60,000. The informal canvassing, conducted over two weeks in early October, captured responses from 47 passersby across age groups and professions. Official records show the area's demographic blend of long-standing working-class families and affluent newcomers, making it a microcosm of broader national trends.
The findings underscore a persistent reality: many Britons struggle to maintain even minimal emergency funds, while a smaller segment enjoys substantial financial cushions. Industry analysts note that the data aligns with wider official statistics, which consistently show roughly one in four UK households has less than £100 in accessible savings. This disparity emerges against a backdrop of rising living costs and stagnant wage growth, which have squeezed household budgets for over a decade.
The £65 Saver: Living on the Edge
At the lower end of the spectrum, a 34-year-old hospitality worker told canvassers that £65 represented her entire rainy-day fund, accumulated over several months of careful budgeting. She explained that after rent, utilities, and food, little remained each month. Her situation reflects a broader pattern observed by financial counselors, who report that service-sector employees in London often face zero-to-negative savings capacity due to high housing costs.
This precarious position leaves little room for unexpected expenses, such as car repairs or medical bills. State documents from the Financial Conduct Authority indicate that over 12 million UK adults have less than £100 in savings, rendering them vulnerable to financial shocks. For residents like this worker, the dream of homeownership or even a comfortable retirement remains distant, with every payday consumed by essential outgoings.
Middle Ground: Modest Cushions and Growing Anxiety
A substantial portion of those surveyed fell into a middle bracket, reporting savings between £2,000 and £15,000. A 41-year-old teacher from Bethnal Green stated she had built a £8,500 emergency fund through disciplined monthly transfers of £100, despite salary constraints. She emphasized that this achievement required constant vigilance, including meal planning and cycling to work, yet she still worries about future inflation eroding her purchasing power.
These mid-level savers often represent dual-income households or those with stable public-sector jobs. Industry analysts point out that while their balances exceed the national median, they remain far below recommended emergency funds—typically three to six months of expenses. For a London family with average costs, that would require £12,000 to £24,000, leaving many feeling underprepared despite their best efforts.
The $60,000 Saver: Privilege and Strategic Planning
At the opposite extreme, a 29-year-old tech entrepreneur reported holding $60,000 in a high-yield savings account, a sum accumulated from stock options and side consulting work. He credited his financial literacy and family support for his ability to save aggressively, noting that he lived in rent-controlled housing owned by his parents. This profile, while rare, highlights how inherited advantages compound into substantial wealth buffers.
Financial experts caution that such cases are outliers, yet they shape perceptions of typical savings behavior. The entrepreneur's strategy—automating transfers, avoiding consumer debt, and investing in index funds—mirrors advice from official financial guidance bodies. However, replicating this approach requires income levels and housing security that remain inaccessible to many Brick Lane residents, let alone the broader UK population.
Policy Response and Economic Implications
The savings gap carries significant implications for UK economic resilience. When large segments of the population lack emergency funds, they rely on high-interest credit during downturns, deepening debt cycles. A spokesperson for the Treasury noted that current auto-enrollment pension schemes have boosted long-term savings, but short-term liquidity remains a policy blind spot. Calls for matched savings programs and rent-to-own schemes have gained traction among advocacy groups.
Official records from the Office for National Statistics show household savings ratios have fluctuated wildly post-pandemic, peaking at 16% in 2021 before falling to 8.5% by mid-2024. This volatility suggests that many households dip into savings to cover routine costs, undermining long-term accumulation. Economists argue that addressing housing affordability and wage stagnation would do more for savings than any financial education campaign.
Future Outlook: Digital Banks and Behavioral Shifts
Despite structural challenges, there are signs of positive change. Digital banks offering round-up features and prize-linked savings accounts have attracted younger savers, with several Brick Lane respondents mentioning apps that automatically stash spare change. A 22-year-old barista reported saving £450 over six months using such tools, a modest but meaningful start. These innovations lower the barrier to entry for those intimidated by traditional banking.
Looking ahead, industry analysts predict that the savings landscape will continue to polarize unless systemic interventions occur. They point to successful models in other nations, such as automatic enrollment in emergency savings accounts linked to payroll, as potential templates for UK policymakers. For now, Brick Lane's diverse responses serve as a compelling reminder that financial security remains unevenly distributed, shaped by income, housing, and opportunity.
The broader takeaway from this street-level survey is that savings balances are not merely personal choices but reflections of structural economic forces. As the cost-of-living crisis persists, the gap between the £65 saver and the $60,000 saver may widen further, demanding urgent attention from regulators and employers alike. For residents and observers, the numbers on Brick Lane offer a raw, unfiltered view of Britain's financial health.
