
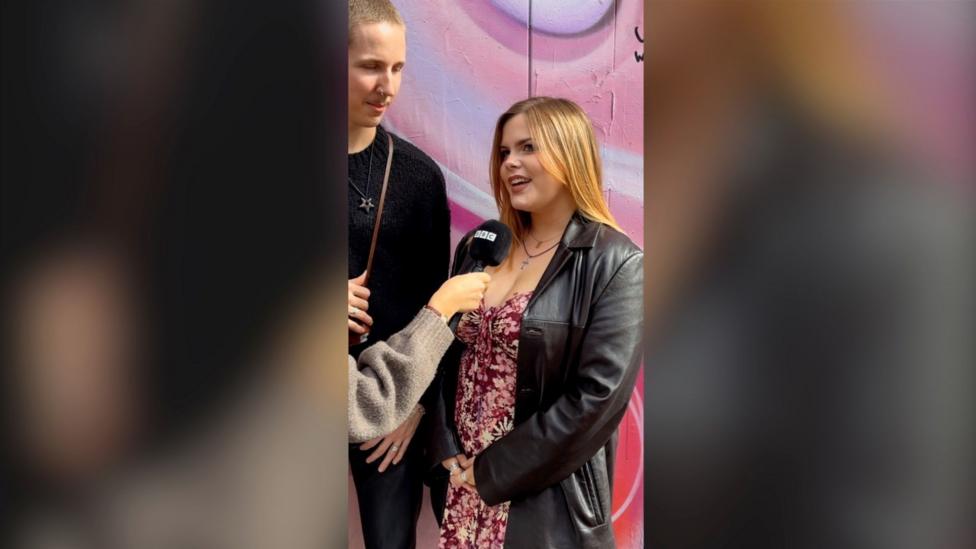
Brick Lane, the vibrant heart of East London's diverse community, has become an unlikely barometer of Britain's financial health. A new street-level survey reveals savings balances ranging from a modest £65 to an impressive $60,000 among local residents. The striking disparity underscores a widening wealth gap that persists even within a single neighborhood, raising urgent questions about economic mobility and financial security across the United Kingdom.
Brick Lane Survey Uncovers Stark Savings Disparity
The informal survey conducted along Brick Lane's bustling thoroughfare captured responses from dozens of passersby, shopkeepers, and longtime residents. Figures ranged dramatically, with younger workers reporting minimal emergency funds while established business owners held five-figure sums. This microcosm reflects national trends where the top 10% of savers hold nearly half of all household deposits, according to official banking records.
Local financial advisors note that Brick Lane's unique blend of immigrant entrepreneurs, creative professionals, and service workers creates a natural laboratory for studying economic behavior. The area's transformation from textile district to tech hub has attracted new wealth while longtime residents struggle with rising rents. These dynamics directly influence how much individuals can set aside each month.
Why Savings Balances Vary So Widely in East London
Industry analysts attribute the savings gap to multiple factors including income instability, housing costs, and financial literacy. Brick Lane's rental market has surged 40% over five years, consuming disposable income that might otherwise flow into savings accounts. Meanwhile, self-employed traders face irregular earnings, making consistent deposits challenging despite high revenue months.
The £65 balance reported by a young hospitality worker highlights a growing precariat class. This individual, like many peers, maintains multiple part-time roles yet struggles to build an emergency cushion. Financial counselors report that such minimal savings leave households vulnerable to unexpected expenses, forcing reliance on high-interest credit products.
Historical Context of UK Personal Savings Trends
Britain's savings culture has shifted dramatically since the post-war era when building societies dominated the landscape. The 1980s financial deregulation introduced competitive interest rates, yet the 2008 crisis eroded public trust in banking institutions. Today's low-rate environment further discourages traditional saving, pushing many toward riskier investment vehicles.
Official statistics show the UK household savings ratio hovering near historic lows at 8.2% of disposable income. This compares unfavorably with France's 15% and Germany's 19%, reflecting structural differences in pension provision and social safety nets. Brick Lane's diverse population mirrors these national challenges while adding local complexity.
Regulatory and Policy Responses to Savings Inequality
Government initiatives like the Lifetime ISA and Help to Buy schemes have attempted to incentivize saving, particularly among younger demographics. However, take-up remains concentrated among higher earners who can afford to lock away funds. Policy analysts argue that auto-enrollment pension reforms should be extended to short-term savings products to address this gap.
The Financial Conduct Authority recently proposed new rules requiring banks to offer fairer interest rates on easy-access accounts. Currently, major institutions pay as little as 1.5% while base rates sit at 4.5%, creating a hidden transfer from savers to lenders. Brick Lane residents interviewed expressed frustration at this discrepancy, with several moving funds to online challenger banks.
Public Impact and Community Responses on Brick Lane
Local community centers have launched financial education workshops in response to the survey's findings. These sessions cover budgeting basics, emergency fund building, and navigating government support programs. Organizers report strong attendance from both young renters and older residents seeking to maximize limited incomes.
Small business owners along Brick Lane describe a dual reality: thriving commerce coexisting with personal financial fragility. Several restaurateurs mentioned keeping substantial business reserves while personally holding minimal savings, a common strategy among entrepreneurs who reinvest profits. This behavior explains some high balances while masking underlying vulnerability.
Future Outlook for UK Savings and Financial Resilience
Economic forecasters predict continued pressure on savings rates as inflation remains above the Bank of England's 2% target. Real wage growth has stalled, particularly in service sectors prevalent around Brick Lane. Without intervention, the savings gap between asset-rich homeowners and asset-poor renters will likely widen further.
Innovative fintech solutions, including round-up apps and micro-investment platforms, offer new pathways for small savers. However, adoption requires smartphone access and digital literacy, which remain uneven across demographic groups. Community leaders advocate for hybrid approaches combining technology with traditional face-to-face financial guidance.
The Brick Lane survey serves as a powerful reminder that national statistics obscure local realities. A single street can contain both extreme financial precarity and substantial wealth accumulation. Addressing this divide demands coordinated action from policymakers, financial institutions, and community organizations to ensure all Britons can build meaningful savings buffers.
As East London continues its rapid transformation, the savings habits of its residents will shape the neighborhood's future resilience. Whether through policy reforms or grassroots education, closing the savings gap remains essential for sustainable economic health. The stories collected on Brick Lane offer both warning and inspiration for communities nationwide.
