
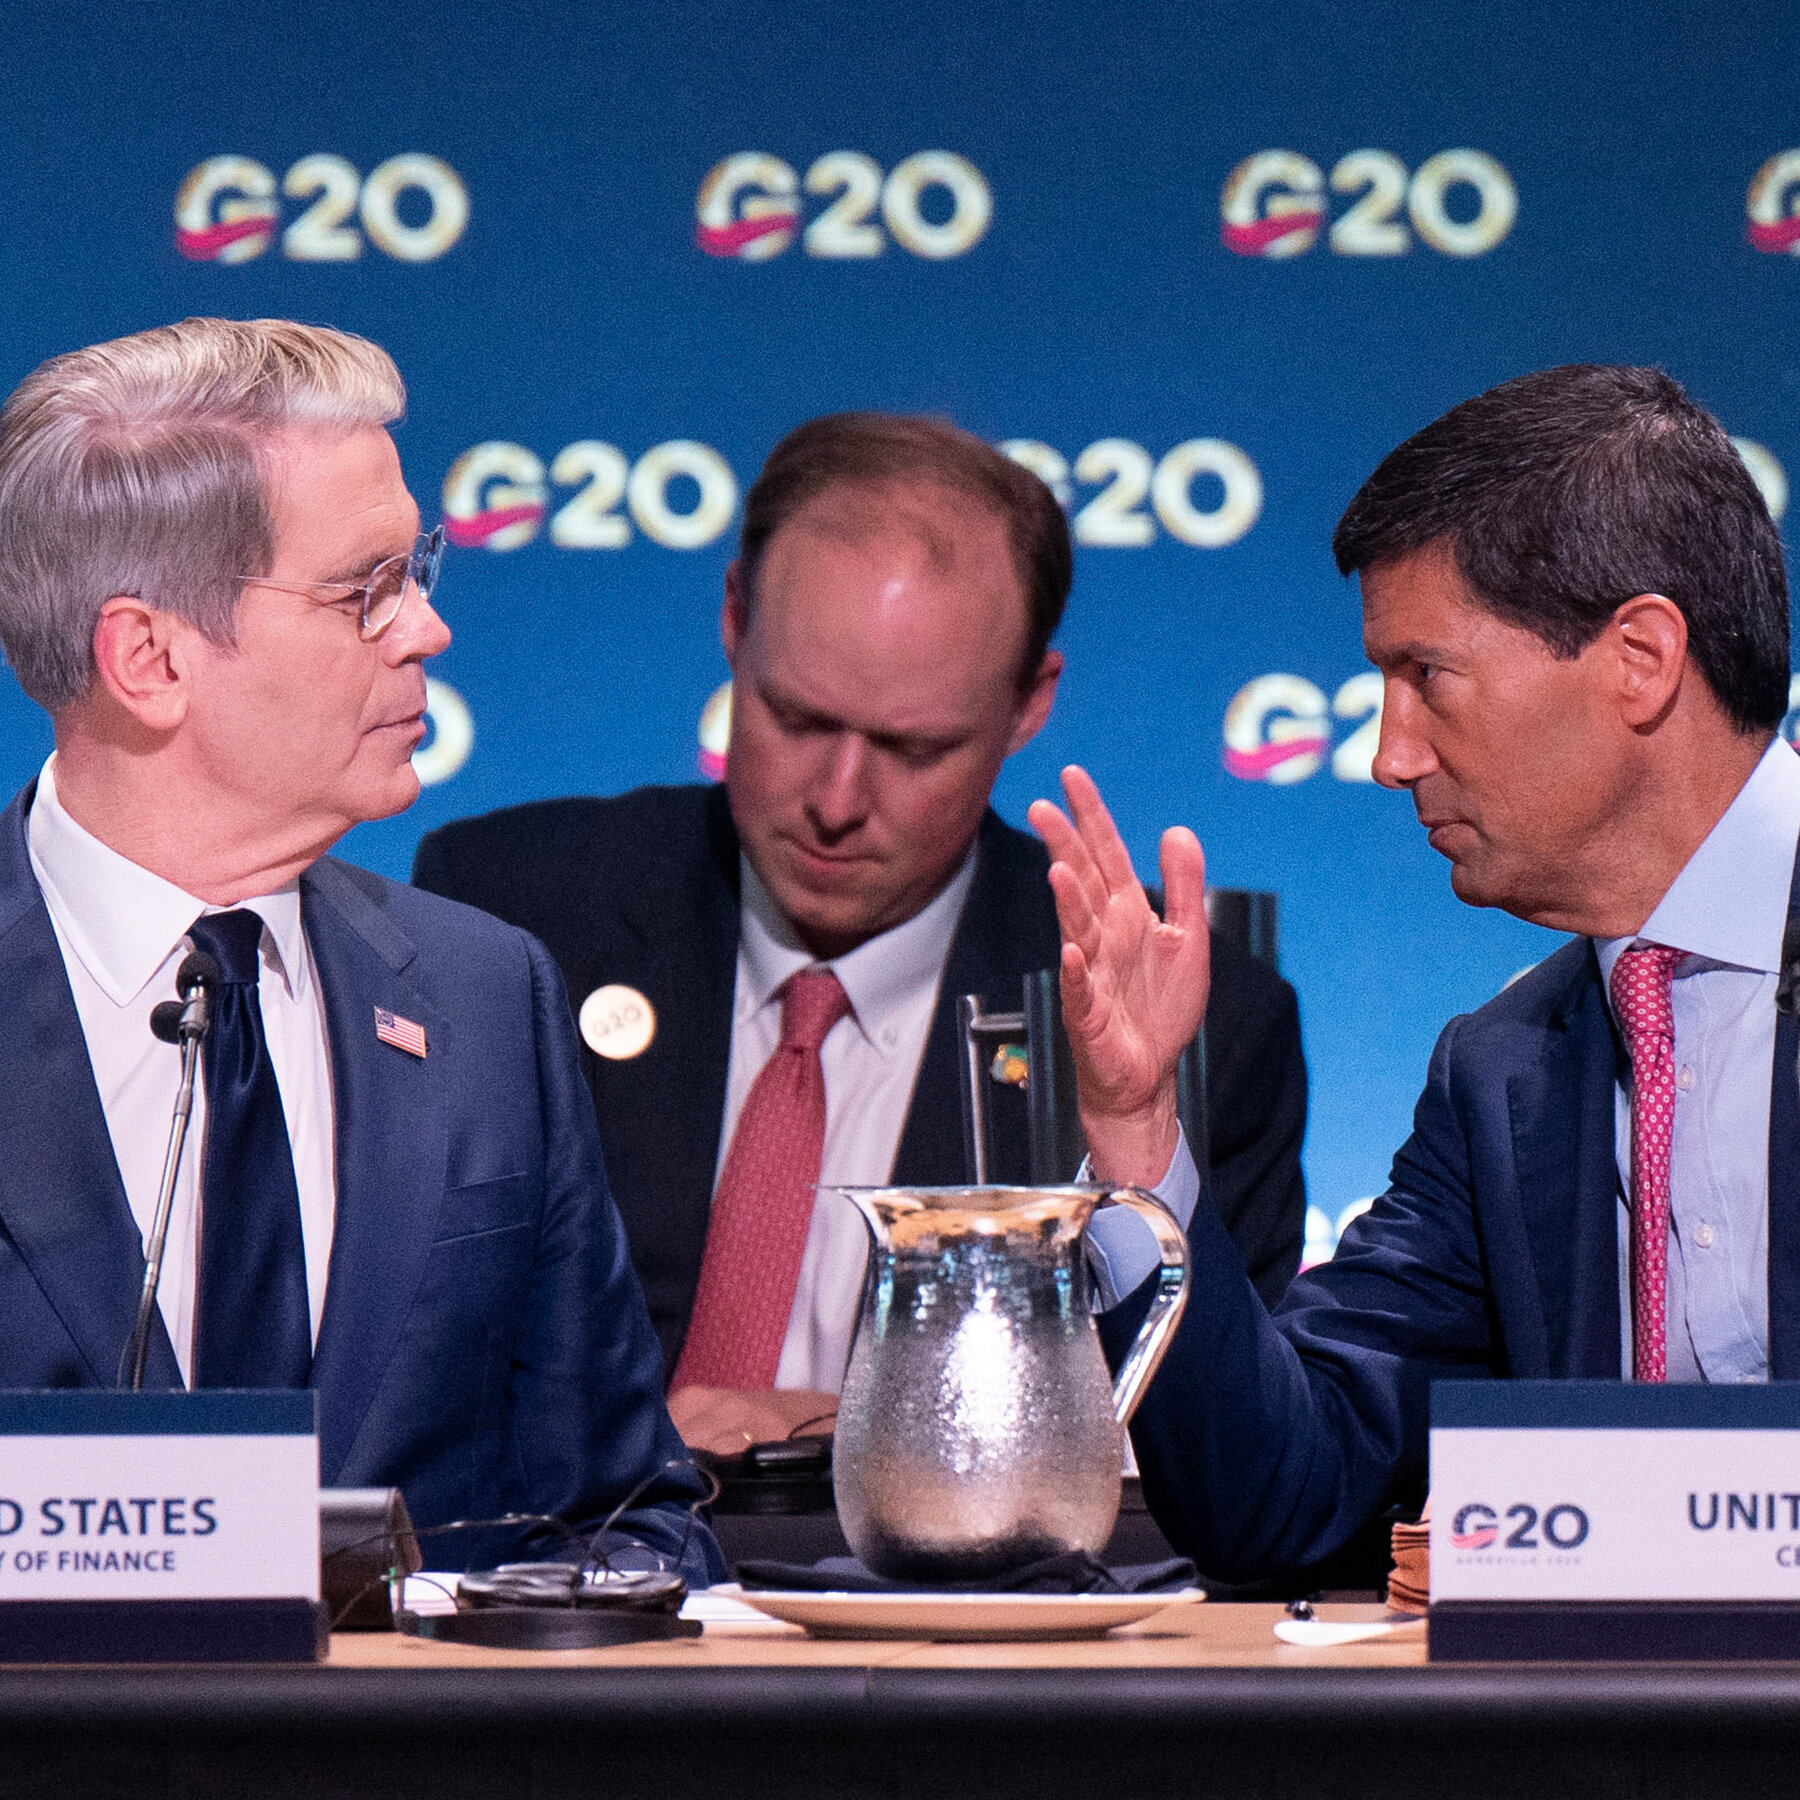
Bond Market Pressures Test Washington's Economic Guardians
Treasury Secretary Scott Bessent and Federal Reserve Chairman Kevin Warsh face a converging challenge as bond investors grow increasingly wary of persistent inflation and widening federal deficits. Their responses, delivered through public statements and policy signals, are being closely monitored by market participants seeking clarity on the nation's fiscal and monetary trajectory. The stakes are high, with long-term borrowing costs already reflecting heightened risk premiums.
The bond market's recent selloff has pushed yields on 10-year Treasury notes to multi-year highs, a development that threatens to raise borrowing costs for consumers and businesses alike. Investors are demanding greater compensation for holding longer-dated government debt, driven by concerns that fiscal expansion will keep inflation above the central bank's 2 percent target. This dynamic places both officials in a delicate position as they attempt to reassure markets without overpromising policy action.
Inflation Expectations and the Fed's Credibility Test
Chairman Warsh, who took the helm of the Federal Reserve earlier this year, has emphasized the importance of anchoring inflation expectations. In his recent testimony before Congress, he reiterated the central bank's commitment to data-dependent decision-making, signaling that interest rates will remain restrictive until price pressures show sustained signs of easing. However, market-based measures of inflation expectations have crept upward, suggesting that investors doubt the Fed's ability to achieve its target without triggering a recession.
The Federal Reserve's preferred inflation gauge, the core personal consumption expenditures price index, has hovered around 2.8 percent for several months, well above the 2 percent goal. While supply chain improvements and moderating energy costs have helped, services inflation remains sticky, driven by rising wages and housing costs. Warsh's communications strategy has aimed to strike a balance between hawkish vigilance and flexibility, but bond traders are demanding more concrete evidence of progress.
Treasury's Fiscal Path and Debt Sustainability Concerns
Secretary Bessent's challenge lies in convincing investors that the federal government's debt trajectory is sustainable over the long term. The Treasury's quarterly refunding statement highlighted plans to increase auction sizes for longer-dated securities, a move that has exacerbated supply concerns in the bond market. Bessent has argued that economic growth, fueled by productivity-enhancing policies, will eventually narrow the deficit, but skeptics point to entitlement spending and interest costs as structural drags.
The Congressional Budget Office projects that federal debt held by the public will reach 116 percent of GDP by 2034, up from 97 percent in 2023. This upward trajectory, driven by mandatory spending and net interest payments, has prompted credit rating agencies to flag potential downgrades. Bessent has responded by emphasizing the administration's commitment to spending discipline, though detailed proposals remain sparse, leaving bond investors to price in a higher risk premium.
Market Reactions and Investor Sentiment Shifts
The bond market's mood has shifted noticeably from the complacency that characterized the post-pandemic period. Term premiums, which compensate investors for the risk of holding long-term bonds, have turned decisively positive after years of suppression. Analysts attribute this change to a combination of quantitative tightening, increased Treasury supply, and diminished confidence in the fiscal outlook. These factors have collectively created an environment where bond bears are gaining influence.
Portfolio managers report that clients are increasingly allocating toward inflation-protected securities and shorter-duration instruments to hedge against uncertainty. The yield curve, while still inverted at the short end, has steepened notably, reflecting expectations of higher long-term rates. This repositioning suggests that investors are not convinced that either the Fed or the Treasury can deliver the stability promised in official communications.
Policy Coordination and Communication Strategies
Bessent and Warsh have signaled a commitment to regular coordination on economic policy, a departure from the sometimes tense relationship between their predecessors. Their joint appearances and public statements have emphasized a shared understanding of the challenges ahead, particularly the need to avoid fiscal-monetary conflict. This alignment is intended to reassure markets that policy actions will be complementary rather than contradictory.
However, limits to coordination remain, as the Fed's independence in setting monetary policy is a cornerstone of its credibility. Warsh has been careful to distinguish his role from that of the Treasury, noting that the central bank will not be swayed by political pressure to ease conditions prematurely. Bessent, for his part, has underscored that fiscal decisions rest with Congress, while the Treasury executes the nation's financing needs.
Global Implications and Future Outlook
The stakes extend beyond US borders, as Treasury securities serve as the global benchmark for risk-free assets. A sustained rise in yields could tighten financial conditions worldwide, affecting emerging markets that borrow in dollars and multinational corporations with dollar-denominated debt. International investors are watching closely, with some central banks diversifying reserves into alternatives, a trend that bears monitoring.
Looking ahead, both officials face a critical window in the coming months to demonstrate that their policies can restore confidence. The Fed's next policy meeting will be scrutinized for any shift in guidance, while the Treasury's quarterly refunding will reveal auction plans. If inflation continues to moderate and deficits show signs of narrowing, the bond market may stabilize, but the margin for error remains thin.
Industry analysts suggest that a coordinated approach, combining fiscal restraint with monetary patience, offers the best path forward. Yet, political realities may complicate such a strategy, as spending pressures from defense, infrastructure, and social programs collide with revenue constraints. The coming year will test whether Washington can meet the bond market's demands without sacrificing economic growth.
In the interim, investors are advised to remain vigilant, as the interplay between fiscal and monetary policy will continue to shape market dynamics. The actions of Bessent and Warsh, while carefully calibrated, will ultimately be judged by the data. Their success in calming the bond bears will depend on delivering tangible progress on inflation and deficits.
