
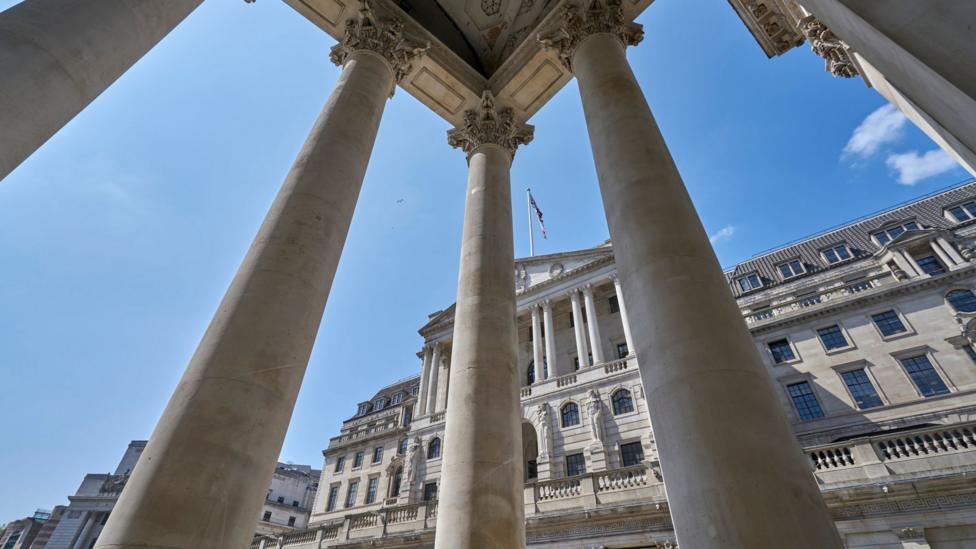
The Bank of England's Monetary Policy Committee convened this week in London under intense scrutiny, as persistent domestic inflation projections complicate the timeline for long-anticipated borrowing cost reductions. While policymakers are broadly expected to maintain the benchmark lending rate at its current elevated level for now, accelerating cost pressures across key consumer sectors are forcing officials to reconsider potential tightening measures before the fiscal year concludes.
Monetary Policy Committee Confronts Escalating Inflation
Central bank governors remain locked in a delicate balancing act between stabilizing overall consumer prices and safeguarding fragile economic expansion across the United Kingdom. Recent official data indicates that core inflation metrics, which strip out volatile energy and food expenditures, have demonstrated unexpected resilience, remaining persistently higher than statutory targets set by macroeconomic regulatory authorities.
Institutional economic analysts suggest that previous interest rate increases have not completely dampened aggregate consumer demand in service industries. Wage growth metrics continue to outpace productivity measures in several competitive sectors, creating strong underlying price momentum that threatens to embed elevated costs deeply into household budgets and enterprise planning for several consecutive fiscal quarters.
Rising Consumer Costs Complicate Lending Landscape
The persistence of elevated retail price indices has created widespread market uncertainty for commercial banking institutions and mortgage providers. Financial lenders have adjusted their underlying product pricing models upward, anticipating that official benchmark lending rates will stay higher for a considerably longer period than previous market consensus had originally estimated during earlier seasonal projections.
This prolonged period of restricted liquidity continues to put pressure on millions of residential property owners seeking to refinance expiring fixed-term loan packages. Regulatory reports indicate that average household mortgage repayments have expanded substantially, reducing discretionary spending capital and prompting consumer-facing retail businesses to lower their overall revenue projections for the coming months.
Diverging Forecasts Prompt Divided Regulatory Opinions
Disagreements within the central bank's decision-making apparatus have become increasingly evident in recent public commentary and institutional statements. Hawkish committee members argue that failing to enact additional rate increases risks allowing second-round inflationary effects to become structural, which would necessitate significantly more drastic monetary interventions in future fiscal cycles.
Conversely, more dovish monetary authorities contend that overtightening policy could prematurely choke off fragile private investment and exacerbate unemployment across manufacturing hubs. Industry analysts point out that corporate insolvencies have already trended upward in response to existing financing costs, warning that further restrictions could trigger a broader industrial contraction.
Institutional Responses and Broader Market Impact
Financial market participants have responded to the hawkish signaling by recalibrating sovereign bond yields and foreign exchange currency valuation models. Government debt instruments have seen increased volatility as institutional asset managers hedge against the distinct possibility that borrowing costs may not experience downward adjustments until well into the next operating calendar.
Major business trade associations have publicly urged the central bank to provide greater long-term guidance and predictability regarding macroeconomic targets. Industry leaders assert that persistent ambiguity around future borrowing costs hinders critical infrastructure investments, discourages foreign direct capital flows, and impedes medium-term hiring plans across multiple commercial industrial sectors.
Future Outlook for UK Monetary Stability
Looking ahead to the upcoming quarterly policy assessment cycles, central bank officials will heavily scrutinize labor market data and global supply chain cost variables before reaching a definitive consensus. The trajectory of international commodity pricing and domestic energy tariffs will play a decisive role in determining whether further benchmark rate hikes will be formally mandated.
As the governing board prepares its comprehensive policy statement, market observers across the national economy remain focused on the potential timeline for stabilization. The decisions finalized over the coming months will fundamentally dictate the structural path of economic recovery, business investment health, and household purchasing power through the remainder of the decade.
