
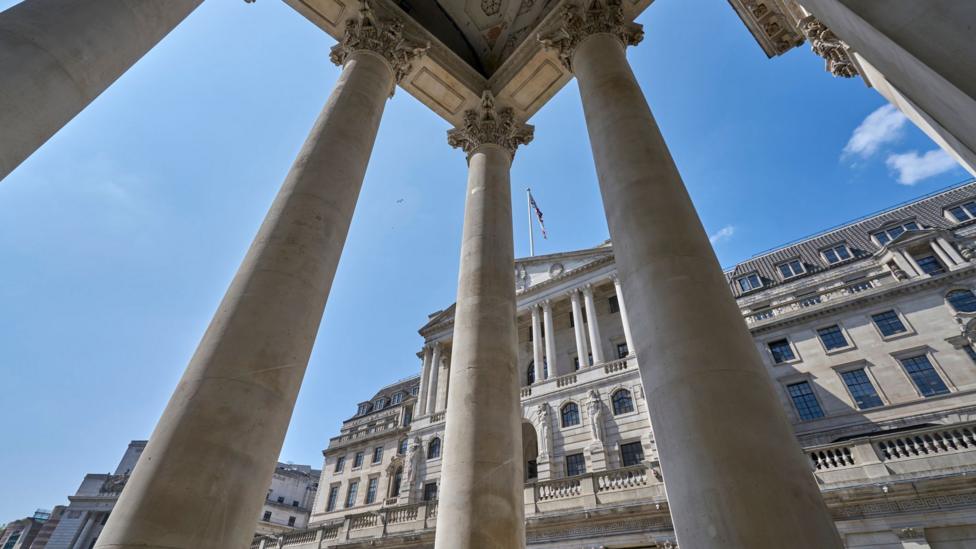
The Bank of England is preparing for an intricate monetary policy balancing act this month as policymakers navigate stubborn price pressures and sluggish domestic growth. With fresh financial projections showing persistent headline inflation, central bank leaders must determine whether holding benchmark borrowing costs steady will adequately stabilize markets without triggering severe economic contraction across commercial and consumer lending sectors.
Inflation Projections Challenge Current Monetary Strategy
Recent economic indicators suggest consumer price index data could trend upward in coming quarters, driven by volatile energy markets and resilient service sector costs. While previous policy interventions managed to curtail rapid price increases, persistent wage growth continues to present structural challenges that prevent inflation from settling smoothly into the regulatory target range.
Market analysts and institutional researchers point out that core consumer metrics remain elevated, creating genuine uncertainty for central bank policymakers. If price acceleration gains renewed momentum throughout the autumn, existing policy frameworks will face significant stress, requiring decisive regulatory intervention to prevent secondary inflationary spikes from embedding permanently across retail pricing tiers.
The Complex Trade-Off Between Growth and Price Stability
Holding benchmark lending rates at their current high baseline offers temporary respite for business investment, but lingering inflation erodes consumer purchasing capacity. Central bankers must constantly assess whether additional tightening will extinguish remaining inflationary embers or unintentionally depress fragile private sector activity, corporate capital expenditures, and industrial output across the country.
Commercial lending institutions and corporate finance desks are already seeing reduced borrowing appetite, as elevated debt service obligations constrain expansion plans. A premature pivot toward aggressive tightening could further dampen credit liquidity, while prolonged indecision might signal institutional complacency to currency markets and international debt purchasers evaluating sovereign risk.
Government economic advisors and fiscal planners are closely monitoring these interest rate developments, recognizing that central bank choices directly affect domestic sovereign debt servicing costs. Balancing public expenditure commitments against restrictive credit conditions leaves fiscal authorities with minimal leeway to stimulate domestic industries without exacerbating broad inflationary momentum.
Household Finances Under Sustained Borrowing Pressure
For average households, the ongoing monetary policy standoff directly impacts residential mortgage refinancing and unsecured personal credit lines. Millions of residential mortgage holders transitioning off favorable fixed-rate packages face dramatically elevated monthly payments, significantly reducing disposable household income and curtailing broader discretionary retail spending across domestic shopping districts.
Housing market transaction volumes have demonstrated noticeable softening over consecutive fiscal quarters as buyers encounter stricter affordability assessments and expensive financing options. Real estate market analysts note that prolonged uncertainty regarding the terminal interest rate trajectory will likely prolong this stagnation phase, dampening residential property construction and related trade activities.
Global Central Banking Context and Diverging Paths
International central banking peers across North America and mainland Europe are facing comparable structural dilemmas, yet their regulatory paths are beginning to diverge. As major foreign monetary authorities explore localized rate reductions or extended pauses, national central banks must evaluate currency exchange differentials that directly influence import costs and domestic consumer price dynamics.
A widening interest rate differential against other major trading partners can weaken domestic currency valuations, thereby increasing the cost of imported commodities and intermediate manufacturing components. Consequently, monetary officials must calibrate domestic policy not only against internal macroeconomic data but also in direct response to broad global capital movements.
Anticipated Timelines and Future Policy Triggers
Financial markets are pricing in a high probability of static borrowing costs during upcoming rate-setting sessions, yet expectations for year-end adjustments remain fluid. Policy decision-makers have repeatedly signaled that incoming labor market statistics, consumer confidence figures, and international trade performance indices will serve as essential catalysts for any decisive monetary adjustments.
Should upcoming quarterly earnings reports and industrial production data reveal sudden macroeconomic cooling, central bank leaders may feel compelled to maintain stable credit terms indefinitely. Conversely, persistent wage settlements exceeding productivity gains would likely reignite arguments for targeted monetary tightening to re-anchor medium-term price stability across commercial markets.
Navigating the approaching fiscal cycle demands exceptional institutional dexterity from monetary leadership as conflicting economic pressures intensify. The coming months will prove critical in establishing whether existing macroeconomic mechanisms can successfully steer domestic commerce toward steady disinflation without triggering widespread corporate bankruptcies, elevated unemployment rates, or prolonged national economic stagnation.
