
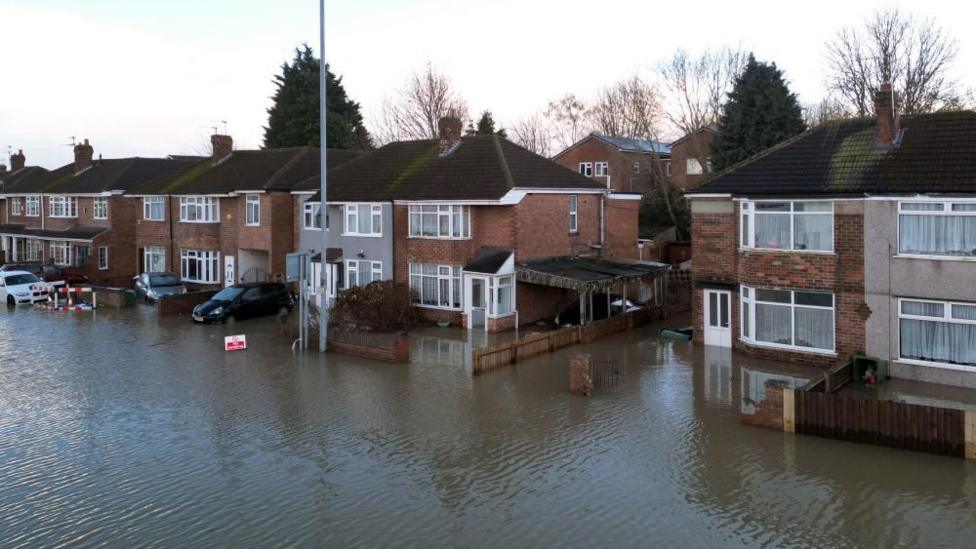
Aviva Chief Flags Looming Insurance Crisis for New Housing
Amanda Blanc, chief executive of Aviva, one of Britain's largest insurers, has issued a stark warning that England is "for sure" constructing homes that could become uninsurable in the future due to escalating flood risks. Speaking at a public event, Blanc highlighted that current building practices are placing properties in vulnerable locations without adequate safeguards, creating long-term financial and safety hazards for homeowners.
The insurance industry has long urged policymakers to align housing development with climate resilience standards. Blanc's statement reinforces growing concern that without urgent planning reforms, thousands of new dwellings could be left without coverage, leaving owners exposed to devastating financial losses and undermining the broader property market.
Why New Homes Face Rising Flood Exposure
Flood risk in England has escalated sharply over the past decade, driven by heavier rainfall, rising sea levels, and increased urbanisation on floodplains. Government data shows that nearly one in six homes in England currently faces some level of flood risk, with projections indicating this figure will climb as climate change accelerates.
Developers often receive planning permission on land that is technically within flood zones, provided they implement mitigation measures. However, critics argue that these measures are frequently insufficient or poorly maintained, leaving residents with inadequate protection. Blanc's comments highlight a systemic issue where short-term housing targets conflict with long-term climate realities.
Insurers calculate premiums based on risk models that factor in flood data, property elevation, and flood defence infrastructure. As risk intensifies, underwriters may either raise premiums sharply or refuse coverage altogether, a scenario that Blanc says is increasingly plausible for newly built properties.
Official Response and Regulatory Context
The UK government has acknowledged the growing threat, introducing measures such as the Flood Re scheme, which provides subsidised insurance for high-risk homes. However, Flood Re is set to expire in 2039, and experts warn that without structural improvements, many properties will simply fall outside its protective umbrella.
Ministers have pledged to update planning guidance to include stricter flood resilience standards, but implementation has been slow. Local authorities often lack the resources to enforce robust conditions, and developers face limited incentives to exceed minimum requirements, creating a patchwork of inconsistent protections.
Industry analysts point out that the government's target of building 300,000 new homes annually puts pressure on councils to approve developments quickly, sometimes at the expense of environmental due diligence. This tension between housing supply and climate adaptation remains a central policy challenge.
Economic and Public Impact of Uninsurable Homes
If new homes become uninsurable, the consequences would ripple through the economy. Mortgage lenders typically require buildings insurance as a condition of loans, so uninsurable properties would become unsellable and unmortgageable, effectively trapping owners and depressing property values in affected areas.
Homeowners in flood-prone regions already face premiums averaging £300 to £500 more per year than those in low-risk areas. Should coverage become unavailable, families could lose their largest asset, and local economies would suffer from reduced investment and population decline.
Public awareness remains low, with many buyers unaware of a property's flood history until they attempt to secure insurance. Consumer groups are calling for mandatory flood risk disclosure at the point of sale, a move that would empower buyers and encourage developers to build safer.
Industry Calls for Stronger Building Standards
Aviva and other major insurers have repeatedly called for mandatory flood resilience standards in new builds, including raised floor levels, flood-resistant materials, and better drainage systems. Blanc's warning underscores the urgency, as retrofitting properties after construction is far costlier than building safely from the outset.
The insurance sector has also proposed a national flood resilience strategy that would integrate land-use planning, infrastructure investment, and natural flood management. Such an approach would not only protect individual homes but also reduce pressure on public finances and emergency services.
Some local councils have begun experimenting with 'blue-green' infrastructure, such as permeable pavements and urban wetlands, which absorb excess water and reduce runoff. These innovations show promise, but adoption remains sporadic and underfunded, requiring a coordinated national push to become standard practice.
Future Outlook and Necessary Reforms
Experts predict that the number of properties at significant flood risk could double by 2050 under current emission trajectories. Without decisive action, the insurance market may retreat from high-risk zones, leaving entire communities without a safety net.
Blanc's warning serves as a catalyst for renewed debate, but lasting change will require legislative action. Updating the National Planning Policy Framework to mandate climate resilience, extending Flood Re beyond 2039, and investing in natural defences are all critical steps that policymakers must take.
For prospective buyers, the message is clear: due diligence on flood risk is no longer optional. For developers and regulators, the time to build smarter has arrived, as the cost of inaction will be measured not only in pounds but in the security and livelihoods of future generations.
