
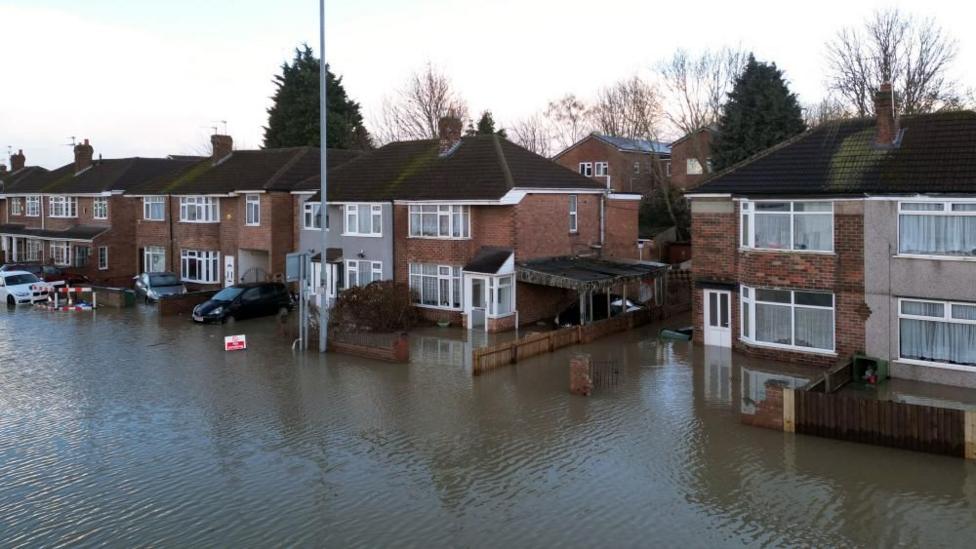
Aviva Chief Warns of Rising Flood Threat to Future Housing
The chief executive of Aviva, Amanda Blanc, has issued a stark warning that England is "for sure" constructing homes that may become uninsurable in the future due to escalating flood risks. Her statement, delivered during a recent industry briefing, underscores growing concerns about climate change's impact on the property sector. The comments highlight a potential crisis for homeowners and developers alike.
Blanc's warning comes as the UK grapples with increasingly frequent and severe flooding events. Official records show that extreme weather patterns have intensified over the past decade, placing significant strain on existing flood defenses. The insurance giant's assessment aligns with broader industry data indicating that new developments in high-risk zones are particularly vulnerable to long-term climate shifts.
The Scope of the Uninsurable Homes Risk in England
The Aviva chief's remarks point to a systemic issue where planning permissions are granted without fully accounting for future climate scenarios. Analysts suggest that thousands of properties, especially those near rivers and coastal areas, could face prohibitively high premiums or outright coverage denial. This situation threatens to destabilize the housing market and create stranded assets for investors.
Current flood risk maps, while comprehensive, often rely on historical data that may not accurately predict future conditions. Industry experts argue that a forward-looking approach is essential, incorporating models that factor in rising sea levels and increased rainfall intensity. Without such measures, the gap between insurable and uninsurable properties is expected to widen considerably.
The economic implications are significant, as property values in flood-prone areas could plummet if insurance becomes unavailable. Mortgage lenders, who typically require coverage as a condition for loans, may also tighten lending criteria in these regions. This cascading effect could impact local economies and reduce the availability of affordable housing in affected communities.
Government and Regulator Responses to Flood Risk Concerns
In response to these warnings, government officials have emphasized their commitment to strengthening flood resilience through infrastructure investments and updated planning guidelines. Recent policy announcements include increased funding for flood defenses and stricter requirements for sustainable drainage systems in new developments. However, critics argue that these measures may not be sufficient to address the scale of the challenge.
Regulatory bodies have also been reviewing the Flood Re scheme, a reinsurance program designed to keep household premiums affordable. While the current scheme is set to operate until 2039, its long-term sustainability is uncertain. Stakeholders are calling for a clear roadmap to transition to risk-reflective pricing while ensuring that vulnerable households remain protected.
The insurance industry, through trade associations, has urged policymakers to adopt a more proactive stance on climate adaptation. This includes mandating higher building standards and discouraging development in high-risk zones altogether. Such measures, they argue, would reduce the future burden on both insurers and the public purse.
Impact on Homeowners and the Broader Property Market
For current homeowners in flood-prone areas, the warning signals potential financial strain as premiums continue to rise. Even with flood defenses in place, insurance costs are likely to reflect the increasing probability of severe weather events. Homeowners may need to invest in property-level resilience measures, such as flood barriers and sump pumps, to secure affordable coverage.
Prospective buyers are also expected to become more cautious, with flood risk becoming a key factor in purchasing decisions. Estate agents report that properties with a known flood history are already taking longer to sell and achieving lower prices. This trend is likely to intensify as awareness of climate risks grows among the general public.
The construction sector faces its own challenges, as developers must balance the demand for new housing with the need to avoid high-risk locations. Some are exploring innovative design solutions, including raised foundations and water-resistant materials, to mitigate potential damage. However, these adaptations come at a cost, which may ultimately be passed on to buyers.
Future Outlook and Recommendations for Resilience
Looking ahead, industry analysts emphasize that addressing this issue requires a coordinated effort across government, insurers, and developers. A comprehensive national strategy for flood risk management is essential, integrating land-use planning, infrastructure investment, and community engagement. Without such a strategy, the warning from Aviva's leadership could become a self-fulfilling prophecy.
There is also a growing call for enhanced data sharing between the public and private sectors to improve flood risk modeling. By leveraging advanced analytics and real-time monitoring, stakeholders can make more informed decisions about where and how to build. This would help ensure that future housing developments are both sustainable and insurable.
Ultimately, the message from the insurance industry is clear: proactive adaptation is far more cost-effective than reactive recovery. Investing in resilient infrastructure and smarter planning today can prevent billions of pounds in future damages. The time to act is now, before the risk of uninsurable homes becomes a widespread reality across England.
