
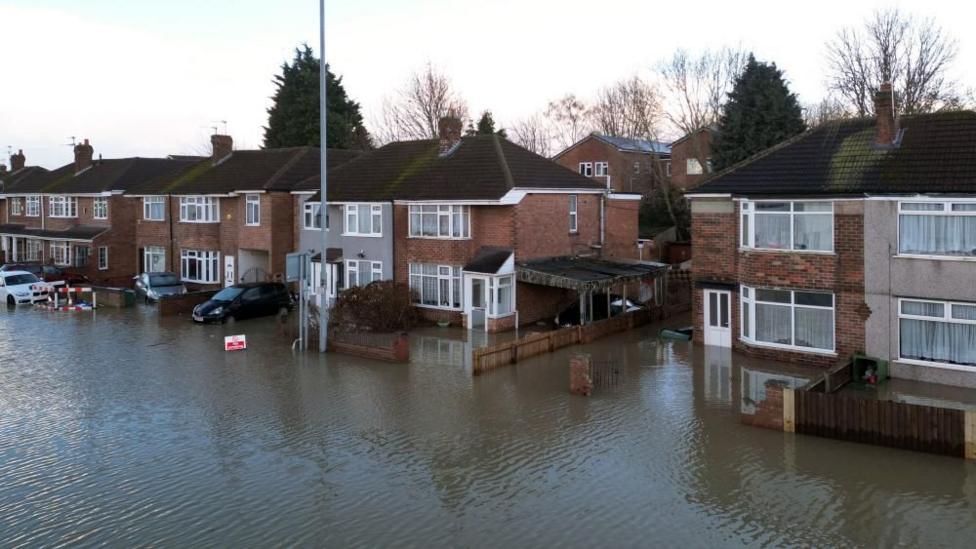
Aviva Chief Executive Issues Stark Warning on Future Housing
Amanda Blanc, chief executive of British insurer Aviva, told an audience of industry leaders that England is "for sure" constructing homes that may become uninsurable at some point in the future. Her comments came during a recent financial services conference in London, where she addressed mounting concerns over climate-related property risks. The warning signals a growing divide between current planning approvals and the realities of a changing climate, with implications for homeowners, developers, and government policy.
Blanc's statement reflects a broader trend across the insurance sector, where flood risk modeling has become increasingly sophisticated. Industry analysts note that properties situated in flood-prone areas are facing higher premiums or declining coverage offers altogether. The Aviva chief's remarks align with data showing that extreme weather events have become more frequent across the United Kingdom, prompting insurers to reassess their exposure. This shift is forcing difficult conversations about where and how the nation builds its future housing stock.
The Growing Threat of Flood Risk to Property Values
Flood risk has emerged as one of the most significant threats to property values in England, according to environmental agencies and real estate analysts. Recent government data indicates that over five million properties in England are currently at risk of flooding, a number projected to rise substantially in coming decades. The Environment Agency has mapped vast areas of land that could become inundated as rainfall patterns intensify, placing swaths of existing and planned developments in jeopardy.
The financial implications are substantial, with some estimates suggesting that flood damage costs the UK economy billions of pounds annually. For individual homeowners, the consequences can be devastating, ranging from unaffordable premium increases to complete loss of coverage. Real estate experts warn that properties designated as high flood risk could see dramatic price depreciation, creating potential negative equity traps for unsuspecting buyers. This dynamic threatens to create pockets of stranded assets across the country.
Planning System Under Scrutiny Amid Rising Climate Concerns
The UK planning system has come under renewed scrutiny following Blanc's comments, with critics arguing that development approvals have historically paid insufficient attention to flood risk data. Local councils face pressure to meet housing targets while balancing environmental constraints, often resulting in approvals for developments on floodplains. Government officials have acknowledged the tension, noting that updated planning guidance emphasizes the need for sustainable drainage systems and flood resilience measures in new builds.
Developers, however, maintain that current regulations already require rigorous flood risk assessments before construction begins. Industry representatives point to examples of innovative design solutions, including raised floor levels and flood-resistant materials, that mitigate potential damage. Yet insurance executives counter that these measures may prove insufficient against the scale of flooding projected under climate change scenarios. The disconnect between planning permission standards and long-term insurability remains a key point of contention.
Insurance Industry Response and Market Implications
Insurance companies have been quietly adjusting their underwriting practices in response to escalating flood risk, with some limiting new policies in high-risk zones. The Association of British Insurers has repeatedly called for greater investment in flood defenses and more stringent planning controls. Industry analysts suggest that without meaningful intervention, certain areas could become effectively uninsurable within a generation, leaving homeowners without financial protection against catastrophic losses.
The market has seen a rise in specialist flood insurance providers offering coverage at premium rates, but affordability remains a significant barrier for many households. Government-backed schemes like Flood Re have provided a temporary safety net, yet their long-term sustainability is uncertain. Insurance experts warn that without systemic changes, the burden of flood risk will increasingly fall on property owners and taxpayers, reshaping the housing market in unpredictable ways.
Public and Economic Impact of Uninsurable Properties
The prospect of uninsurable homes carries profound implications for ordinary families, particularly those in lower-income brackets who may be priced out of safer areas. Mortgage lenders typically require buildings insurance as a condition of approval, meaning uninsurable properties effectively become unsellable through traditional financing routes. This could trap existing homeowners in properties they cannot sell or insure, creating financial hardship and limiting mobility.
Economic analysts point to potential ripple effects on local economies, with declining property values reducing council tax revenues and diminishing community investment. Areas identified as high flood risk may struggle to attract new businesses or retain existing ones, accelerating economic decline. The broader fiscal impact could be substantial, with government potentially forced to step in as insurer of last resort or fund extensive adaptation measures.
Future Outlook and Calls for Policy Reform
Looking ahead, climate scientists project continued increases in extreme rainfall events across England, suggesting that flood risk will only intensify in coming years. Blanc's warning adds urgency to calls from environmental groups and insurance bodies for a comprehensive national strategy addressing both mitigation and adaptation. Proposals include stricter planning restrictions in flood zones, substantial investment in natural flood management, and mandatory flood resilience standards for all new construction.
Government officials have indicated that updates to the National Planning Policy Framework are under consideration, with emphasis on climate adaptation. However, balancing housing demand against environmental constraints remains politically challenging, particularly in regions facing acute housing shortages. Industry observers suggest that a coordinated approach involving insurers, developers, and policymakers will be essential to prevent the scenario outlined by the Aviva chief executive from becoming a widespread reality.
For prospective homebuyers, the warning serves as a reminder to carefully investigate flood risk before purchasing property, including reviewing Environment Agency maps and seeking specialist advice. Real estate professionals recommend that buyers consider long-term insurance availability as a critical factor in their decision-making process. As the climate continues to change, the intersection of housing policy, insurance markets, and environmental reality will demand increasingly urgent attention from all stakeholders.
The insurance sector's growing reluctance to cover high-risk properties represents a market signal that cannot be ignored. While technological innovations and improved flood defenses offer some hope, the fundamental challenge remains addressing the root causes of increased flooding. Blanc's comments, delivered with characteristic directness, have reignited debate about the future of housing in vulnerable areas and the collective responsibility to build more resilient communities.
