
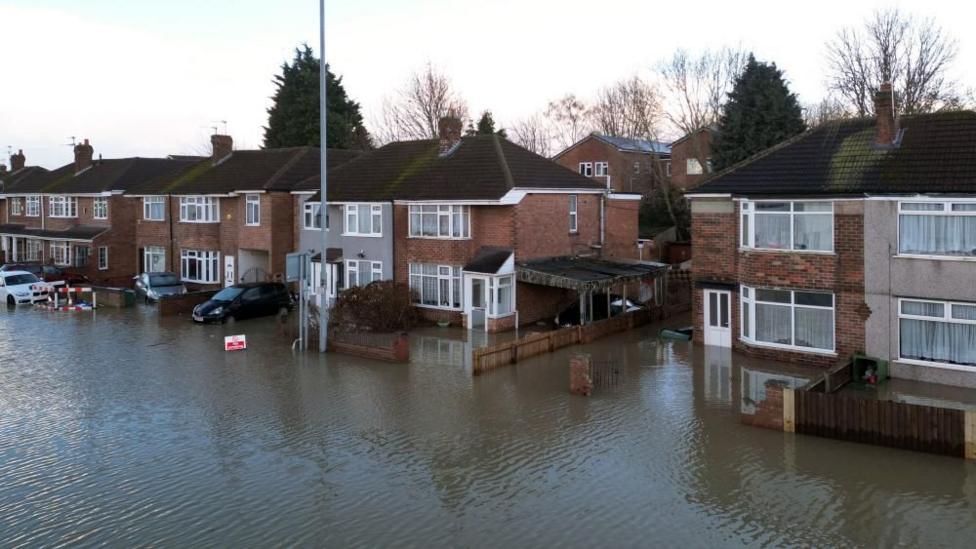
Aviva Boss Issues Stark Warning on Flood-Prone Development
Amanda Blanc, chief executive of Aviva, has issued a stark warning that England is "for sure" constructing homes that may become uninsurable in the future due to escalating flood risk. Her comments, delivered during a recent industry briefing, highlight a growing tension between national housing targets and climate adaptation. Blanc's statement signals that current planning decisions could lock in severe financial and safety liabilities for homeowners and insurers alike.
The warning comes amid increasing scrutiny of where and how the UK builds new housing. With a national target of 300,000 new homes per year, developers have often turned to flood-prone areas, particularly in the south and east of England. Blanc emphasized that the insurance industry cannot indefinitely absorb the rising costs associated with climate-driven weather events, making proactive planning reform an urgent necessity rather than an optional consideration.
Why Flood Risk Is Becoming a Critical Factor for Insurers
Insurers assess flood risk using sophisticated models that factor in historical data, river levels, coastal erosion, and future climate projections. As these models become more precise, properties located in high-risk zones are increasingly priced out of standard coverage. Aviva's internal analysis reportedly shows that a significant percentage of new developments in certain regions could fall into this category within decades, making them effectively uninsurable without substantial government intervention.
The financial implications are profound. A home that cannot be insured is difficult to mortgage, which in turn depresses property values and traps homeowners in assets that are both costly and risky. Blanc's comments suggest that the industry is reaching a tipping point where risk-based pricing will no longer be sufficient, and that the burden must shift to land-use planning and infrastructure investment to prevent future crises.
Government Planning Policies Under Scrutiny
Current planning guidelines permit development on flood plains under certain conditions, provided that mitigation measures such as raised floor levels or flood defenses are implemented. However, critics argue that these measures are often inadequate given the pace of climate change. Blanc's intervention adds weight to calls from environmental groups and local councils for stricter controls on building in areas with high flood probability, even if such measures slow down housing delivery.
The Ministry of Housing, Communities and Local Government has stated that it keeps flood risk guidance under constant review. Yet, industry analysts point out that the political imperative to build more homes often overrides environmental caution. The result is a patchwork of decisions that fail to account for long-term climate trajectories, leaving future generations to bear the cost of today's myopic planning choices.
Impact on Homeowners and the Property Market
For existing homeowners, the threat of uninsurability is already materializing in some flood-affected communities. Premiums have risen sharply, and in worst-case scenarios, insurers have refused to renew policies altogether. This has a chilling effect on local economies, as businesses struggle to secure coverage and property sales collapse. The situation is particularly acute in areas like the Somerset Levels and parts of Yorkshire, where repeated flooding has made reliable insurance a distant memory.
Prospective buyers are also becoming more cautious, often requiring flood risk assessments before making offers. Real estate professionals report that properties in high-risk zones are taking longer to sell and fetching lower prices, creating a two-tier market that penalizes owners who cannot afford to relocate. Blanc's warning is likely to accelerate this trend, as lenders and insurers tighten their criteria in response to public statements from industry leaders.
The Role of Climate Adaptation and Mitigation
While reducing carbon emissions remains the ultimate solution, adaptation measures are equally vital to protect existing and future housing stock. Investments in natural flood management, such as restoring wetlands and creating river overflow areas, have proven effective in mitigating damage. Additionally, upgrading drainage systems and maintaining flood defenses are essential, yet these projects require sustained funding that has been inconsistent across different government budgets.
Blanc has previously advocated for a dedicated infrastructure fund to address climate resilience, and her latest remarks reinforce this call. Industry experts suggest that a portion of the new homes levy could be ring-fenced for flood defense projects, ensuring that development pays for its own protection. Without such mechanisms, the gap between where homes are built and where they should be built will continue to widen, leaving insurers with impossible choices.
What This Means for Future Housing Policy
The insurance sector's growing unease is a powerful signal that housing policy must evolve beyond simple unit counts. Future decisions should incorporate climate risk as a core planning principle, with clear guidelines on where development is permissible. This may mean concentrating new housing in urban brownfield sites and areas with lower environmental vulnerability, even if such locations are more expensive to develop in the short term.
The upcoming review of the National Planning Policy Framework presents a critical opportunity to embed these principles. Environmental charities, local authorities, and now major insurers are aligned in urging the government to act decisively. The cost of inaction is not merely financial; it involves the safety and security of thousands of families who may find themselves without adequate protection in the face of increasingly volatile weather patterns.
As Blanc's warning reverberates through the industry, the message is clear: the era of building without consequences is over. England must choose between short-term housing targets and long-term climate resilience. The decisions made in the next few years will determine whether the nation's housing stock is a source of stability or a liability for generations to come. Insurers have sounded the alarm; policymakers must now respond with the urgency the situation demands.
