
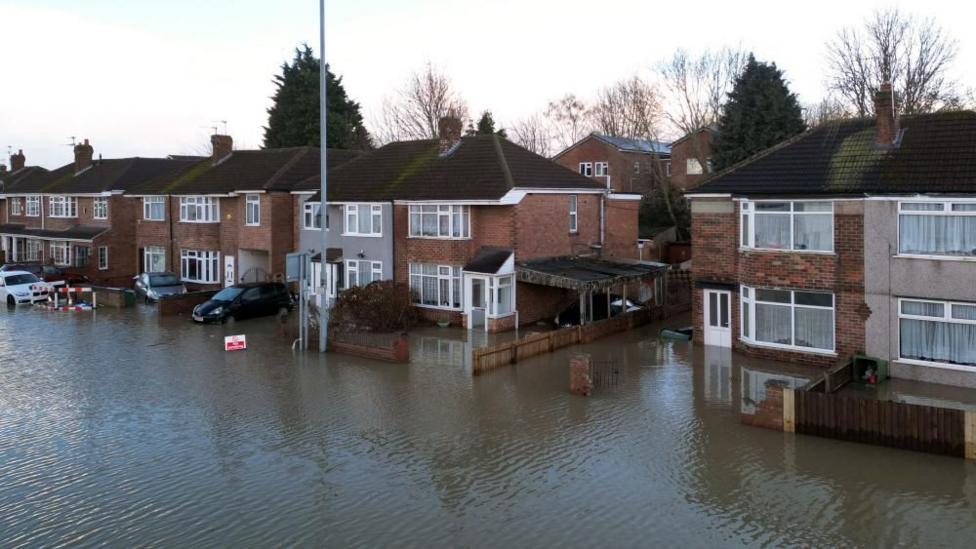
Aviva chief executive Amanda Blanc has issued a stark warning that England is "for sure" constructing homes that may become uninsurable in the future due to escalating flood risks. Speaking at a recent industry event, Blanc highlighted the urgent need for planning reforms to address climate-related threats. Her comments signal growing concern among major insurers about the sustainability of current building practices in flood-prone areas.
Aviva CEO's Stark Warning on Future Home Insurability
Blanc's statement underscores a critical intersection between housing policy and climate resilience. She emphasized that without immediate action, thousands of newly built properties could face severe insurance challenges. The Aviva boss pointed to scientific data indicating increased rainfall intensity and rising flood events, making some locations increasingly hazardous for residential development.
The warning comes as the UK government pushes forward with ambitious housing targets, aiming to build 300,000 new homes annually. Industry analysts note that many proposed developments are situated in areas with moderate to high flood risk, raising questions about long-term viability and affordability for prospective homeowners.
Blanc's remarks reflect a broader trend among insurance executives who are reassessing risk models in light of climate change. Several major insurers have already begun adjusting premiums and coverage terms for properties in vulnerable zones, with some refusing to insure new builds in high-risk flood areas altogether.
Flood Risk Data and Its Impact on Property Insurance
Recent official records show that nearly one in six properties in England currently faces some level of flood risk, a figure expected to rise significantly over the next decade. Government flood maps indicate that approximately 5.2 million homes are at risk, with 1.2 million considered high risk. These numbers are projected to grow as climate patterns shift.
Insurance industry analysts explain that flood risk is not static; it evolves with environmental changes and infrastructure development. New housing projects in floodplains often require expensive mitigation measures, such as raised foundations and flood defences, which can drive up construction costs and insurance premiums.
The financial implications for homeowners are substantial. Properties in high-risk flood zones can face premiums exceeding £5,000 annually, compared to the UK average of £300 for standard home insurance. In some extreme cases, insurers may decline coverage entirely, leaving homeowners with no viable protection options.
Government Response and Planning Policy Reforms
The UK government has acknowledged the growing concern, with the Department for Levelling Up, Housing and Communities reviewing planning guidelines to incorporate flood resilience requirements. Proposed changes include mandatory flood risk assessments for all new developments and stricter criteria for building in vulnerable areas.
However, critics argue that current reforms do not go far enough. Environmental groups and industry experts are calling for a complete ban on construction in areas with high flood risk, unless exceptional mitigation measures are implemented. They point to successful examples in the Netherlands, where innovative water management systems allow safe development in low-lying regions.
The Environment Agency has also updated its flood risk guidance, requiring developers to demonstrate that new homes will remain safe and insurable for their expected lifespan. This includes projections for future climate scenarios, not just current risk levels, which represents a significant shift in regulatory approach.
Economic and Social Consequences for Homeowners
The potential uninsurability of new homes poses serious economic risks for buyers, who may find their property values declining as flood risk increases. Mortgage lenders typically require valid home insurance as a condition for approving loans, meaning uninsurable properties could become effectively unsellable and unmortgageable.
This situation creates a potential trap for first-time buyers who may be attracted to lower-priced properties in flood-prone areas, unaware of future insurance implications. Housing advocates warn that these buyers could face significant financial losses if their properties become uninsurable, trapping them in assets they cannot sell or protect.
Local authorities in affected regions are also concerned about the impact on community development. Areas with high flood risk may struggle to attract new residents and businesses, potentially leading to economic stagnation and reduced property tax revenue for essential public services.
Industry Solutions and Future Outlook for Flood Resilience
Insurers and urban planners are exploring innovative solutions to address the flood risk challenge. These include developing flood-resistant building materials, implementing natural flood management techniques, and creating financial mechanisms to pool risk across larger geographic areas.
Aviva and other major insurers have invested in flood resilience research, partnering with academic institutions to develop better risk assessment tools. These efforts aim to provide more accurate, property-specific data that can inform both insurance pricing and planning decisions.
Industry analysts predict that the insurance market will increasingly differentiate between properties that incorporate flood resilience measures and those that do not. This could create financial incentives for builders to adopt flood-resistant designs, potentially reducing long-term risks and costs for homeowners.
Looking ahead, Blanc's warning serves as a catalyst for broader conversations about sustainable development in an era of climate change. The challenge lies in balancing the urgent need for new housing with the imperative to build in locations that remain safe and insurable for decades to come.
