
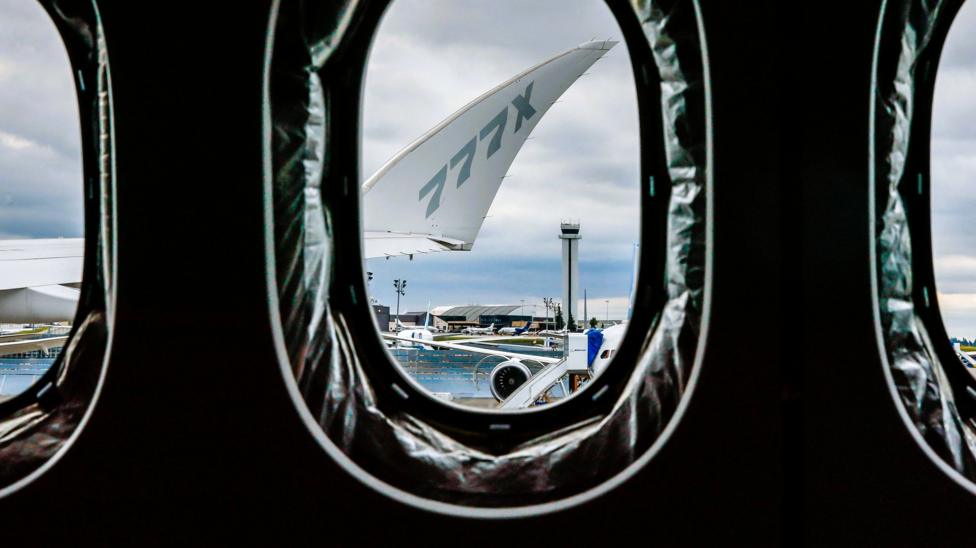
Aircraft Windows: A Niche Industry Faces Mounting Pressure
The production of aircraft windows has evolved into a highly specialized engineering domain, yet the industry now confronts unprecedented technical and supply chain hurdles. Only a handful of manufacturers worldwide possess the advanced capabilities needed to craft these critical components. Industry analysts report that the barriers to entry have risen sharply, driven by stringent safety standards and the demand for lighter, more durable materials.
This concentration of expertise has created a fragile ecosystem where any disruption can ripple across the global aviation sector. Recent regulatory filings and defense briefings highlight that the number of certified suppliers has remained static over the past decade, even as aircraft production rates climb. The result is a bottleneck that airlines and planemakers must navigate carefully, balancing cost pressures against uncompromising safety requirements.
The Science Behind the Porthole: Materials and Design Evolution
Modern aircraft windows are far from simple glass panes. They typically consist of multiple layers of stretched acrylic or chemically strengthened glass, designed to withstand extreme pressure differentials at cruising altitudes. Each layer serves a distinct purpose, from structural integrity to fail-safe redundancy in the event of cracking. The outer pane bears the primary load, while inner layers provide backup and thermal insulation.
Engineering teams now employ computer-aided modeling to simulate stress distribution, bird strikes, and thermal cycling. The shape itself—an oval or rounded rectangle—is not aesthetic but functional, distributing stress evenly around the corners. Industry analysts note that the shift toward larger windows in modern aircraft like the Boeing 787 has introduced new optical and structural complexities, requiring innovative manufacturing processes to maintain clarity and strength.
Why Fewer Firms Can Meet the Demanding Standards
The certification process for aircraft window manufacturers is notoriously rigorous. Regulatory bodies such as the Federal Aviation Administration and the European Union Aviation Safety Agency mandate extensive testing, including pressure cycling, impact resistance, and optical quality verification. These requirements demand significant capital investment in precision equipment and cleanroom facilities, which many potential entrants cannot justify.
Furthermore, the raw materials themselves are specialized. Aerospace-grade acrylic must meet exacting purity and consistency standards, while glass variants require advanced coating technologies to reduce glare and manage cabin pressure. Suppliers must maintain tight tolerances measured in microns, a level of precision that few industrial operations can achieve consistently. This technical barrier has effectively created an oligopoly, with long-standing players dominating the market.
Supply Chain Strains and the Push for Innovation
Recent disruptions in global logistics have exposed the fragility of this concentrated supply chain. A single plant shutdown or raw material shortage can delay deliveries for months, affecting aircraft production schedules worldwide. Airlines have reported increasing lead times for replacement windows, prompting some to explore alternative sourcing options, though none have yet matched the established quality benchmarks.
In response, manufacturers are investing in automation and artificial intelligence to enhance quality control and reduce waste. Some are experimenting with new composite materials that promise lighter weight and better impact resistance. However, these innovations require years of testing and certification before they can be deployed in commercial aircraft, keeping the near-term outlook conservative.
Economic and Operational Impact on the Aviation Sector
The high cost of aircraft windows—each unit can run into tens of thousands of dollars—directly impacts airline operating budgets. Maintenance schedules must account for window replacement cycles, and any unplanned failures can ground aircraft for extended periods. Industry analysts estimate that window-related issues account for a small but significant fraction of unscheduled maintenance events each year.
For planemakers, the limited supplier base creates negotiating leverage for incumbents, potentially inflating prices. This dynamic has caught the attention of regulators, who monitor market concentration in safety-critical components. While no formal antitrust action has been initiated, officials have urged the industry to explore redundancy measures to ensure resilience.
Future Outlook: Can the Industry Keep Pace with Demand?
Looking ahead, the aviation industry's projected growth—driven by rising passenger traffic and fleet modernization—will intensify pressure on window manufacturers. To meet this demand, firms must expand capacity while maintaining impeccable safety records. Some are partnering with research institutions to develop next-generation materials that could simplify production and reduce costs.
Yet, the path to certification remains a formidable hurdle. Any new entrant must navigate a multi-year process, and even established players face the challenge of scaling up without compromising quality. Industry analysts suggest that collaborative approaches, such as shared R&D consortia, might be the most viable route to innovation in this niche field.
For passengers, the humble window is a symbol of flight itself—a portal to the skies. For engineers, it represents a masterclass in material science and precision manufacturing. As the industry evolves, the commitment to safety and performance will remain paramount, ensuring that this small but critical component continues to meet the highest standards.
The extreme engineering behind aircraft windows is a testament to human ingenuity, yet it also underscores the vulnerabilities inherent in specialized industries. By fostering innovation and resilience, the sector can navigate the challenges ahead, keeping the world flying safely and comfortably.
